


SkiStar (OM:SKIS B) Raised Its Dividend And Investment Plans, Is It Still Undervalued?
SkiStar (OM:SKIS B) is back in focus after reporting full-year results alongside a higher proposed dividend and fresh spending on lifts, gondolas, and accommodation across its Scandinavian resorts.
SkiStar’s 1 year total shareholder return of 9.0% and 3 year total shareholder return of 73.2% point to solid longer term rewards, even though the 1 month share price return of 2.9% and a small dip over the past week signal cooling short term momentum as investors digest the higher dividend and ongoing resort investment plans.
Scan how SkiStar compares with other potential resort and leisure opportunities by reviewing the curated 176 high quality undervalued stocks that combine cash flow strength with balance sheet support.
SkiStar now trades at SEK 165.20 while analyst targets cluster near SEK 193, and some intrinsic value work points to an even wider gap. Is that discount really justified by the risks investors see?
Most Popular Narrative: 14% Undervalued
SkiStar’s most followed valuation story puts fair value at about SEK 191.67 per share, above the recent SEK 165.20 close. This frames today’s discount as a question of whether its resort investments and forecast margins can materialise as expected.
The investment in new gondolas and ski lifts in Trysil and Are, along with anticipated developments in these ski areas, are expected to significantly enhance customer experience and capacity, potentially boosting future revenue from increased ski pass sales and accommodation. The expansion and development of the Vemdalen ski area and the addition of 500 new beds in Salen are likely to increase accommodation availability and attractiveness of these destinations, driving higher occupancy rates and associated revenue growth.
See why 4 investors see SkiStar as 14% undervalued.
Result: Fair Value of SEK191.67 (UNDERVALUED)
Still, that apparent discount sits alongside weather-driven costs that have already pressured margins, as well as heavy capital spending on lifts and snow systems that can strain cash flow if conditions disappoint.
Find out about the key risks to this SkiStar narrative.
Another View: What SkiStar’s P/E Is Telling You
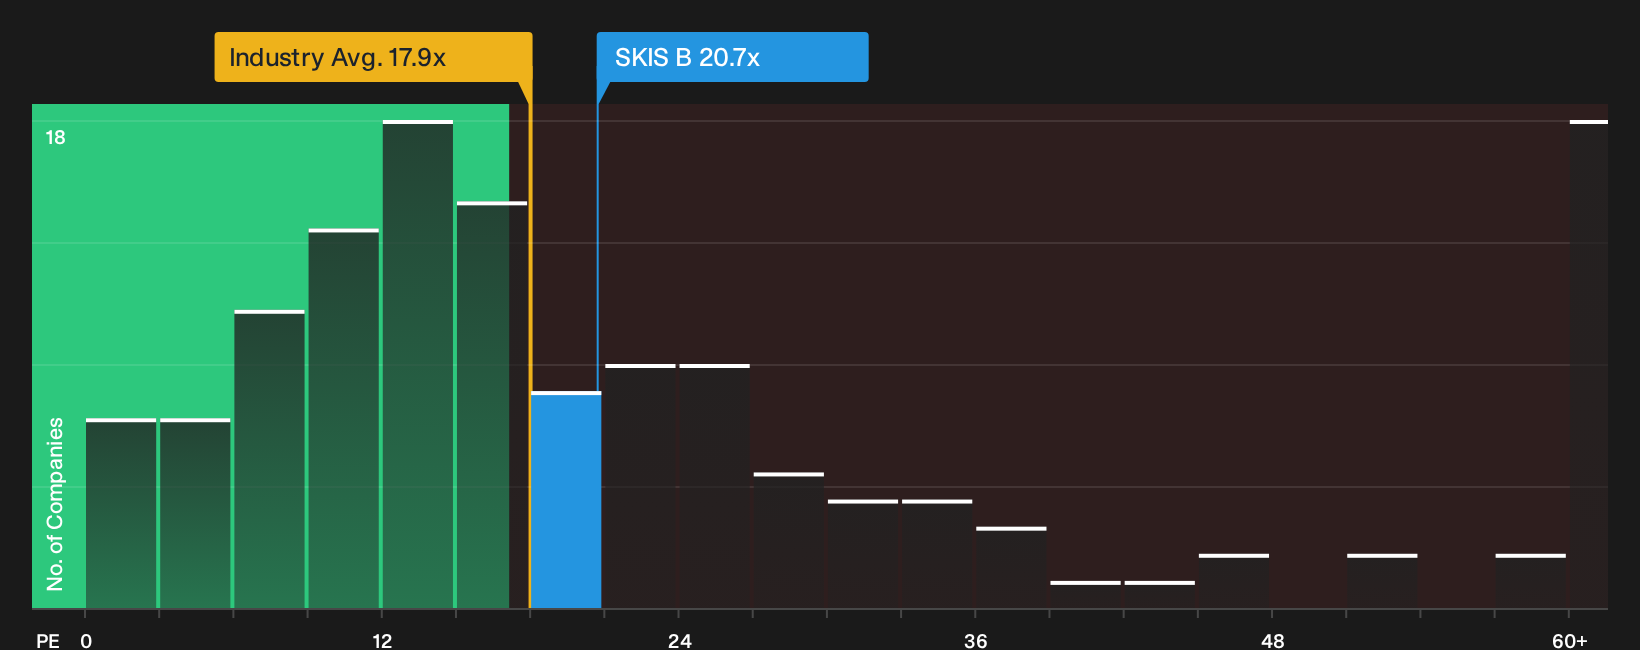
There is a very different message once you switch from SkiStar’s cash flow story to the simple P/E yardstick. At around 20.7x earnings, the stock trades well above the Swedish Hospitality industry on 17.8x, the peer group on 15x, and a fair ratio estimate of 12.4x, which implies meaningful valuation risk if sentiment cools.
For anyone weighing up these mixed signals, it helps to see what the numbers imply if the market leans back toward that fair ratio over time, and how that compares to today’s pricing See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on SkiStar’s value story will not resolve themselves, so evaluate the potential upside and downside for yourself while the market is still pricing in both 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond SkiStar?
If SkiStar has sharpened your eye for opportunity, do not stop here. Broaden your watchlist now so you are not reacting after the best ideas move.
- Target resilient income by reviewing 223 dividend fortresses that could help anchor a portfolio with ongoing cash returns.
- Hunt for potential bargains early through the curated 618 high quality undiscovered gems before wider attention bids prices up.
- Reduce portfolio stress by scanning 223 resilient stocks with low risk scores built around stronger balance sheets and lower risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com