


Record Backlog Might Change The Case For Acciona Stock (BME:ANA)
- Acciona's infrastructure arm has reached a record backlog of €54b in projects and concessions, tying long-term work closely to Spain's economy and its global construction footprint.
- The sheer scale of this committed project pipeline gives Acciona a high degree of visibility on future activity, while also concentrating execution and margin risk in long duration contracts.
- We will now look at how Acciona's record infrastructure backlog could reshape the investment narrative investors use to judge the business.
Scan beyond Acciona and stress test your thesis against a curated 43 power grid technology and infrastructure stocks focused on the same long-term infrastructure and grid upgrade theme.
Acciona Investment Narrative Recap
To own Acciona, you need to trust the mix of long dated infrastructure work and renewable assets can convert a €54b backlog into steady cash generation. The short term swing factor is simple. How efficiently those construction and concession contracts move from awarded to invoiced without fresh cost surprises hitting already thin 1.6% net margins.
Risk cuts the other way through balance sheet strain. Interest costs are not comfortably covered, the dividend is not well backed by free cash flow, and big one off items cloud underlying profit quality. The record backlog does not change those pressure points much yet. It just raises the execution stakes.
Among recent developments, the all time high infrastructure backlog is the clearest operational signal for this story. It links directly to the main catalyst investors are watching: the ability of Acciona to turn committed roads, rail, water and concessions work into more predictable revenue and, over time, better project level profitability.
That same announcement also sharpens the main risk. A larger book of long duration projects means more exposure to delays, cost over-runs and any future need to rotate assets to manage leverage. For you as a shareholder, the question is less about the headline €54b figure and more about how cleanly it flows through to earnings and cash.
Acciona's analyst narrative points to €22.8b in revenue and €681.8m in earnings by 2029, based on an assumed 1.4% yearly revenue growth rate and an earnings increase of about €321.8m from current earnings of €360.0m.
Uncover how Acciona's fair value indicates a 3% potential upside to its current price before that discount narrows.
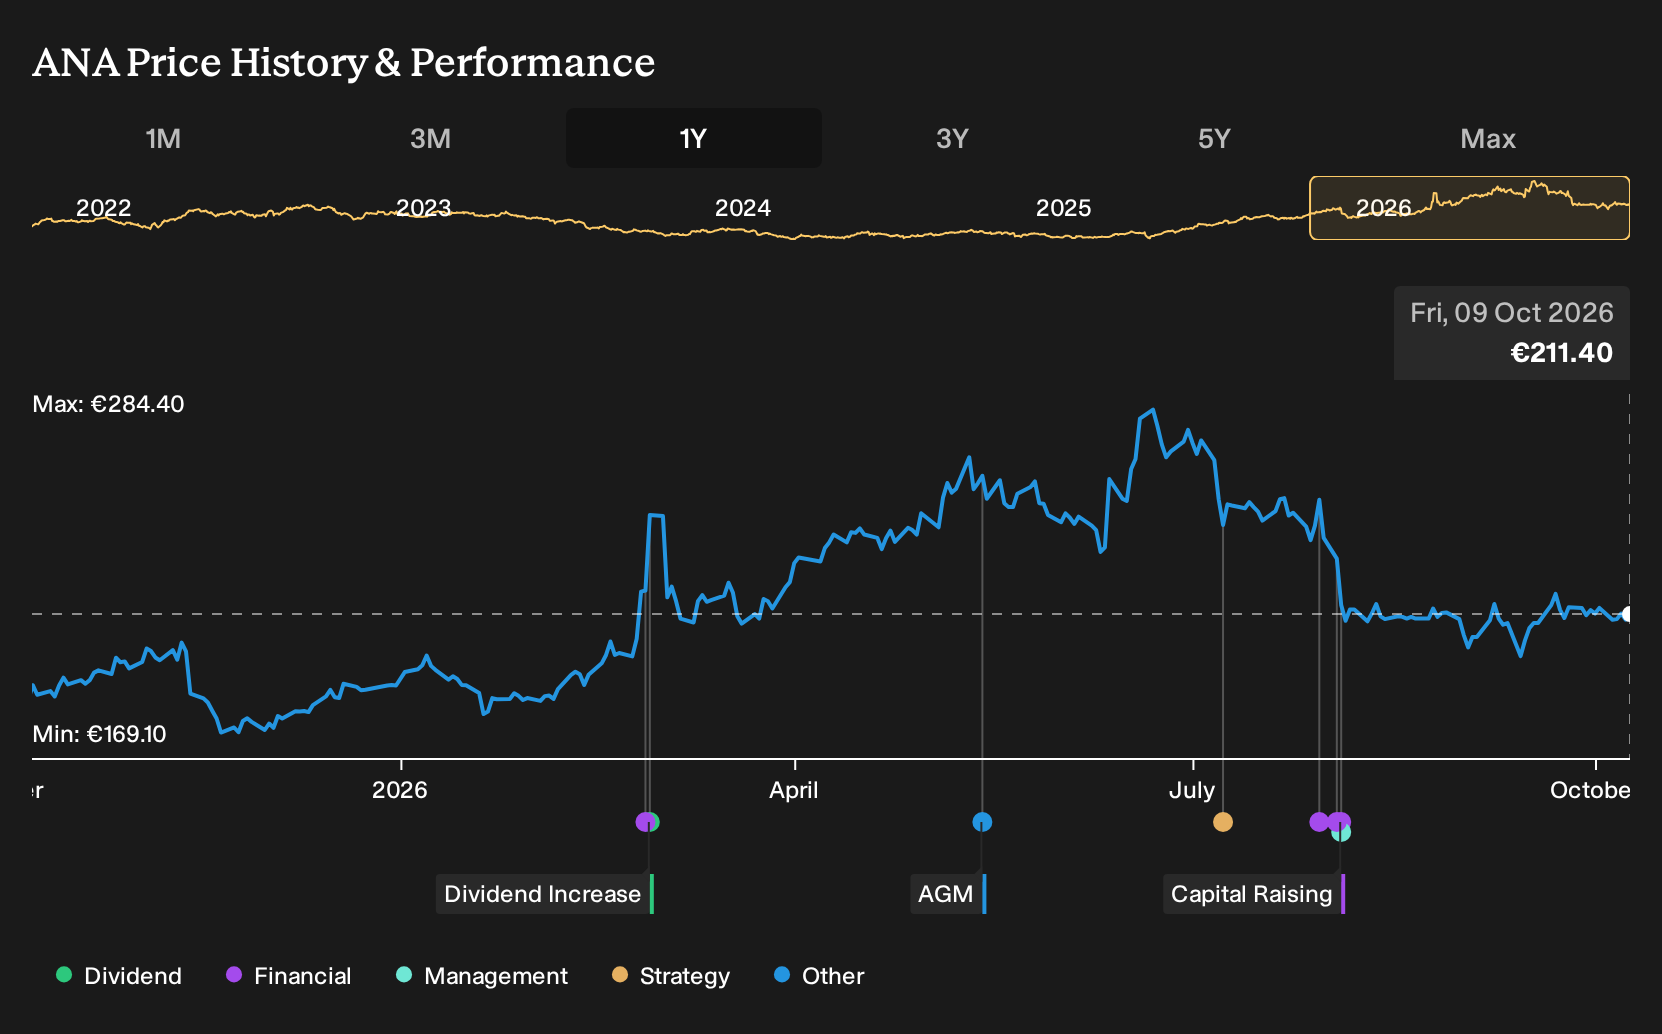
Exploring Other Perspectives
One alternate view puts Acciona’s net debt of about €8.2b at H1 2026 front and center. The most cautious analysts worry that weaker captured power prices and slower asset rotations could squeeze earnings, which is why their 2029 revenue and profit path sits nearer €21.1b and €463.5m. That gap to the consensus view is wide. Use it as a prompt to test how this new backlog news might reshape both scenarios.
Explore 2 other Acciona fair value estimates, including one that suggests as much as 82% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Acciona research is our analysis highlighting 1 key reward and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Acciona. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Acciona's overall financial health at a glance.
Looking For More Investment Ideas Beyond Acciona?
If Acciona has sharpened your view on long term infrastructure and cash flow quality, broaden that lens across the market using the Simply Wall St Screener. You can quickly filter for different balance sheet profiles, income streams, and risk levels to see how other businesses stack up against the questions this stock raises.
- If capital preservation is high on your list, start with a set of 223 resilient stocks with low risk scores that prioritise resilience and more measured risk profiles.
- If dependable income is what you are after, review a curated group of 223 dividend fortresses that pair higher yields with scrutinised payout histories.
- If you want to spot opportunities before the crowd, scan through a hand picked 618 high quality undiscovered gems built around strong fundamentals and lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com