


How Green Energy Expansion At Trelleborg (OM:TREL B) Has Changed Its Investment Story
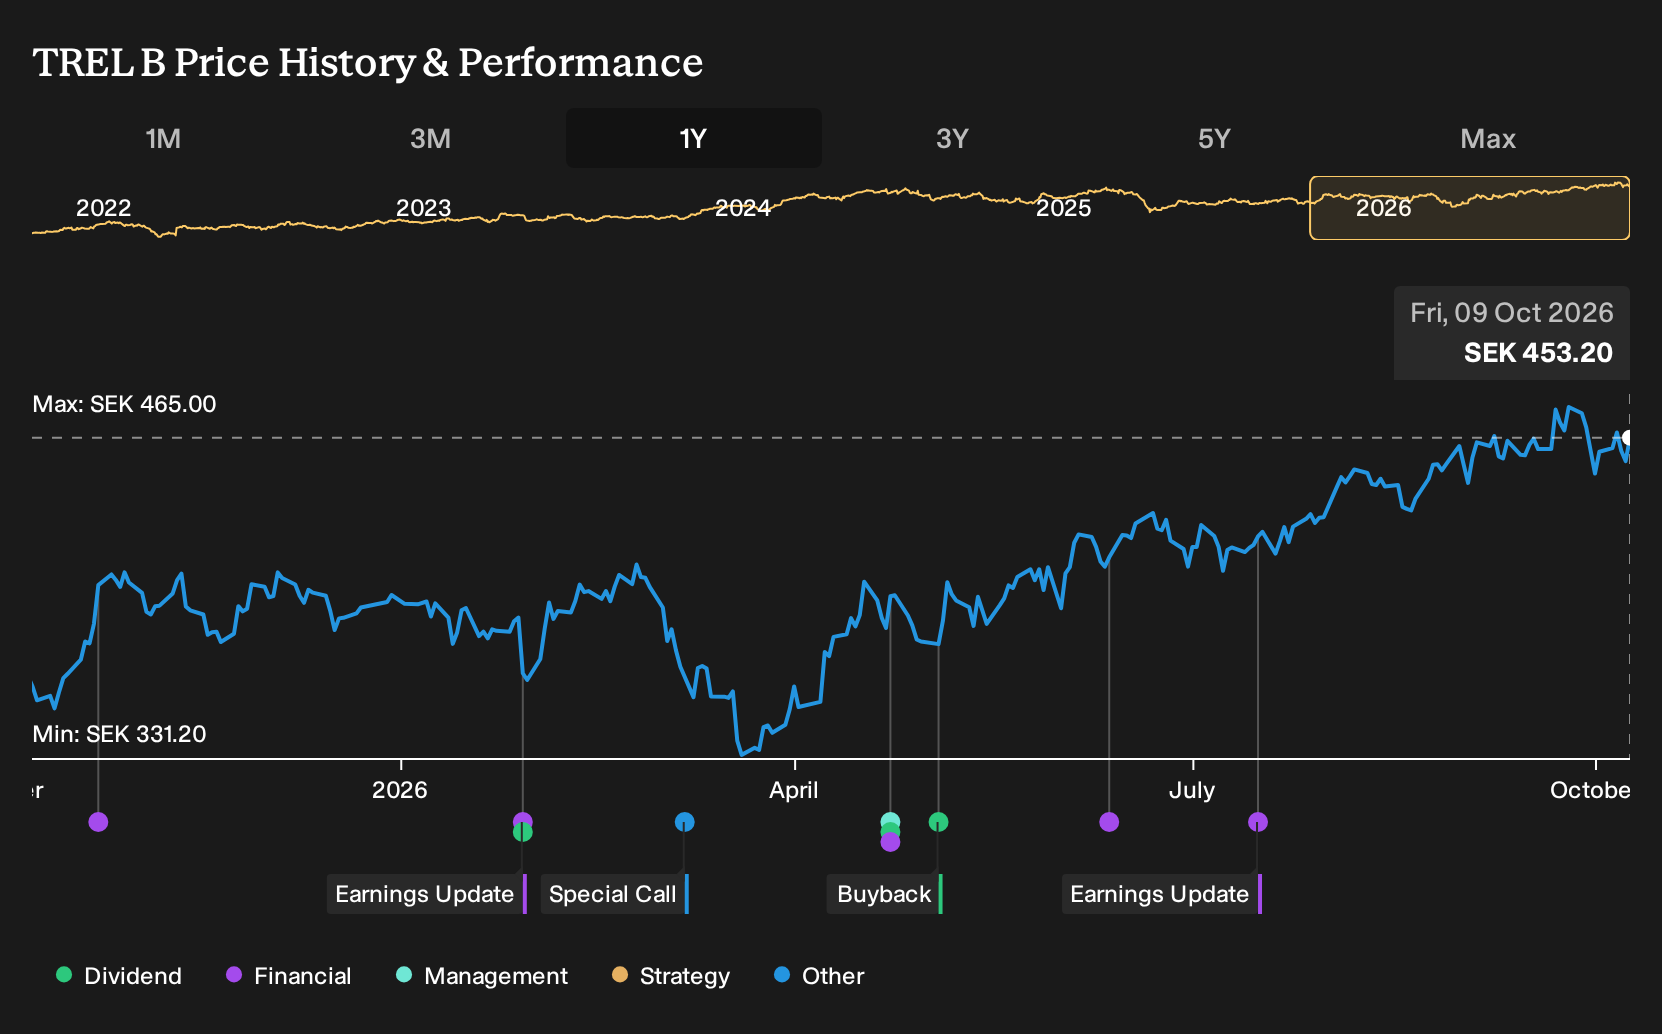
- Trelleborg is at the center of a fresh valuation debate as investors weigh analyst free cash flow projections against rising capital expenditure needs and expansion into green energy related markets.
- The key question now is whether Trelleborg's cash generation and investment program in areas like wind and LNG infrastructure can support its current valuation without stretching the balance sheet.
- We will look at how Trelleborg's investment narrative intersects with rising capex plans that support green energy expansion and projected cash flows.
Compare Trelleborg's green energy expansion story with other balance-sheet focused opportunities by scanning our list of solid balance sheet and fundamentals (204 results), which could also support heavy investment programs without overreaching.
Trelleborg Investment Narrative Recap
Trelleborg appeals to shareholders who trust its mix of engineered polymer know how and exposure to automation, medtech, and green energy projects. To stay comfortable, you need to believe that cash generation can keep pace with heavier capex and that new projects in wind, LNG, and infrastructure translate into solid orders rather than just headlines.
The recent discussion around free cash flow versus valuation does not materially alter the near term business catalyst. Execution on integration of past acquisitions and delivery from new facilities remains the swing factor. The bigger immediate risk is prolonged weakness and volatility in automotive, which could weigh on organic volumes and margins.
Absent fresh announcements tied directly to this valuation debate, the most relevant context is Trelleborg’s ongoing push into green energy and higher growth segments through prior acquisitions and capacity investments. Those moves are intended to spread exposure beyond cyclical areas like automotive and into longer duration project work such as wind and LNG infrastructure.
For you, the operational question is whether these acquired units and new plants can run at healthy utilization without eroding profitability through integration friction. Project timing in energy infrastructure, the pace of automation spending, and stability in Medical Solutions volumes sit at the center of the near term catalysts and operational risk balance for Trelleborg.
Trelleborg's current analyst narrative points to SEK43.2b in revenue and SEK5.9b in earnings by 2029, anchored on 7.6% yearly revenue growth and an earnings increase of about SEK2.1b from SEK3.8b today.
Uncover why Trelleborg's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate view focuses on project lumpiness rather than green energy upside. If you worry about delayed tunnel, marine and energy work, then the lowest analysts look closer to your camp. They were pencilling in SEK40.3b of revenue and SEK5.4b of earnings by 2029, on a lower 16.5x P/E, before this latest Trelleborg news.
Explore 2 other Trelleborg fair value estimates, including one that suggests it could be worth just SEK459.45.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Trelleborg research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Trelleborg. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trelleborg's overall financial health at a glance.
Looking For More Ideas Beyond Trelleborg?
If you want to stress test the Trelleborg thesis against other potential holdings, it helps to line it up next to companies with different cash flow profiles, payout policies, and balance sheet strength. The Simply Wall St Screener gives you a quick way to surface those alternatives without getting buried in raw data.
- If capital preservation sits high on your priority list, compare Trelleborg with other resilient businesses by reviewing a group of 223 resilient stocks with low risk scores that aim to keep drawdowns in check.
- If you are hunting for value, set Trelleborg beside companies trading on more modest valuations by scanning a curated set of 176 high quality undervalued stocks that already show solid fundamentals.
- If income matters just as much as price appreciation, weigh Trelleborg against a collection of 223 dividend fortresses that combine higher yields with an emphasis on payout resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com