


Clover Health (CLOV) Stock Looks Reasonable Despite New 5 Star Ratings
Clover Health Investments has seen sharp swings in its share price in recent years, and the stock closed at US$4.79 most recently. With the business in the spotlight after new Medicare plan ratings, the question for investors is whether that price can be explained by its sales.
- The stock has delivered a very large 3 year return of about 365.0%, which puts a lot of weight on whether current revenue levels and future top line potential can support today’s valuation.
- Clover Health’s Medicare Advantage PPO plans received a 5 Star rating for 2027 and membership reached about 157,000, which may support expectations for stronger sales as the company can attract members year round and reinvest in richer benefits.
- Your read on Clover Health Investments is one view; the desks covering it have another. See what analysts think Clover Health Investments's shares could be worth.
The stock’s next move may depend on whether Clover Health’s current market value is justified by the sales it is generating today and the revenue it is realistically positioned to earn over time.
If you want a wider starting list while you research Clover Health Investments and its Medicare-focused story, apply the same approach to review 34 healthcare AI stocks.
Where Does Clover Health Investments Sit on Sales?
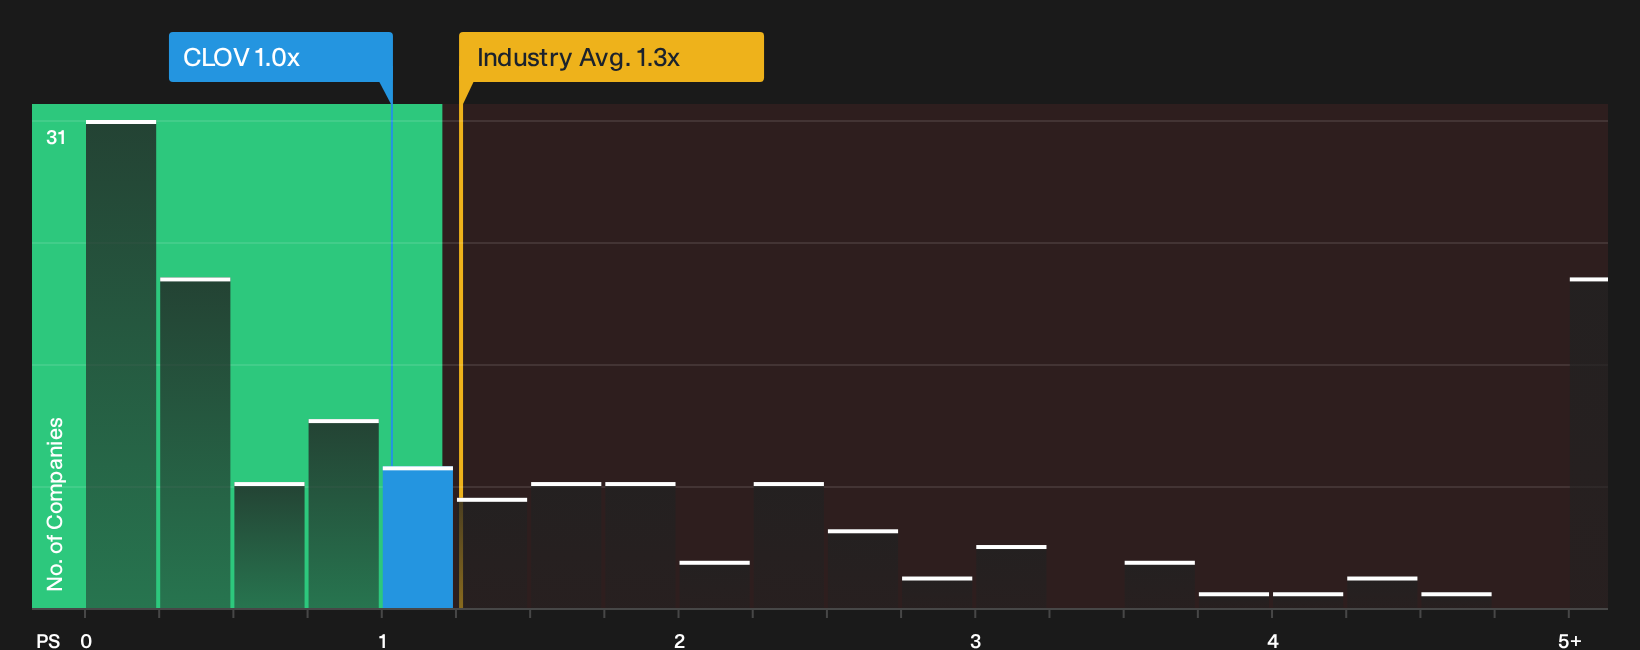
The P/S ratio suits Clover Health Investments because investors are mainly paying for its Medicare-focused revenue rather than current earnings. At roughly 1.0x P/S, the stock trades slightly below the wider Healthcare sector average of about 1.3x and also below the peer group near 2.0x. That means each dollar of Clover Health’s sales is priced more cautiously than many comparable healthcare stocks.
The Fair Ratio model, which adjusts the benchmark multiple for Clover Health’s size, margins, business risks and industry, points to a P/S very close to where the shares change hands today. Because the recent 5 Star rating is already known and has lifted sentiment, the current valuation suggests the market is not paying a big premium for that news. For a reader comparing options in Healthcare, the key question is whether Clover Health’s Medicare Advantage positioning and revenue quality justify paying roughly this sales multiple instead of a higher one elsewhere. Explore the numbers behind Clover Health Investments's P/S valuation.
The Clover Health Investments Narrative: What Would Justify Today's Price?
Clover Health Investments' Simply Wall St Narratives pick up where the P/S discussion leaves off by spelling out which paths for revenue, margins and earnings would need to play out for the current share price to look either conservative or stretched. Rather than a single multiple or model output, each narrative lays out the assumptions behind its view of fair value so you can line those up against future results as they are reported on the Community page.
One of the top community narratives on Clover Health Investments: 11% undervalued
"The Clover Assistant software platform and the non delegated risk model are viewed as key potential earnings drivers, which bullish analysts see as important…"
Discover why this Narrative puts Clover Health Investments at 11% undervalued.
One more Clover Health Investments signal worth checking before you move on
The valuation picture for Clover Health Investments only tells part of the story, because recent trading disclosures by people inside the business raise a separate set of questions that only you can judge. See the recent insider selling flagged for Clover Health Investments.

This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com