


Royal Bank Of Canada (TSX:RY) Could Be 8% Undervalued As Strong Q3 Earnings Land
Royal Bank of Canada (TSX:RY) just put fresh numbers on the table, with fiscal Q3 2026 net income reported at $6b and earnings per share higher by 13%. That financial update may influence how investors evaluate the stock today.
Royal Bank of Canada’s share price has pulled back recently, with a 7 day share price return of 1.84% lower and a 30 day share price return down 4%. However, the year to date share price return of 16.72% and 1 year total shareholder return of 39.85% indicate that momentum has been building over a longer stretch as debt issuance, new partnerships and product launches keep the story in focus.
Scan how Royal Bank of Canada’s latest earnings, capital strength, and funding moves compare with other large financial institutions by reviewing a curated set of 7 resilient stocks with low risk scores.
Royal Bank of Canada looks like a powerhouse on paper, with fresh earnings strength and active funding moves. The real tension now is simple. Are you paying a premium, or getting that quality at a reasonable tag?
Most Popular Narrative: 8% Undervalued
Royal Bank of Canada last closed at CA$273.78, while the most followed narrative pegs fair value around CA$298.79 based on a 7.2% discount rate and modeled cash flows. That gap puts the focus squarely on how its mix of AI, wealth growth and U.S. expansion could support those assumptions over time.
Strategic investments in AI and digitalization such as the ATOM Foundation and Lumina platform, expanded use of data analytics, and digital banking product launches are driving cost efficiencies, deeper customer engagement, and higher transaction volumes, which should support future revenue and net margin growth.
See why 169 investors see Royal Bank of Canada as 8% undervalued.
Result: Fair Value of CA$298.79 (UNDERVALUED)
Still, the story can break if credit losses stay elevated or if Canadian mortgage and commercial real estate exposures result in heavier impairments and weaker profitability.
Find out about the key risks to this Royal Bank of Canada narrative.
Another View: Royal Bank of Canada Through The P/E Lens
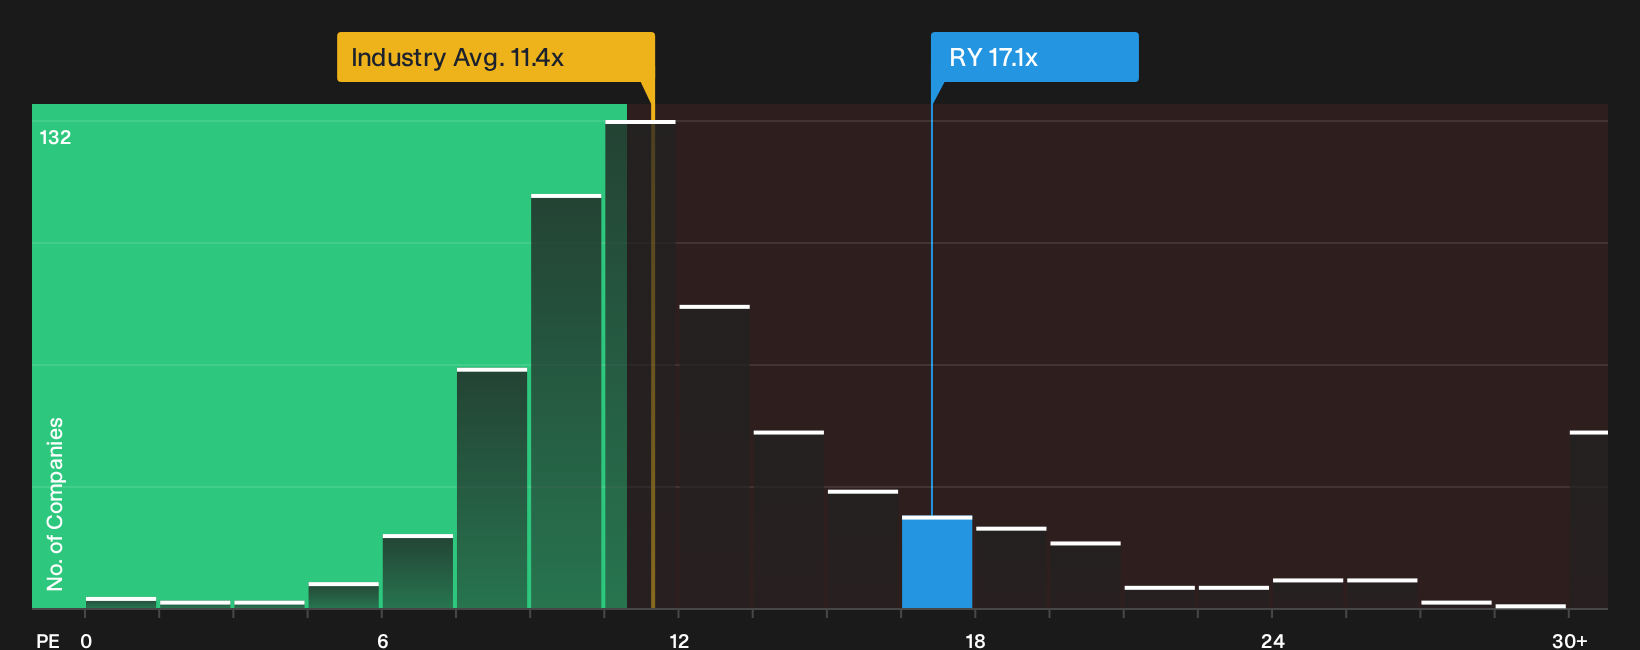
The DCF work points to Royal Bank of Canada trading below modeled fair value. The picture looks less comfortable when you zoom in on earnings. The stock trades on a P/E of 17.1x, compared with 11.4x for the North American banks group and 16.6x for its peer set, while the fair ratio for Royal Bank of Canada is 17.7x. That mix of a premium to the wider sector but only a small gap to the fair ratio raises a simple question: Is the earnings multiple giving you enough room for disappointment, or not quite enough margin for error?
To stress test that view against hard numbers, review how the current earnings multiple lines up with our valuation breakdown and where it could move over time, then decide which set of assumptions you trust most See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment looks split, which is exactly why the next move should be yours and based on what you see in the numbers, not headlines. To weigh both the concerns and the bright spots around Royal Bank of Canada in one place, take a closer look at the 4 key rewards and 1 important warning sign
Looking for more Royal Bank of Canada sized ideas?
If Royal Bank of Canada has sharpened your focus, keep that momentum going by scanning other opportunities that could complement or balance your portfolio.
- Target companies that combine quality and a potential value gap by reviewing a curated 9 high quality undervalued stocks that share strong fundamentals.
- Strengthen your income stream by assessing a focused set of higher yielding payers through the 3 dividend fortresses built for consistency seekers.
- Anchor your watchlist with resilient balance sheets by running through a pre filtered list of solid balance sheet and fundamentals (7 results) that can help steady overall risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com