


Don't Buy Vedanta Limited (NSE:VEDL) For Its Next Dividend Without Doing These Checks
It looks like Vedanta Limited (NSE:VEDL) is about to go ex-dividend in the next 2 days. The ex-dividend date is two business days before a company's record date in most cases, which is the date on which the company determines which shareholders are entitled to receive a dividend. The ex-dividend date is an important date to be aware of as any purchase of the stock made on or after this date might mean a late settlement that doesn't show on the record date. Thus, you can purchase Vedanta's shares before the 14th of October in order to receive the dividend, which the company will pay on the 7th of November.
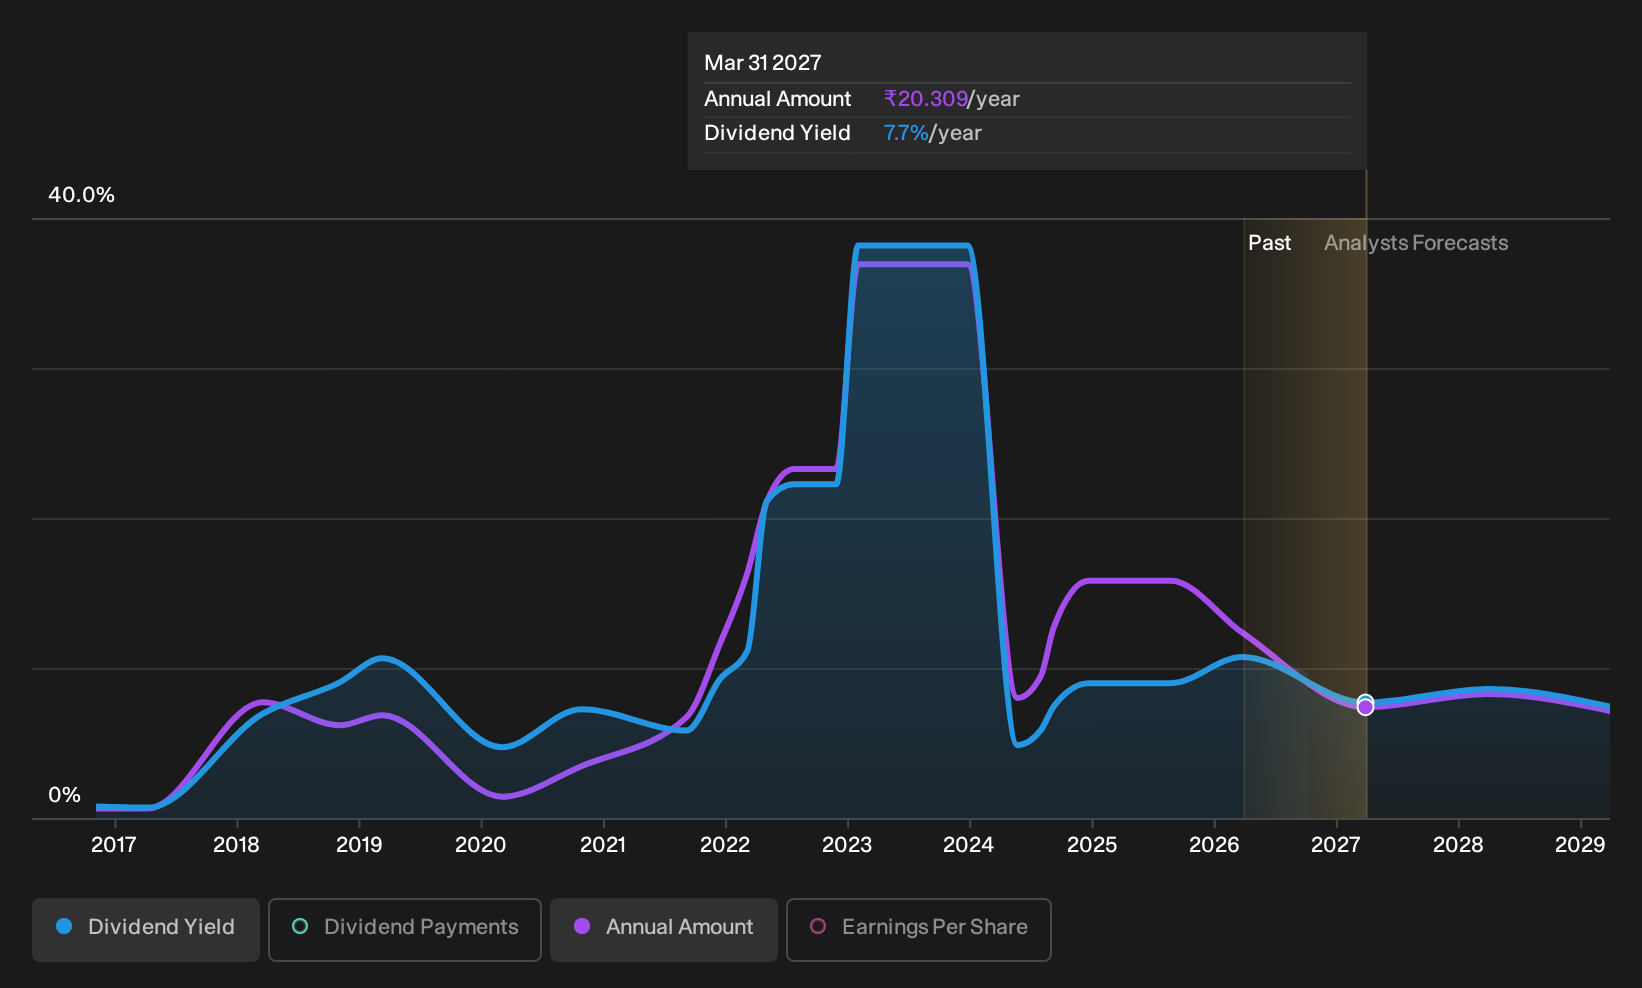
The company's next dividend payment will be ₹5.00 per share. Last year, in total, the company distributed ₹34.00 to shareholders. Based on the last year's worth of payments, Vedanta stock has a trailing yield of around 6.1% on the current share price of ₹264.00. Dividends are an important source of income to many shareholders, but the health of the business is crucial to maintaining those dividends. So we need to investigate whether Vedanta can afford its dividend, and if the dividend could grow.
If a company pays out more in dividends than it earned, then the dividend might become unsustainable - hardly an ideal situation. Vedanta distributed an unsustainably high 155% of its profit as dividends to shareholders last year. Without more sustainable payment behaviour, the dividend looks precarious. Yet cash flows are even more important than profits for assessing a dividend, so we need to see if the company generated enough cash to pay its distribution. Over the last year it paid out 71% of its free cash flow as dividends, within the usual range for most companies.
It's good to see that while Vedanta's dividends were not covered by profits, at least they are affordable from a cash perspective. If executives were to continue paying more in dividends than the company reported in profits, we'd view this as a warning sign. Very few companies are able to sustainably pay dividends larger than their reported earnings.
See our latest analysis for Vedanta
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Companies with falling earnings are riskier for dividend shareholders. If business enters a downturn and the dividend is cut, the company could see its value fall precipitously. Vedanta's earnings per share have fallen at approximately 11% a year over the previous five years. When earnings per share fall, the maximum amount of dividends that can be paid also falls.
Many investors will assess a company's dividend performance by evaluating how much the dividend payments have changed over time. In the last 10 years, Vedanta has lifted its dividend by approximately 8.6% a year on average. That's intriguing, but the combination of growing dividends despite declining earnings can typically only be achieved by paying out a larger percentage of profits. Vedanta is already paying out a high percentage of its income, so without earnings growth, we're doubtful of whether this dividend will grow much in the future.
Final Takeaway
From a dividend perspective, should investors buy or avoid Vedanta? It's never fun to see a company's earnings per share in retreat. Additionally, Vedanta is paying out quite a high percentage of its earnings, and more than half its cash flow, so it's hard to evaluate whether the company is reinvesting enough in its business to improve its situation. It's not an attractive combination from a dividend perspective, and we're inclined to pass on this one for the time being.
So if you're still interested in Vedanta despite it's poor dividend qualities, you should be well informed on some of the risks facing this stock. For example - Vedanta has 1 warning sign we think you should be aware of.
If you're in the market for strong dividend payers, we recommend checking our selection of top dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.