


Universal (UVV) Revenue Fell In Q1, Is The 37% Undervalued View Credible?
Universal (UVV) is back in focus after Q1 FY 2027 results showed consolidated revenue of US$524 million, down 12%, and operating income of US$2.3 million compared with US$33.8 million a year earlier.
The weak quarter has been met with selling pressure, with Universal’s share price down 7.0% over the past month and 17.6% over 3 months, while the 1 year total shareholder return is 14.9% lower but still positive over 3 and 5 years. This suggests recent momentum has faded, even though longer term holders have retained modest gains.
Spot opportunities beyond Universal’s recent pullback and scan a curated 28 high quality undervalued stocks that combine healthy cash flows with balance sheet strength.Bulls point to Universal’s weaker quarter and pullback as a chance to buy quality cash flows at a discount. Bears see a value trap taking shape. Which side do the numbers lean toward as valuation comes into focus?
Most Popular Narrative: 37% Undervalued
Universal last closed at $42 while the most followed narrative pegs fair value at $67. This wide gap puts future earnings power under the microscope.
Ongoing investments in new value-added ingredients facilities and products are beginning to deliver higher sales volumes and improved utilization, creating a platform for enhanced revenue diversification and long-term margin expansion as these operations scale. Consolidation among major tobacco manufacturers increases the importance of Universal's global footprint and reliability, reinforcing its pricing power and ability to secure long-term supply agreements, stabilizing both revenue and net margins.
See why 10 investors see Universal as 37% undervalued.
Result: Fair Value of $67 (UNDERVALUED)
Still, the expected oversupply in flue cured and burley tobacco and ongoing margin pressure in the Ingredients Operations arm could easily weaken the Universal narrative.
Find out about the key risks to this Universal narrative.
Another View: Universal Through The Earnings Multiple Lens
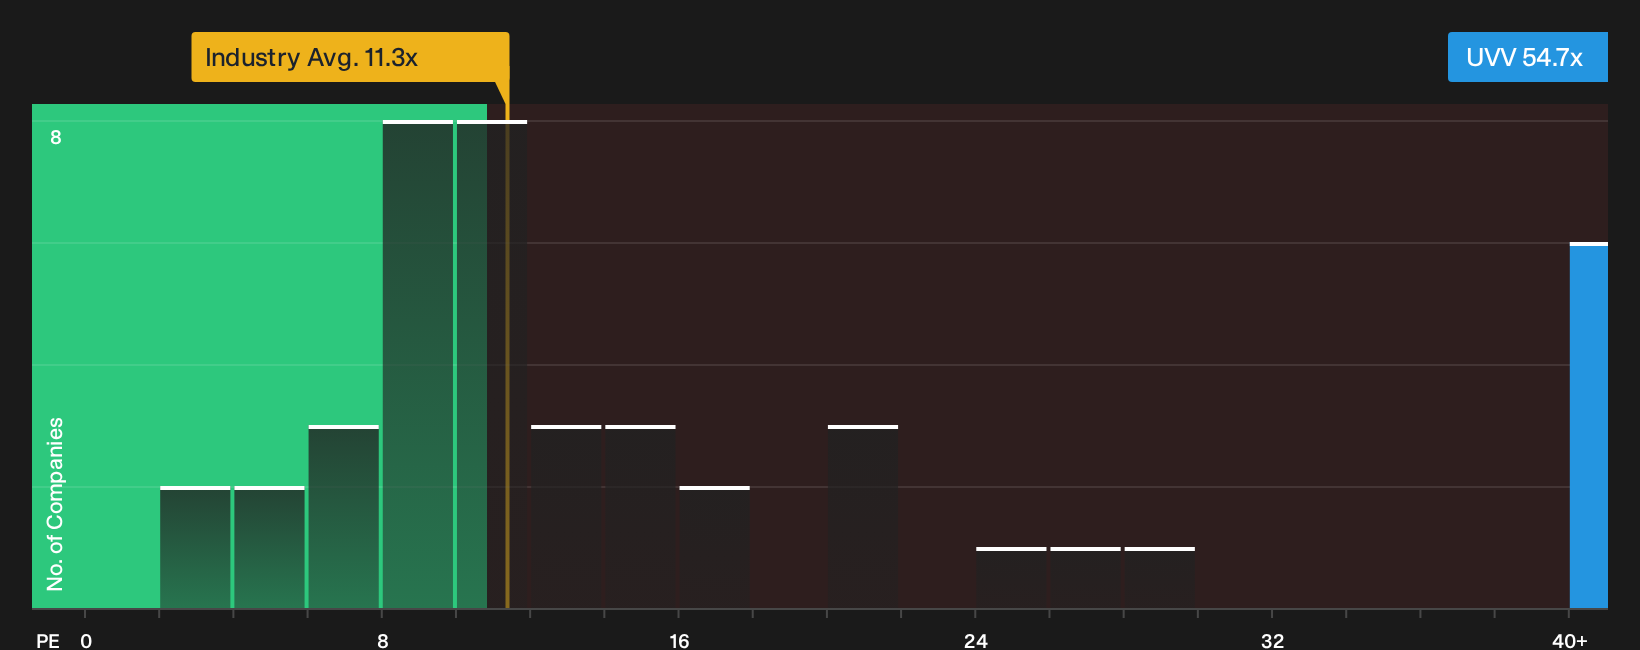
One valuation method suggests Universal looks inexpensive, yet the simple earnings ratio paints a tougher picture. The stock trades on a P/E of 54.7x, compared with 11.3x for the global Tobacco group and a peer average of 26.7x, while the fair ratio is 55.6x.
This puts Universal roughly in line with the fair ratio but far above sector and peer levels. It also suggests there may be meaningful valuation risk if sentiment, earnings quality, or forecasts reset. How comfortable are you owning a business where the current multiple already reflects a substantial amount of positive expectations?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Universal can pull sentiment in either direction, so move quickly, review the figures yourself and weigh up 2 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Universal?
If Universal now feels fully priced, broaden your opportunity set with other filters that spotlight different combinations of quality, value, and resilience.
- Hunt for mispriced strength by scanning a curated set of companies that screen as 28 high quality undervalued stocks before the crowd catches on.
- Build a sturdier income stream by reviewing businesses that qualify as 8 dividend fortresses and assess whether those payouts suit your goals.
- Dial down portfolio stress by focusing on companies that appear in our 31 resilient stocks with low risk scores, then decide which ones fit your risk comfort.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com