


Ensign Group (ENSG) Could Be 22% Undervalued Following Class Action Lawsuit
Ensign Group (ENSG) is in focus after a securities class action lawsuit accused the healthcare operator and several executives of widespread patient neglect, fraudulent billing practices, and misleading disclosures about regulatory and legal risks.
At a last close of $171.80, Ensign Group’s recent share price return has been modest, with the 90 day share price return of 2.03% contrasting with a 1 year total shareholder return that is down 1.87%. However, the 3 and 5 year total shareholder returns of 80.56% and 138.30% point to stronger longer term momentum, which is now being tested by the fresh legal and reputational questions raised in the class action and investigative reports.
Pressure test Ensign Group against peers facing fewer headline risks by scanning our hand-picked 31 resilient stocks with low risk scores with stronger resilience profiles and lower overall risk scores.
Ensign Group now trades only slightly above where it sat before the class action headlines hit, which leaves a simple fork in the road. Do you step in at today’s price or wait for a deeper reset as legal risks evolve?
Most Popular Narrative: 21.9% Undervalued
On the widely followed fair value view, Ensign Group’s last close of $171.80 sits below an implied value of $220. This puts the legal overhang up against a growth and quality narrative that many investors still track closely.
A sizeable pipeline of low occupancy, clinically challenged acquisitions, particularly in Texas, creates room for operational turnaround using the existing cluster and ONE CLINICAL model, which can affect occupancy driven revenue and EBIT over multi year periods.
See why 1 investors see Ensign Group as 22% undervalued.
Result: Fair Value of $220 (UNDERVALUED)
Still, the Ensign Group story only holds together if Medicare and Medicaid funding remains supportive and recent acquisitions in weaker facilities do not drag on earnings for longer than expected.
Find out about the key risks to this Ensign Group narrative.
Another View On Ensign Group’s Valuation
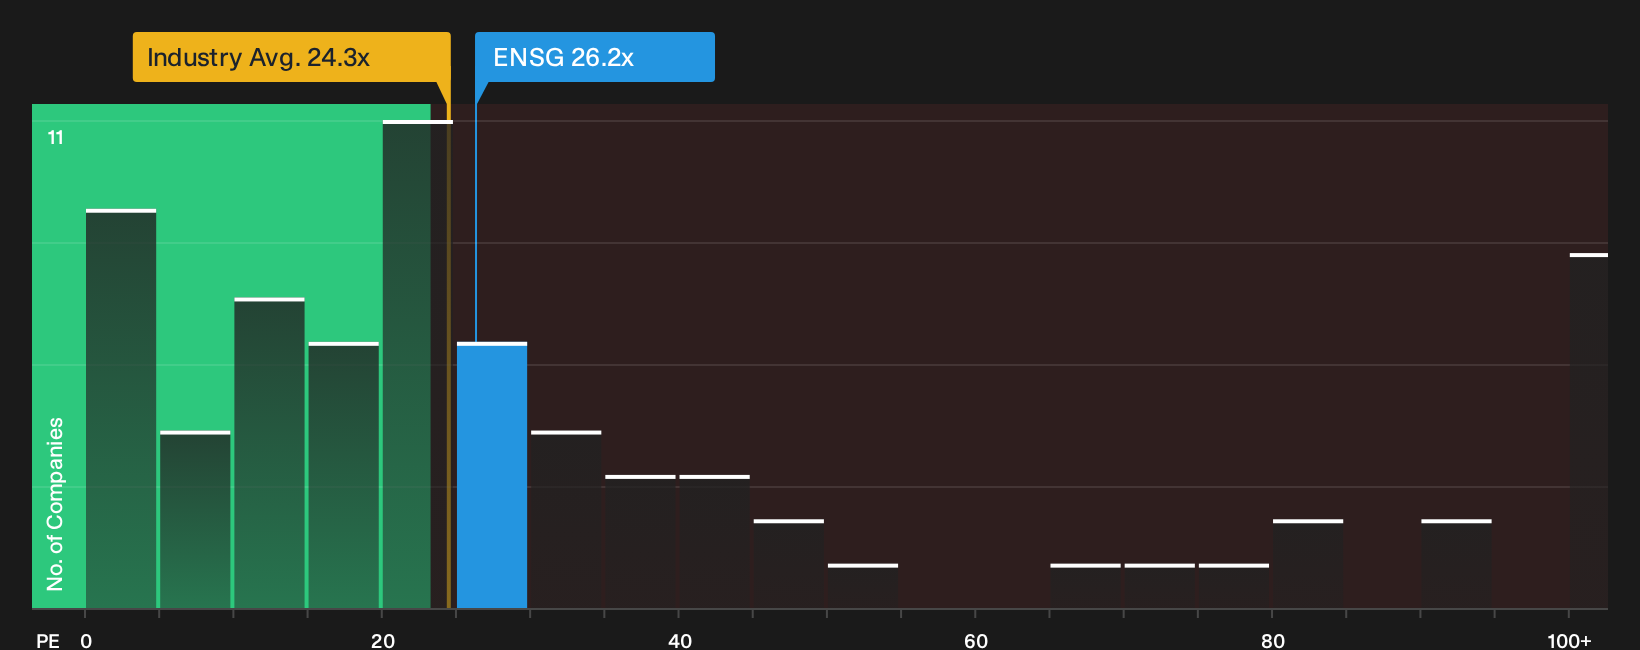
While fair value models point to Ensign Group as undervalued, the market is charging a higher tag on simple earnings maths. The stock trades on a P/E of 26.2x, compared with 15.5x for peers and 24.7x for the wider US Healthcare group, and above a fair ratio of 25.6x. This points to a richer entry point and less margin for error. Does that premium feel justified to you given the class action noise now in play?
For investors weighing that premium against fundamentals, the detailed earnings multiple breakdown in the See what the numbers say about this price — find out in our valuation breakdown. can help frame how much valuation risk you are really taking on.
Next Steps
Sentiment around Ensign Group is clearly split, which is exactly why your own homework matters more than ever. Take time to examine the full picture for yourself, and then weigh it against the 4 key rewards.
Looking for more investment ideas beyond Ensign Group?
Do not stop with Ensign Group. Broaden your watchlist now with focused stock ideas that match your style and risk tolerance before the next move passes you by.
- Target income potential and stress test your current holdings against a curated pool of companies offering resilient payouts through the 8 dividend fortresses.
- Hunt for mispriced quality and compare Ensign Group with a broader set of companies flagged as attractively valued using the 28 high quality undervalued stocks.
- Upgrade portfolio resilience by filtering for businesses with stronger finances through the Simply Wall St list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com