


Starbucks (SBUX) Could Be 19% Undervalued On Chipotle Takeover Talk
Reports that Starbucks (SBUX) has explored a takeover of Chipotle Mexican Grill immediately change how you have to think about the stock, because any large restaurant merger can reshape capital needs and future cash generation.
Starbucks has been in the spotlight all week, with the Chipotle talks, a fresh dividend increase and a new class-action lawsuit landing just as the share price has eased off recent highs.
The stock has slipped over the short term, with the 1-month share price return down 8.09% and the 3-month share price return down 15.46%, even though the year-to-date share price return is still 8.07% and the 1-year total shareholder return is 18.62%.
This mix of softer near term momentum and stronger 12 month total shareholder return suggests investors are reassessing risk and capital allocation after the merger headlines, rather than rewriting the longer term Starbucks story overnight.
Spot opportunities that rhyme with the Starbucks story by scanning a curated group of resilient consumer stocks in our 31 resilient stocks with low risk scores.The question now is whether Starbucks stock is adjusting to fresh information about the underlying business, or whether sentiment has simply swung too far and pulled the valuation away from fundamentals.
Most Popular Narrative: 19% Undervalued
In the most followed view of Starbucks, a fair value of $112.23 sits above the latest $90.75 close. This puts the recent pullback in a very different light for anyone focused on long term cash generation rather than short term headline risk.
The Back to Starbucks plan, including Green Apron Service, standardized store scorecards, and a $2b cost-savings program through fiscal 2028, is still in progress and is expected to continue affecting operating margins and earnings as more of the targeted savings and process changes flow through the P&L.
See why 228 investors see Starbucks as 19% undervalued.
Result: Fair Value of $112.23 (UNDERVALUED)
Still, unionisation efforts and higher compensation, along with ongoing legal and regulatory disputes, could pressure Starbucks margins and undercut the earnings-led thesis investors are leaning on.
Find out about the key risks to this Starbucks narrative.
Another Look At Starbucks Valuation
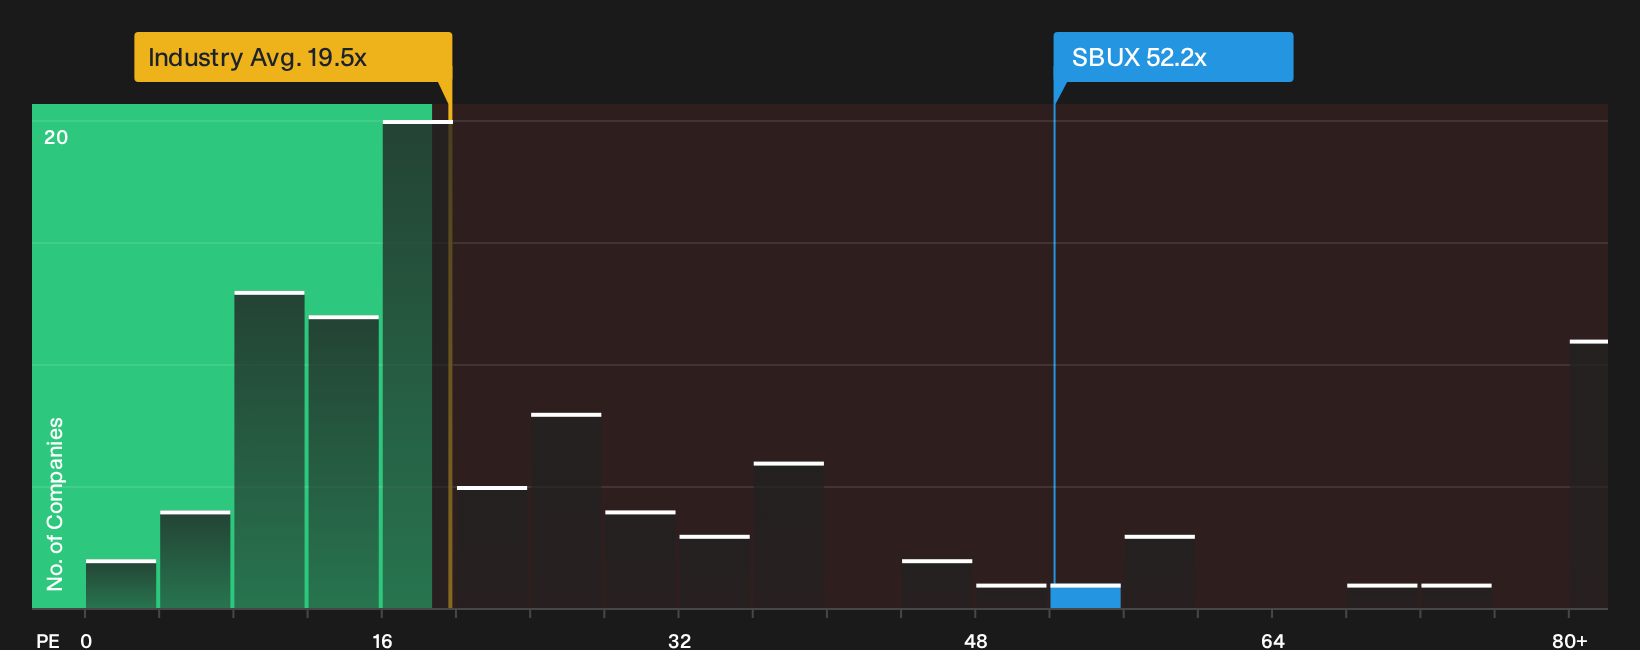
The fair value of $112.23 rests on cash flow and margins, yet Starbucks currently trades on a P/E of 52.2x. The wider US Hospitality group sits closer to 19.5x, while the fair ratio for Starbucks is estimated at 32.4x. That gap points to richer pricing and higher valuation risk. Which signal do you trust more: the cash flow story or what the market is willing to pay per dollar of earnings today?
See what the numbers say about this price in the fuller valuation breakdown, including how that P/E premium compares across peers and over time, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of risks and rewards around Starbucks feels finely balanced, you may want to move quickly to stress test the numbers and form your own stance using our breakdown of 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Starbucks?
Starbucks may be the starting point, but your portfolio deserves a wider bench of quality opportunities that match different goals, time horizons, and risk levels.
- Target durable quality by scanning a list of solid balance sheet and fundamentals (25 results) that can help you focus on financially resilient businesses before the crowd pays attention.
- Hunt for value by reviewing a curated 28 high quality undervalued stocks that filters for companies where fundamentals and price are pulling in different directions.
- Build a cash flow backbone by assessing income ideas in our 8 dividend fortresses so potential yield does not slip past you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com