


Clean Harbors (CLH) Raises $600 Million For Acquisitions, Is The Stock Still Undervalued?
Clean Harbors (CLH) just raised $600 million through new 6.250% senior notes due 2034, tying the debt raise directly to its recent EnviroServe and ES&H environmental services acquisitions.
Clean Harbors’ share price has gained 30.19% year to date to US$316.93, with a 90 day share price return of 4.21% pointing to slower near term momentum, even as the 1 year total shareholder return of 35.47% and 5 year total shareholder return of 193.67% reflect a much stronger long haul story that this latest round of acquisition funded debt now feeds into.
Capitalize on Clean Harbors’ deal-driven momentum by scanning a curated 20 high quality undiscovered gems that could be quietly building similar acquisition-fueled stories in the background.Clean Harbors now trades near US$317, while analyst targets cluster closer to US$360 and intrinsic value estimates sit lower again. Which reference point best reflects what you are actually paying for today?
Most Popular Narrative: 9% Undervalued
According to prajeeshprathap, the prevailing narrative pegs Clean Harbors at a fair value of $350, which sits above the last close at $316.93 and frames today’s price as a discount to a hard to replicate environmental infrastructure network.
Clean Harbors is essentially one of North America's most important environmental infrastructure companies.
The company has built a network of specialized facilities, including hazardous-waste incinerators, landfills, treatment and disposal facilities, recycling operations and service locations. Replicating that network would require enormous capital, regulatory approvals, technical expertise and many years of development.
See why 2 investors see Clean Harbors as 9% undervalued.
Result: Fair Value of $350 (UNDERVALUED)
Still, the Clean Harbors narrative can be hit if acquisition integration disappoints or if tighter environmental rules raise operating costs faster than customers will accept higher pricing.
Find out about the key risks to this Clean Harbors narrative.
Another View: Clean Harbors Through The P/E Lens
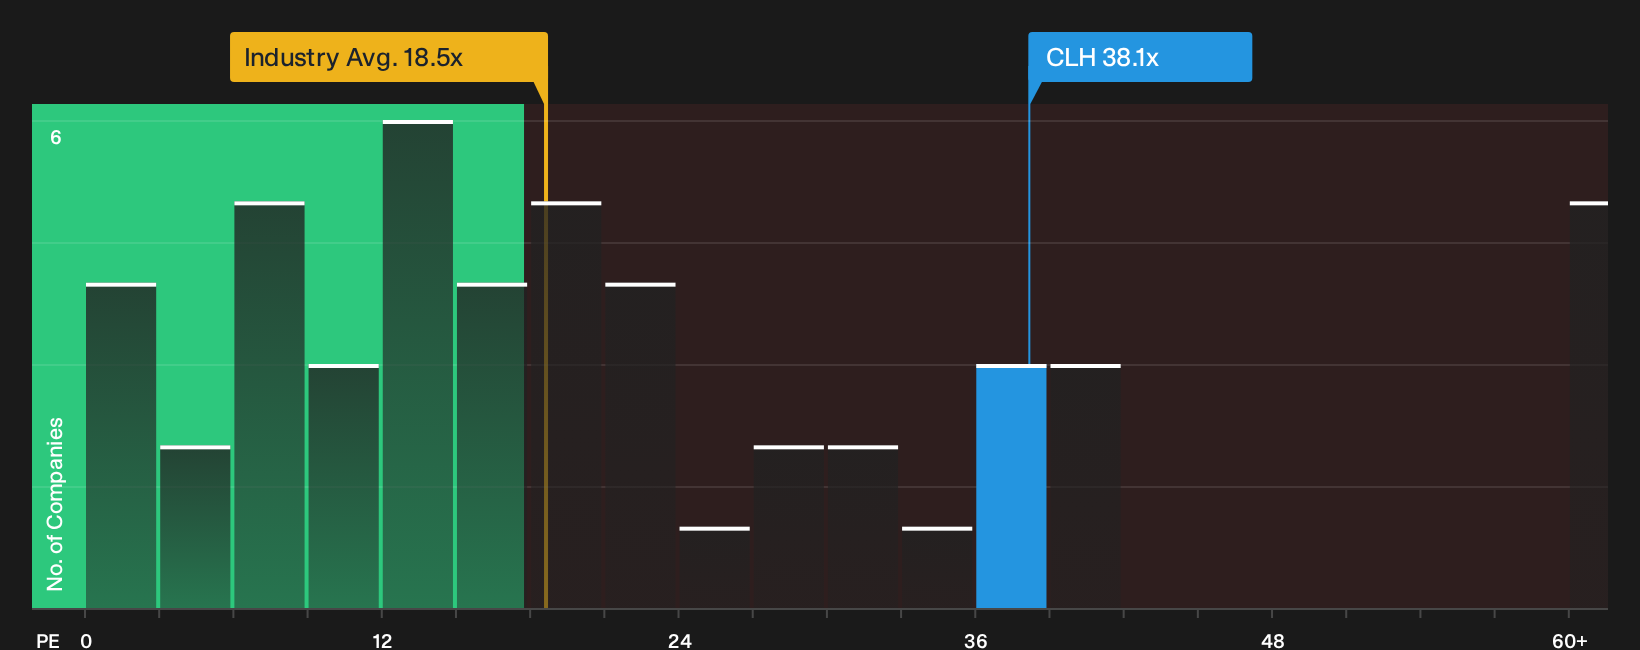
Clean Harbors may look appealing against a $350 fair value narrative, yet the P/E at 38.1x tells a different story. That figure is more than double the US Commercial Services industry at 18.5x and well above both the 27.2x peer average and a 20.7x fair ratio.
In practical terms, you are paying a premium for each dollar of earnings that goes far beyond sector norms, which leaves less room for error if growth cools or sentiment fades. Does that premium signal a quality business priced for durability, or simply stretch the risk side of the equation a little too far for your taste
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Clean Harbors so far. Take a closer look at the underlying data, weigh the concerns against the upside, and ground your own judgment with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Clean Harbors?
If Clean Harbors has you thinking harder about pricing and potential, do not stop there. Broadening your watchlist now could shift your whole return profile.
- Spot overlooked quality and give yourself more room for upside by scanning a curated 28 high quality undervalued stocks that filters for both strength and attractive pricing.
- Build resilience into your portfolio and sleep easier by checking a targeted 31 resilient stocks with low risk scores focused on companies with steadier risk profiles.
- Strengthen your income stream and avoid shaky payouts by reviewing a focused 8 dividend fortresses built around higher yielding, more durable distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com