


HealthEquity (HQY) Reshuffles Leadership And Adds A Director, Is It Still 22% Undervalued?
HealthEquity (HQY) has reshuffled parts of its leadership team, ending the employment of Chief Commercial Officer Michael Fiore without cause and reallocating his duties, while also adding experienced finance executive Noémie Heuland to its board.
At around US$92.61 per share, HealthEquity has seen its 7 day share price return of 2.85% contrast with a slightly weaker 90 day share price return, while a 5 year total shareholder return of 46.65% points to momentum that has built over a longer horizon as investors weigh the recent leadership shake up and new board appointment against the broader business trajectory.
Spot similar leadership and governance stories shaping other potential opportunities by scanning our hand-picked 31 resilient stocks with low risk scores, featuring resilient balance sheets and more measured risk profiles.Leadership change on the commercial side, a fresh finance voice on the board, and a share price near US$92 all pull in different directions for HealthEquity. Does that mix still leave the risk reward tilted toward buyers?
Most Popular Narrative: 22% Undervalued
HealthEquity's most followed valuation narrative points to a fair value of about $119 per share, compared with the recent $92.61 price. This frames the current leadership changes within a story of custodial cash, efficiency and capital returns doing much of the heavy lifting.
The recent regulatory expansion that allows direct primary care, pre-deductible telehealth and new ACA Bronze and catastrophic plan members to qualify for HSAs continues to enlarge HealthEquity’s addressable market. This can feed future HSA account and asset growth and support revenue.
See why 5 investors see HealthEquity as 22% undervalued.
Result: Fair Value of $119.33 (UNDERVALUED)
Still, the HealthEquity story can shift quickly if employment softens and employer HSA additions slow, or if fee pressure keeps service revenue growth lagging behind.
Find out about the key risks to this HealthEquity narrative.
Another View: What HealthEquity’s P/E Is Telling You
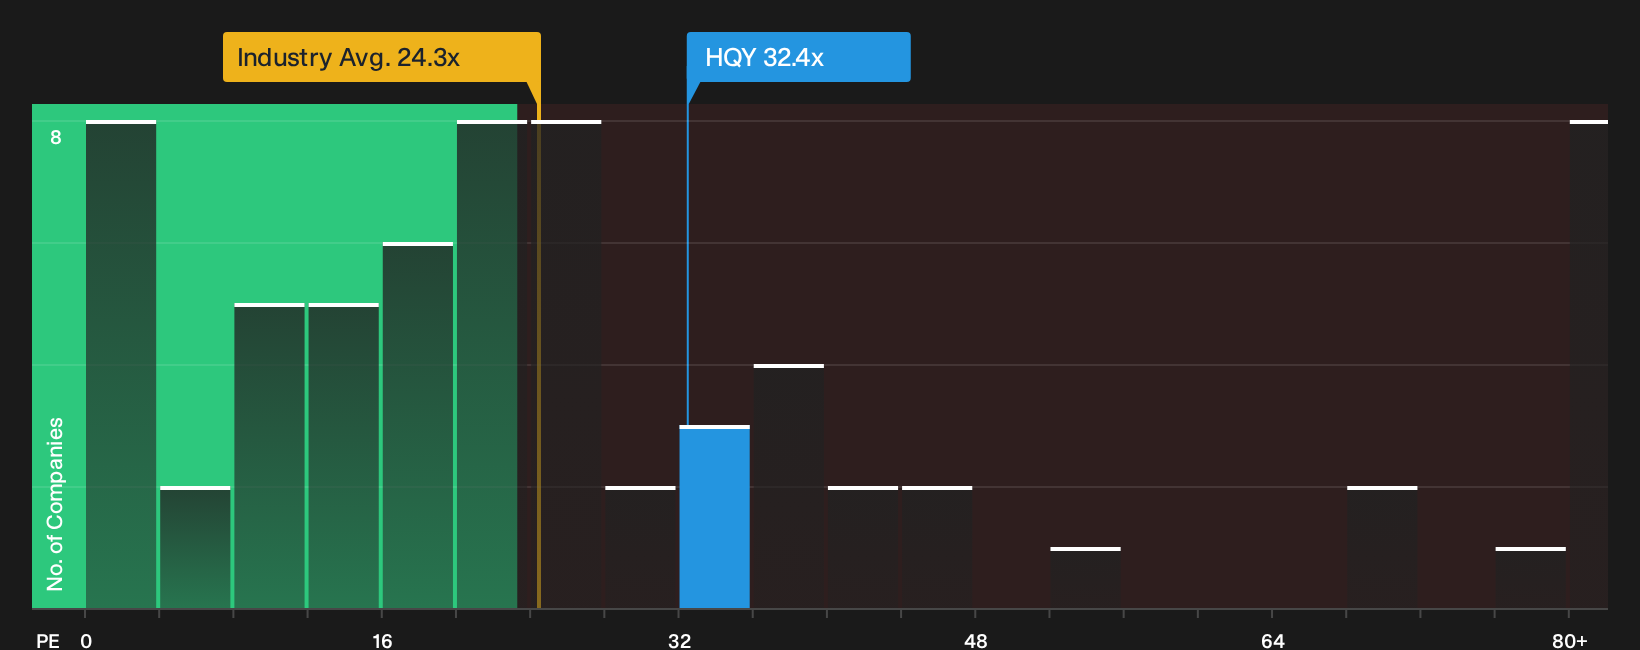
The first story on HealthEquity leans on a fair value of about $119 per share, yet the current P/E of 32.4x paints a tougher picture. That multiple sits above the Healthcare industry at 24.7x, the peer average at 31.1x, and a fair ratio of 25.8x, which hints at valuation risk if sentiment cools.
For investors who prefer to anchor decisions on earnings multiples rather than narratives, this gap raises a simple question. Is HealthEquity priced for more progress than its earnings forecasts and 16% projected return on equity can reasonably deliver, or is the premium a trade off you are comfortable paying for the current growth profile, cash generation and governance mix implied by the recent leadership moves, AI push and buybacks, knowing that multiples can compress even when profits keep rising?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages from the rest of the HealthEquity story so far. If you want to move quickly and ground your view in the positives management is targeting, take a closer look at 4 key rewards
Looking for more investment ideas beyond HealthEquity?
If HealthEquity has sharpened your focus, do not stop here. Broader context from other opportunities can help you judge risk, quality and price with more confidence.
- Target resilient value by scanning the 28 high quality undervalued stocks that combine quality fundamentals with prices that may sit below intrinsic estimates.
- Lock in potential income streams by reviewing the 8 dividend fortresses that pair higher yields with an emphasis on durability.
- Zero in on financial strength by filtering through the list of solid balance sheet and fundamentals (25 results) that keep leverage in check while supporting ongoing operations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com