


EZCORP (EZPW) Could Be 22% Undervalued After Its Strong Run This Year
EZCORP (EZPW) has drawn fresh attention after recent trading left the share price at US$31.96, with returns up 2.5% over the past day and 5.8% across the past week.
The recent gain builds on a much stronger run for EZCORP, with the share price up 59.3% year to date and a 1-year total shareholder return of 72.9%. The 3-year total shareholder return of just under 3x suggests momentum has been strong over a longer stretch, even though the 30 and 90 day share price returns have softened.
Scan beyond EZCORP's surge and explore other financially solid movers with the curated list of solid balance sheet and fundamentals (25 results).
After a run like EZCORP has logged over the past year, the temptation is to either chase the move or wait on the sidelines. Does the current price fairly reflect what you are paying for today’s earnings power?
Most Popular Narrative: 22% Undervalued
On the most followed view, EZCORP is worth $40.8 per share, comfortably above the latest close at $31.96, which frames the current debate around how much of the future is already in the price.
Continued focus on core pawn profitability, with most recent EBITDA and gross profit growth coming from pawn operations rather than scrap gold, positions future earnings and net margins to depend more on recurring loan demand and merchandise sales than on gold price movements.
Further roll out of standardized operating playbooks and data driven pricing and lending tools across the enlarged store base, including acquired platforms such as SMG, offers additional operating leverage that can support EBITDA margin expansion ahead of revenue growth.
See why 19 investors see EZCORP as 22% undervalued.
Result: Fair Value of $40.8 (UNDERVALUED)
Still, the EZCORP story can crack if scrap margins compress further or if newer Latin American stores fail to cover their higher operating and integration costs.
Find out about the key risks to this EZCORP narrative.
Another View: What EZCORP’s P/E Is Saying
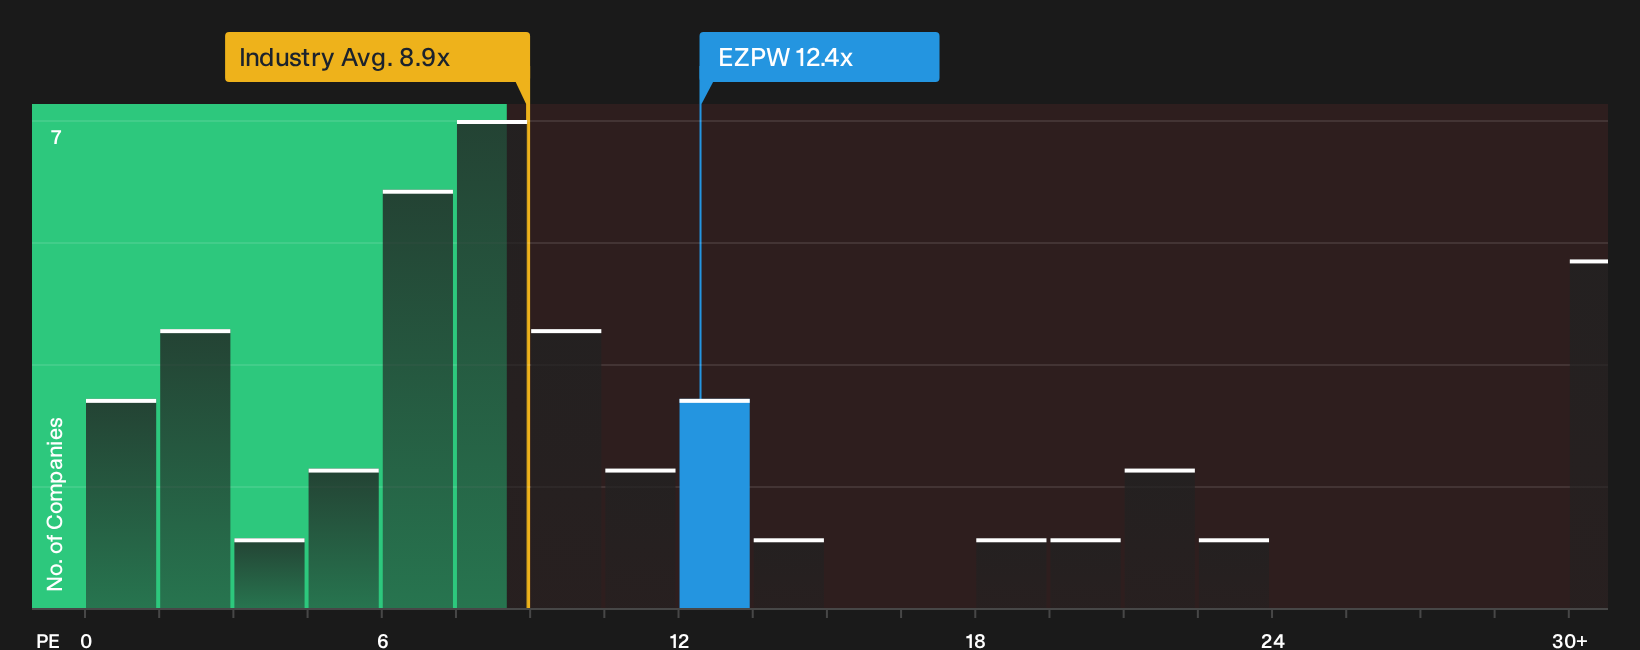
The analyst narrative frames EZCORP as 22% undervalued at $40.8 per share. The simple P/E yardstick paints a different picture. At 12.4x earnings, the shares are above the fair ratio of 11.6x and well above the US Consumer Finance industry on 9x, even though they sit below the 16.2x peer average. Is the market already paying up for the story that analysts see as still cheap?
To pressure test that gap between story and simple multiples, it helps to see what the numbers imply about valuation risk in more detail. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around EZCORP’s valuation can create both excitement and hesitation, so consider acting promptly, reviewing the full data, and weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond EZCORP?
If EZCORP has caught your attention, do not stop there. Broaden your watchlist with other clear setups that match your risk, income, and value preferences.
- Target dependable cash generators by scanning a 28 high quality undervalued stocks list built to highlight quality businesses trading below their implied worth.
- Lock in potential income streams by reviewing a curated set of 8 dividend fortresses that pair higher yields with resilient fundamentals.
- Dial down portfolio stress by focusing on companies in the 31 resilient stocks with low risk scores that show stronger balance sheets and more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com