


Is Kraft Heinz (KHC) Reasonable on Sales at This Price?
Kraft Heinz has seen its share price under pressure in recent years, so the question now is whether the current US$22.27 level is reasonable when set against the revenue the business generates. With the focus squarely on what investors are paying for each dollar of sales, the stock’s recent track record gives useful context but not yet an answer.
- Over the past 5 years the share price has declined 22.5%, which puts the spotlight on whether the present valuation still lines up with Kraft Heinz’s sales base.
- The group’s mature portfolio and emphasis on branded packaged foods can shape expectations for future revenue stability, margin resilience, and the extent to which sales can support today’s equity value.
- Your read on Kraft Heinz is one view; the desks covering it have another. See what analysts think Kraft Heinz's shares could be worth.
The issue now is whether Kraft Heinz’s current share price is adequately supported by its sales when compared with the Fair Ratio benchmark.
If you want to test the same sales based valuation question beyond Kraft Heinz, a quick way is to scan 28 high quality undervalued stocks.
Is Kraft Heinz Fairly Priced on Sales?
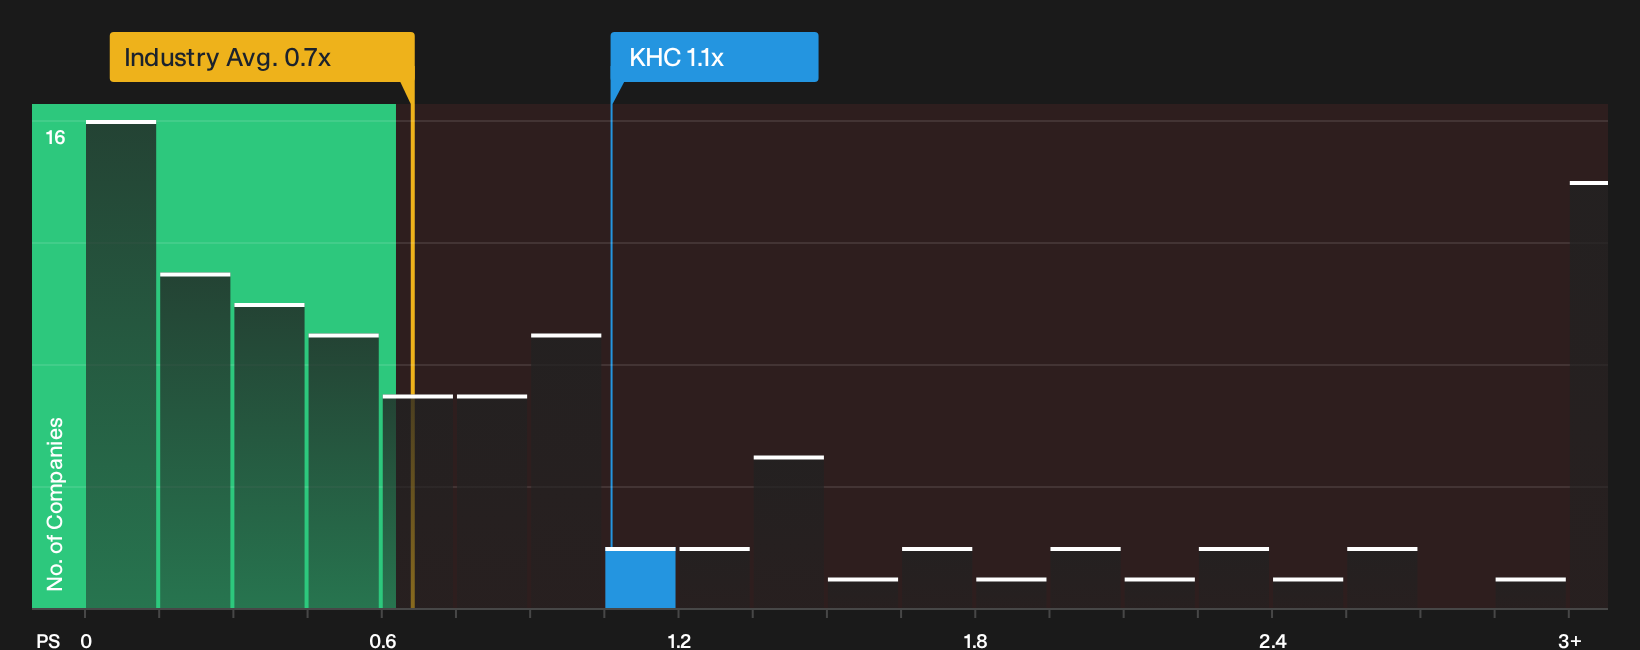
P/S is a useful yardstick for Kraft Heinz because investors often focus on what they are paying for each dollar of branded food revenue rather than on accounting earnings. On this measure, the stock trades on a P/S of 1.1x, compared with an industry average of about 0.7x and a peer group closer to 1.3x. That puts Kraft Heinz on a richer multiple than the broader Food sector but a lower tag than similar companies followed in the peer set.
The Fair Ratio, which reflects what a tailored model suggests for Kraft Heinz after weighing its margins, size, sector and risk profile, points to the current 1.1x sitting close to the level implied by those fundamentals. For you as a shareholder or potential buyer, the key takeaway is that the market is neither placing a clear premium nor a marked discount on each dollar of Kraft Heinz sales compared with what this framework would expect. Explore the numbers behind Kraft Heinz's P/S valuation.
The Kraft Heinz Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this P/S discussion leaves off for Kraft Heinz by spelling out which growth, margin and earnings paths would need to play out for the stock to look meaningfully higher or lower than today’s price, and they appear on the company’s Community page. Rather than relying on a single valuation output, each narrative lays out its own assumptions so you can compare those expectations with the actual results as they come through.
Community views on Kraft Heinz split cleanly between investors who see repairable value and those who think expectations already lean too optimistic.
Bull case: 36% undervalued
"This is not what a dying brand portfolio looks like, it is what a neglected one looks like when somebody starts feeding it again…"
Discover why this Narrative puts Kraft Heinz at 36% undervalued.
Bear case: 17% overvalued
"Although Kraft Heinz is lifting brand, marketing and R&D spend to a new base level, the risk is that higher promotion intensity simply defends share rather than reverses volume declines in processed categories…"
Explore why this Narrative puts Kraft Heinz at 17% overvalued.
The unanswered Kraft Heinz question that sits behind the numbers
Valuation only tells part of the Kraft Heinz story, because the people setting priorities, allocating capital and designing incentives can tilt long term outcomes in ways the multiples alone never reveal. See who runs Kraft Heinz and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com