


Loews (L), Why Is This Valuation Debate Getting Attention Now?
Loews share performance and recent context
Loews (L) has drawn fresh attention after a recent pullback, with the stock closing at US$106.69. Short term moves show mixed signals, while longer horizons reflect different return profiles for patient holders.
The recent share price drift, including a 7.22% decline in the 90 day share price return, contrasts with a 1.94% year to date share price gain and a 5 year total shareholder return of 88.31%. This signals fading short term momentum, while longer term holders have still seen meaningful value creation.
Scan beyond Loews and line up other insurers and financials showing similar long term compounding traits with our curated list of 28 high quality undervalued stocks.
After Loews slid over the past quarter yet still carries a long run record of solid compounding, does the current price still offer an attractive balance between downside risk and upside potential based on valuation alone?
Price-to-earnings of 12.9x for Loews: Is it justified?
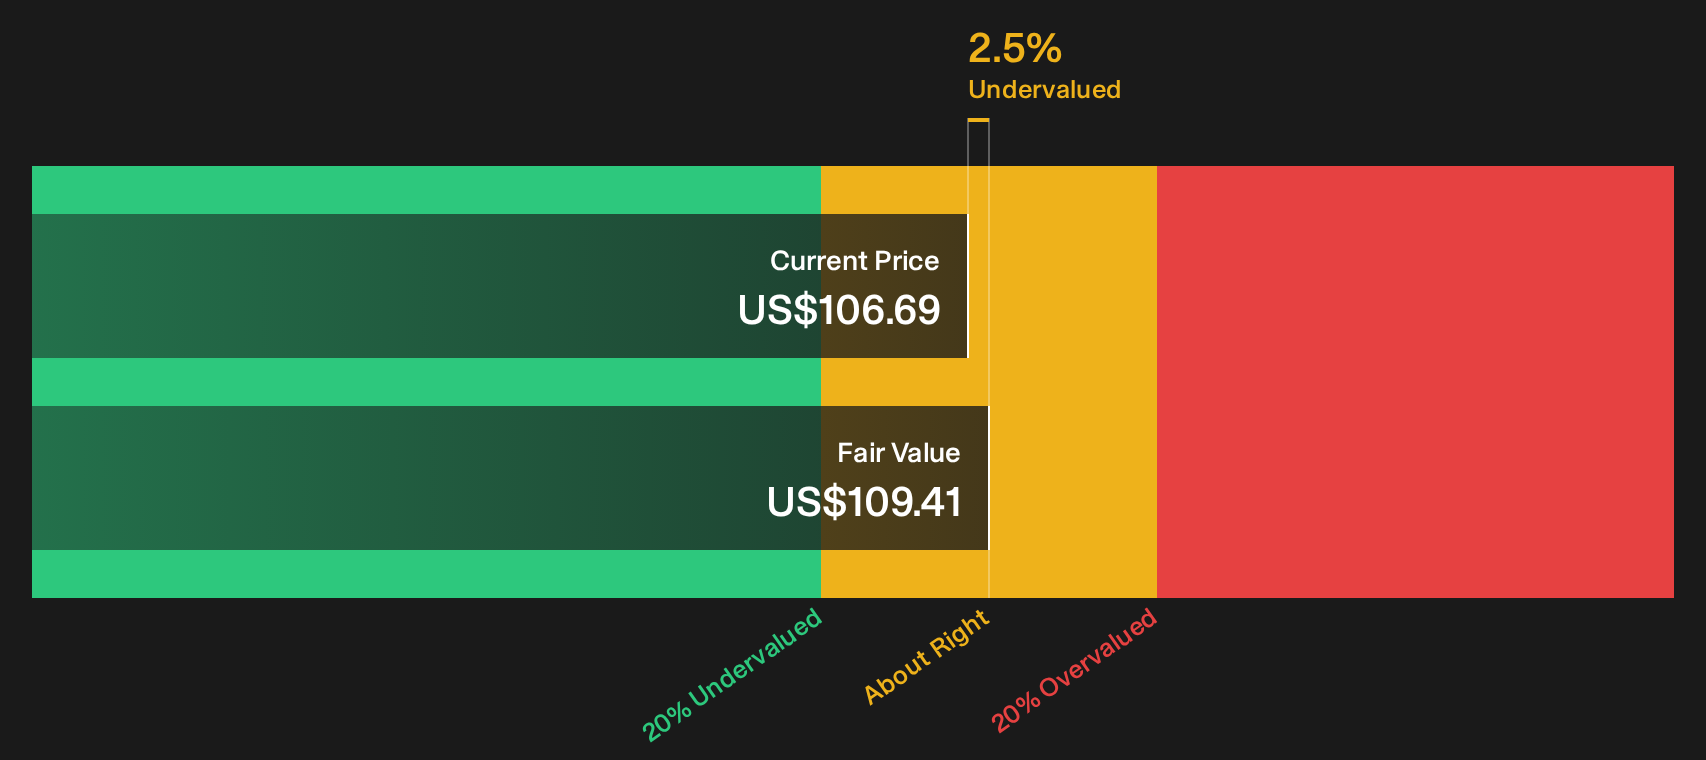
Loews trades on a P/E of 12.9x while recent SWS DCF work suggests fair value near $109.41, only slightly above the last close at $106.69. The share price sits a touch below that fair value estimate, yet the earnings multiple sits above both direct peers and the wider US insurance group.
The P/E ratio compares what investors pay for each dollar of current earnings. For an insurer-heavy group like Loews, this metric gives a simple read on how the market prices its profit base versus other financial stocks with similar risk profiles.
Based on the provided checks, Loews screens as expensive on P/E compared with its peer average of 10x and the US insurance industry average of 10.7x. That gap implies investors are willing to pay a richer price for each dollar of earnings than they pay for many competitors, even though management’s own fair value work points to only a modest 2.5% discount to intrinsic value.
The comparison against the industry is blunt. Loews trades at 12.9x earnings while peers cluster closer to 10x, so the market is assigning a clear premium multiple to this ticker instead of pricing it in line with the sector.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 12.9x (OVERVALUED)
Alongside the headline multiple, Loews also has a DCF check that points to shares trading 2.5% below the SWS DCF model estimate of future cash flow value at $109.41. That estimate comes from projecting future free cash flows from the insurance, pipelines, hotels, and plastics businesses and discounting them back to today using a required rate of return.
For a diversified insurer and industrial holding group with earnings growth of 4.2% per year over the past 5 years and net profit of $1,687.0m on revenue of $18,694.0m, anchoring on cash generation helps frame whether the current pullback simply brought the price closer to a reasonable intrinsic range.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of $109.41 (UNDERVALUED)
Still, Loews faces real swing factors if insurance claim trends worsen, or if Boardwalk Pipelines and Loews Hotels deliver weaker cash generation than current assumptions.
Find out about the key risks to this Loews narrative.
Another view on Loews valuation
The P/E premium paints Loews as expensive, yet the SWS DCF model points in a slightly different direction. With shares at $106.69 and an estimated future cash flow value of $109.41, the stock screens as about 2.5% below that model fair value. Which signal would you lean on when sizing a position?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Loews for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Loews valuation can feel messy at first glance, so move fast, pull up the full data set, and stress test the story yourself with the 2 key rewards.
Looking for more investment ideas beyond Loews?
If Loews has you thinking harder about price, quality, and risk, do not stop here. Broader opportunity often sits just outside your current watchlist.
Use the Simply Wall Street Screener to pressure test your next moves and spot ideas that match your risk tolerance and income goals.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential value opportunities that pair quality with pricing support using the 28 high quality undervalued stocks.
- Prioritise sleep-at-night resilience by focusing on companies flagged in the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com