


Planet Fitness Stock What UBS Saw In Fall Sign Ups
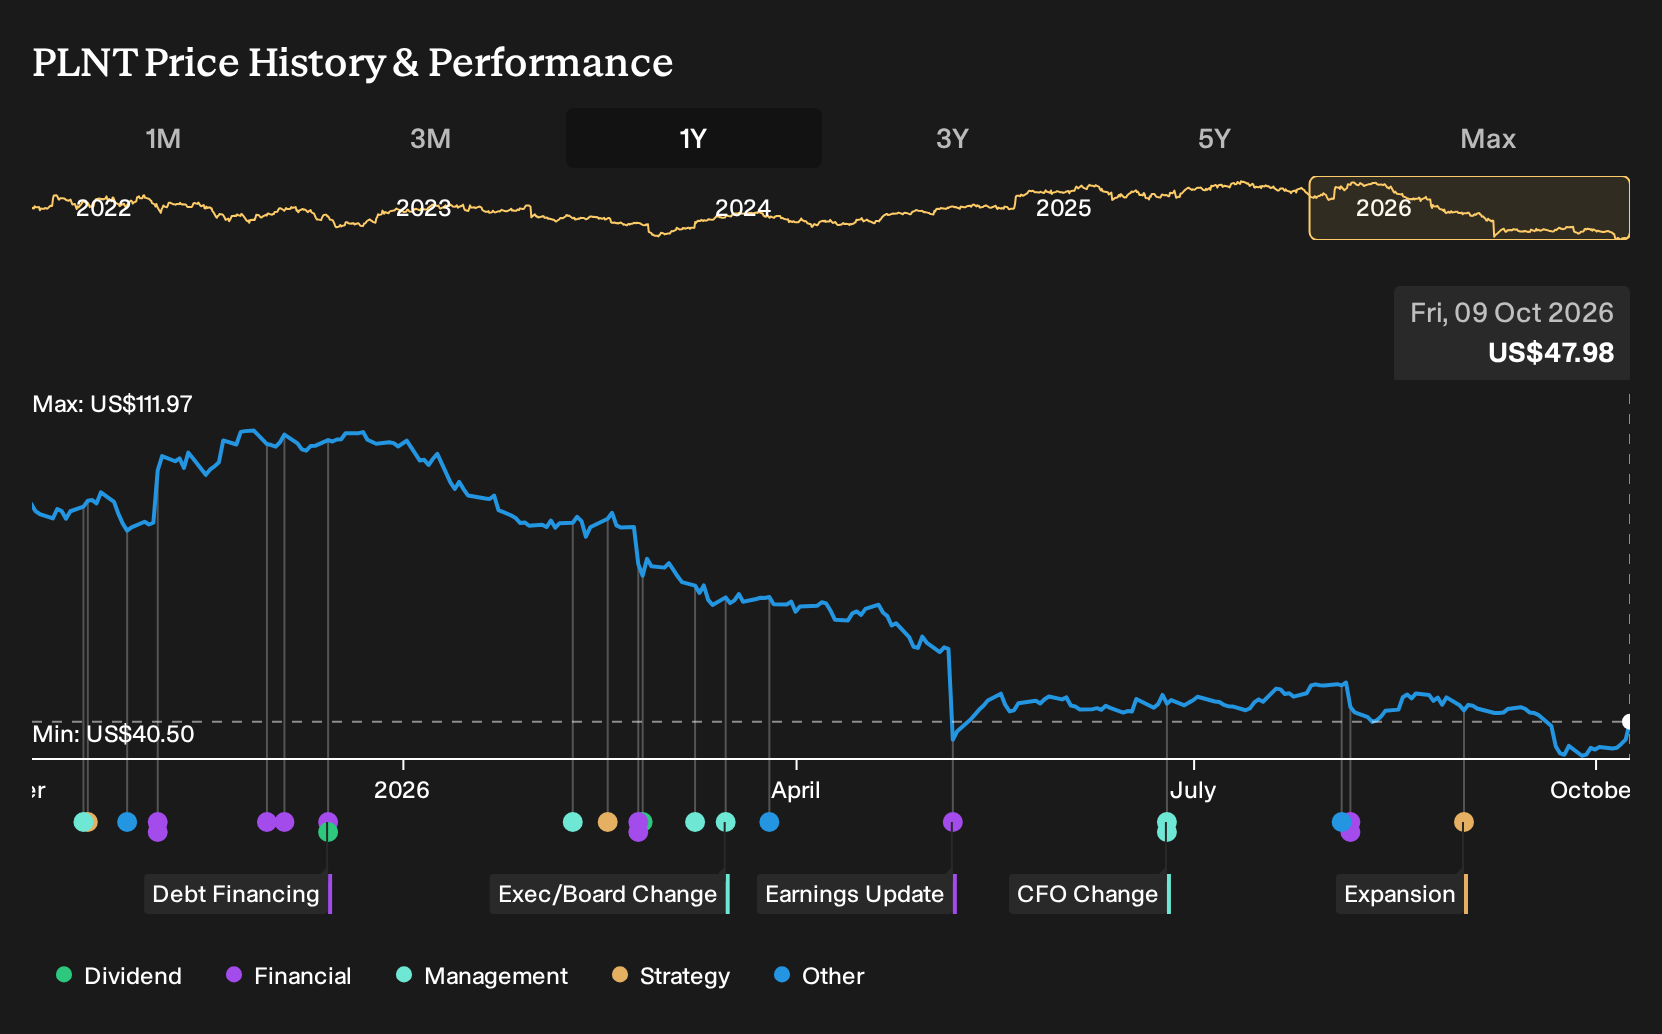
- Planet Fitness recently attracted renewed attention after UBS highlighted evidence of stronger member demand, citing firm membership trends and responsiveness to a fall pricing promotion launched at the end of August.
- The interesting angle for investors is how this apparent pickup in sign ups during the promotion period speaks directly to demand elasticity for Planet Fitness memberships and the brand's pull with value focused gym users.
- We will now look at how Planet Fitness's investment narrative could be influenced by this apparent lift in membership demand.
Scan how the Planet Fitness story compares with other value focused consumer plays by running your own check on 28 high quality undervalued stocks right now.
Planet Fitness Investment Narrative Recap
To own Planet Fitness, you need to believe the low cost, beginner focused model can keep pulling in casual gym users at scale while franchise economics remain attractive. The recent UBS flagged lift in sign ups during the fall promotion points to healthy price sensitivity and supports the near term catalyst of a rebound in net joins and same club activity.
The biggest near term risk still sits with churn and franchise returns. Online cancellation and heavy cancel anytime messaging previously tied to a 3.8% attrition quarter show how fragile retention can be. Higher ad fund contributions that pressure franchise margins could also cool appetite for new club openings if not carefully managed.
The pricing promotion that kicked off on 31 August sits at the center of this latest move in Planet Fitness. UBS called out stronger membership growth in September and early October tied to that offer. For you, the key question is whether this was a short lived discount effect or evidence that the value pitch still resonates when pricing sharpens.
If that campaign helped reaccelerate joins without training members to wait for deals, it supports the broader marketing and AI initiatives that aim to lift engagement and reduce churn. If it mostly pulled forward demand, the underlying concerns around competition from other low price chains, slower same club sales of about 1.7% and franchise margin pressure remain front of mind.
Planet Fitness' narrative projects US$1.7b revenue and US$345.5m earnings by 2029. That aligns with analyst assumptions for 10.1% yearly revenue growth and implies an earnings increase of about US$107.6m from US$237.9m today.
Uncover why Planet Fitness' fair value indicates a 38% potential upside to its current price, a discount that could close sooner than many expect.
Exploring Other Perspectives
For a different angle, focus on the bearish concern that Planet Fitness may lean too heavily on buybacks rather than stronger cash generation. The lowest analysts were only pencilling in revenue of about US$1.7b with earnings of US$287.9m by 2029, well below the more optimistic US$364.0m view. Today’s UBS driven demand surprise could push either side to reassess those paths. Treat this as a prompt to compare several narratives, not a final answer.
Explore 3 other Planet Fitness fair value estimates, including one that suggests it could be worth just $49.20.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Planet Fitness research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Planet Fitness. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Planet Fitness' overall financial health at a glance.
Looking for more Planet Fitness style investment ideas?
If the Planet Fitness story has you thinking about where else value, resilience, or income potential might show up, use the Simply Wall St Screener to widen your watchlist and pressure test your thesis across a broader set of companies.
- For investors who like mispriced quality, scan a curated set of opportunities through 28 high quality undervalued stocks that line up strong fundamentals with attractive pricing.
- If capital preservation is top of mind, focus on stability and balance sheet strength by filtering companies via a 31 resilient stocks with low risk scores that targets businesses with lower overall risk profiles.
- When you want to move beyond the usual watchlist and hunt for fresher stories, use a 20 high quality undiscovered gems to surface lesser known stocks with solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com