


Dover (DOV) Showcases Fueling Tech Following Fair Value Questions
Dover (DOV) is showcasing its convenience retail and fueling technology portfolio to industry buyers, connecting refrigeration, fueling, EV charging and car wash systems to efficiency and customer experience themes at the upcoming NACS and PEI events.
Recent trading tells a mixed story for Dover. The share price has eased over the past quarter, with the 90 day share price return down 12.31%. However, longer term momentum remains positive, with a 1 year total shareholder return of 18.16% and 3 year total shareholder return of 41.36%, hinting that investors have been rewarding the broader business performance while short term sentiment cools slightly around the latest product push.
Scan for other equipment suppliers benefiting from the same convenience retail and fueling themes shaping Dover's story by reviewing the curated 43 power grid technology and infrastructure stocks.That pullback has created a gap between Dover’s recent share price and where some valuation frameworks place it. Does that disconnect still tilt the risk reward balance toward buyers, or has most of the upside been taken already?
Most Popular Narrative: 22.5% Undervalued
Dover’s most followed narrative places fair value at $243.79 a share, well above the last close of $188.83. This points to a material gap between price and the longer term cash flow story.
Increasing capital investments in capacity and automation for data center cooling solutions and clean energy components positions Dover to benefit from large, multi year trends in data center build outs and energy transition projects, supporting future revenue acceleration and a higher margin mix.
See why 28 investors see Dover as 23% undervalued.
The thesis behind that valuation uses an 8.68% discount rate and assumes Dover leans harder into automation, clean energy and other secular areas that already account for a sizeable share of its $8.4b revenue base. Analysts in that framework also factor in earnings growth, margin expansion from 13.4% to 15.8%, and a bigger contribution from software and recurring revenue as newer platforms in coding, traceability and integrated fueling scale.
Execution risk still matters. Refrigeration plant consolidation in Conyers, Georgia has already been estimated to shave 1% to 1.5% off organic growth and delay revenue, and critics point to slower organic progress and a P/E around the low 20s as reasons to be cautious on how much investors will pay for that future cash flow. The narrative view is that if Dover converts its data center, power infrastructure and CO2 refrigeration order book into higher margins as planned, the current discount to that $243.79 fair value could narrow over time.
Result: Fair Value of $243.79 (UNDERVALUED)
Still, refrigeration plant setbacks in Conyers, along with any further delays in capacity ramps or margin progress, could quickly weaken confidence in Dover’s upbeat narrative.
Find out about the key risks to this Dover narrative.
Another View: What Multiples Say About Dover
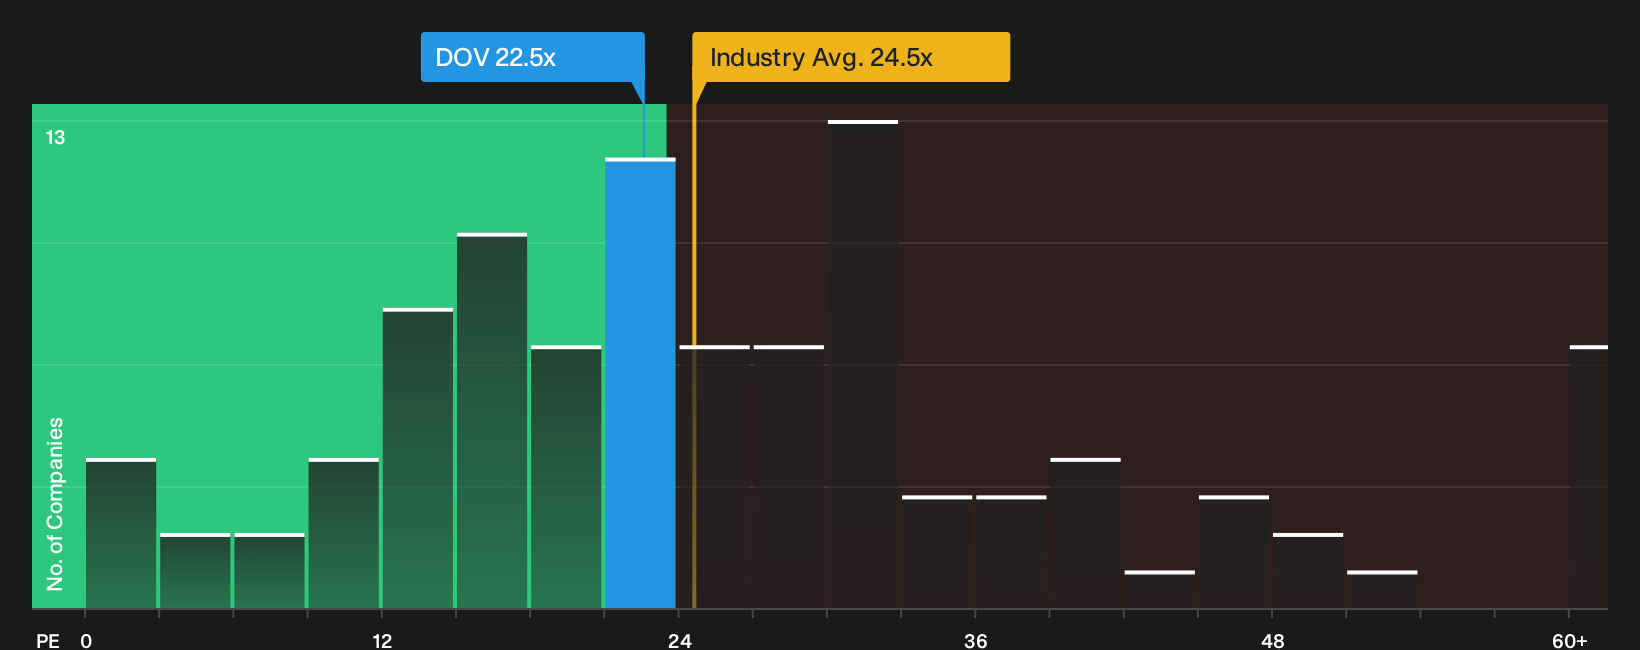
Dover screens as undervalued on future cash flows, yet the current 22.5x P/E is slightly above its 22.2x fair ratio and roughly in line with peers at 22.5x. Compared with the US Machinery average of 24x, that leaves only a narrow margin of safety. Is that slim gap enough compensation for the execution risks you see?
To pressure test that earnings based view against more detailed valuation work, take a closer look at the numbers behind it with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling that Dover’s story is tilted toward optimism, or still on the fence about the risks? Act while the data is fresh and pressure test that view against the 4 key rewards.
Looking for more investment ideas beyond Dover?
Do not stop your research with Dover. Broaden your watchlist and compare what you see here with other opportunities that fit different goals and risk levels.
- Target resilient income by reviewing companies that share the traits of fortress like payers using the 8 dividend fortresses.
- Hunt for mispriced quality and pressure test Dover’s valuation against a broader pool of opportunities sourced from the 28 high quality undervalued stocks.
- Prioritize capital preservation and stress test your downside protection by scanning the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com