


Sartorius (XTRA:SRT3) Jumped, But What Is Behind The Fresh Attention?
Sartorius (XTRA:SRT3) has jumped back into focus after a rebound in its share price linked to improved earnings and margins, while investors question a P/E of 91.5x and the company’s use of higher risk funding.
Recent trading paints a mixed picture for Sartorius. The 1 month share price return of 6.84% and 1 year total shareholder return of 18.8% point to recovering momentum, even though the 5 year total shareholder return is still down 51.18%. This keeps the current €253.0 level and 91.5x P/E under close scrutiny.
Compare Sartorius’s rich P/E and risk profile with companies that screen as high quality and potentially better priced by scanning our curated list of 174 high quality undervalued stocks today.
The rebound in Sartorius now corresponds to a P/E of 91.5x and follows a sizeable 5-year drawdown. Is most of the repricing already in the rear-view mirror, or is there meaningful upside left from here as the valuation is unpacked next?
Price-to-Earnings of 91.5x: Is it justified?
On the numbers provided, Sartorius trades on a rich P/E multiple, with the recent €253.0 close corresponding to roughly 91.5x earnings, while our fair value work indicates the shares trade at a 21.1% discount to an estimated intrinsic value of €320.67 based on the SWS DCF model.
The P/E ratio compares the share price to earnings per share and effectively shows how many years of current profit investors are willing to pay for. For a life sciences supplier like Sartorius, this metric often reflects what the market is willing to pay for its earnings profile, its role in bioprocessing, and the visibility of its profit growth.
Here, the gap is wide. Sartorius screens as expensive on a simple P/E lens when set against the Global Life Sciences industry average of 38.5x, the peer group at 48.6x, and an estimated fair P/E of 28x that the fair ratio analysis suggests the market could move toward over time.
Explore the SWS fair ratio for Sartorius.
Result: Price-to-Earnings of 91.5x (OVERVALUED)
Still, Sartorius faces clear risks if biopharmaceutical customers pull back on equipment budgets or if its higher valuation and funding costs reduce returns on new investments.
Find out about the key risks to this Sartorius narrative.
Another View on Sartorius: DCF vs High P/E
A simple P/E screen portrays Sartorius as expensive, yet the SWS DCF model suggests a different picture. At €253, the share price sits about 21.1% below an estimated future cash flow value of €320.67, which points to potential undervaluation. Which signal is more informative for the next move?
Look into how the SWS DCF model arrives at its fair value.
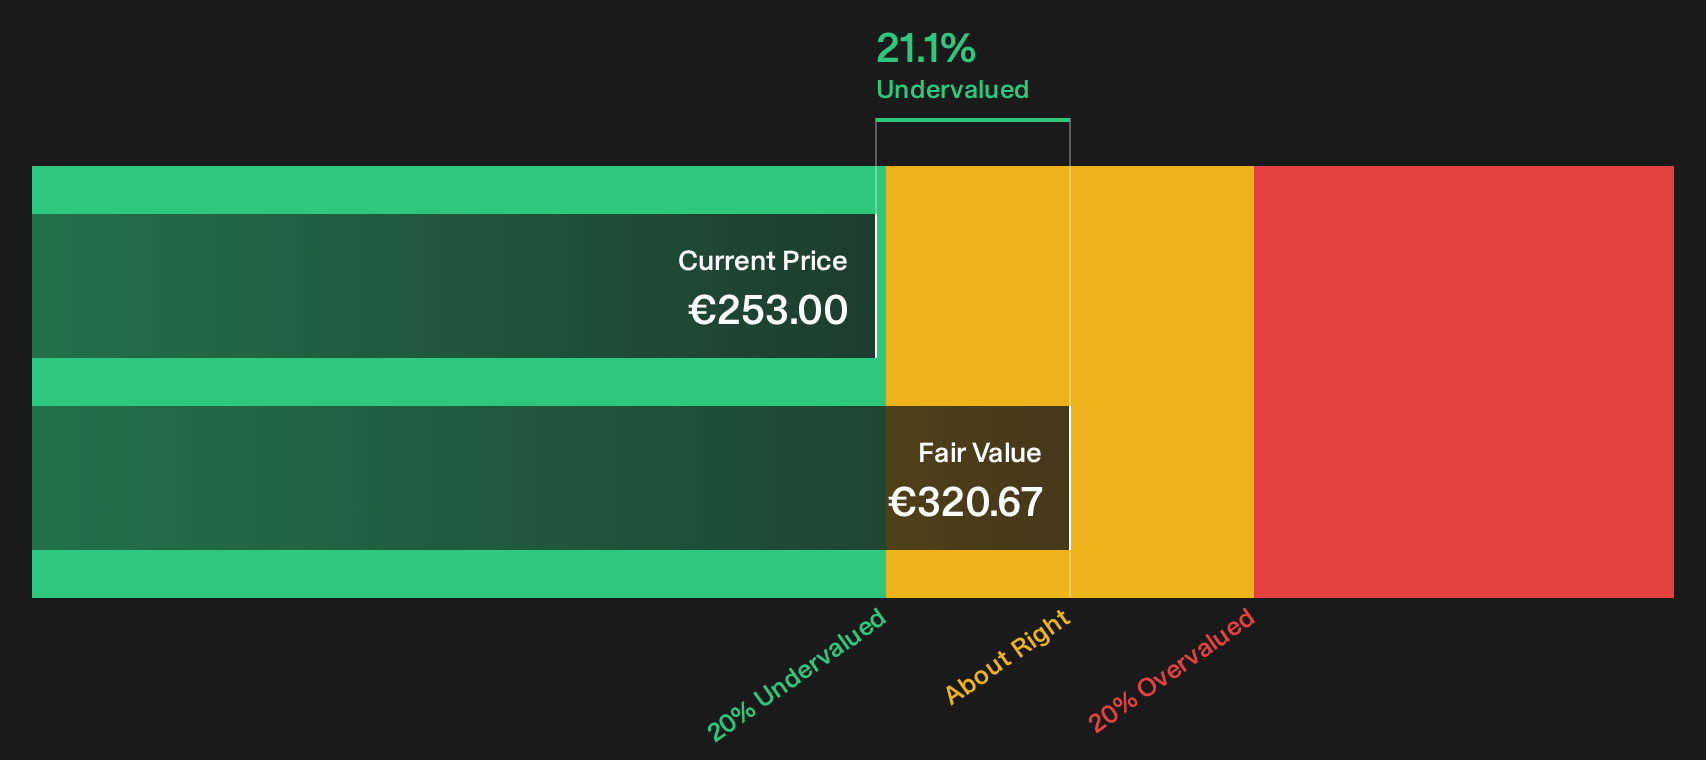
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sartorius for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Given this mix of rich valuation signals and flagged issues around Sartorius, it makes sense to look at the underlying data yourself and move fast to shape your own view. To weigh the downside against the upside in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sartorius?
If Sartorius is just one position on your watchlist, rounding out your research with a few contrasting ideas can really sharpen your next move.
- Target stronger value by checking out companies that screen as high quality and potentially better priced in the 174 high quality undervalued stocks.
- Prioritise resilience by reviewing the list of solid balance sheet and fundamentals (204 results) for businesses with sturdier finances that may better withstand tougher conditions.
- Get ahead of the crowd by scanning the 618 high quality undiscovered gems before other investors start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com