


Higher Rates Could Keep Lifting These US Financial Stocks
Interest rates are high, and the Federal Reserve is hinting they could stay that way for years, which quietly rewrites the rulebook for who wins and who struggles in US financials. That shift creates an opening for investors who are willing to look past the headlines and focus on business models tied to cash, credit and deposits. This article breaks down three stocks from our screener that appear aligned with the latest Fed signals and explains how each might respond to a higher for longer environment.
The three stocks covered below are just a sample, and the full screen surfaced 9 more large-cap US financial companies with equally compelling rate-sensitive narratives that are not included in this article. To identify and analyze the higher-for-longer ideas that best fit your own portfolio framework, head straight to the US Financials Benefiting from Higher-for-Longer Interest Rates screener.
Burke & Herbert Financial Services (BHRB)
Overview: Burke & Herbert Financial Services is a Virginia based community bank holding company offering deposits, loans, and wealth and cash management services.
Operations: The business reports about US$360 million in Community Banking revenue, entirely generated within the United States.
Market Cap: US$1.39b
Burke & Herbert Financial Services fits within the higher for longer interest rate theme, with most income tied to interest-earning community banking. Net interest income recently reached US$93.05 million for the quarter, while the stock trades on a 14.5x P/E and offers a 3.19% dividend yield. One key consideration is how much of that rate environment ultimately flows through to future margins.
How much of that actually sticks in future margins comes into clearer focus in the DCF valuation analysis for Burke & Herbert Financial Services, where the rate path and earnings power sit side by side.
Inter & Co (INTR)
Overview: Inter & Co is a Brazil based digital financial group that combines retail banking, payments, investing and insurance on a single platform.
Operations: Inter & Co generates most of its R$7.6b revenue from Banking & Spending at about R$5.5b, with all activity reported in Brazil.
Market Cap: US$3.2b
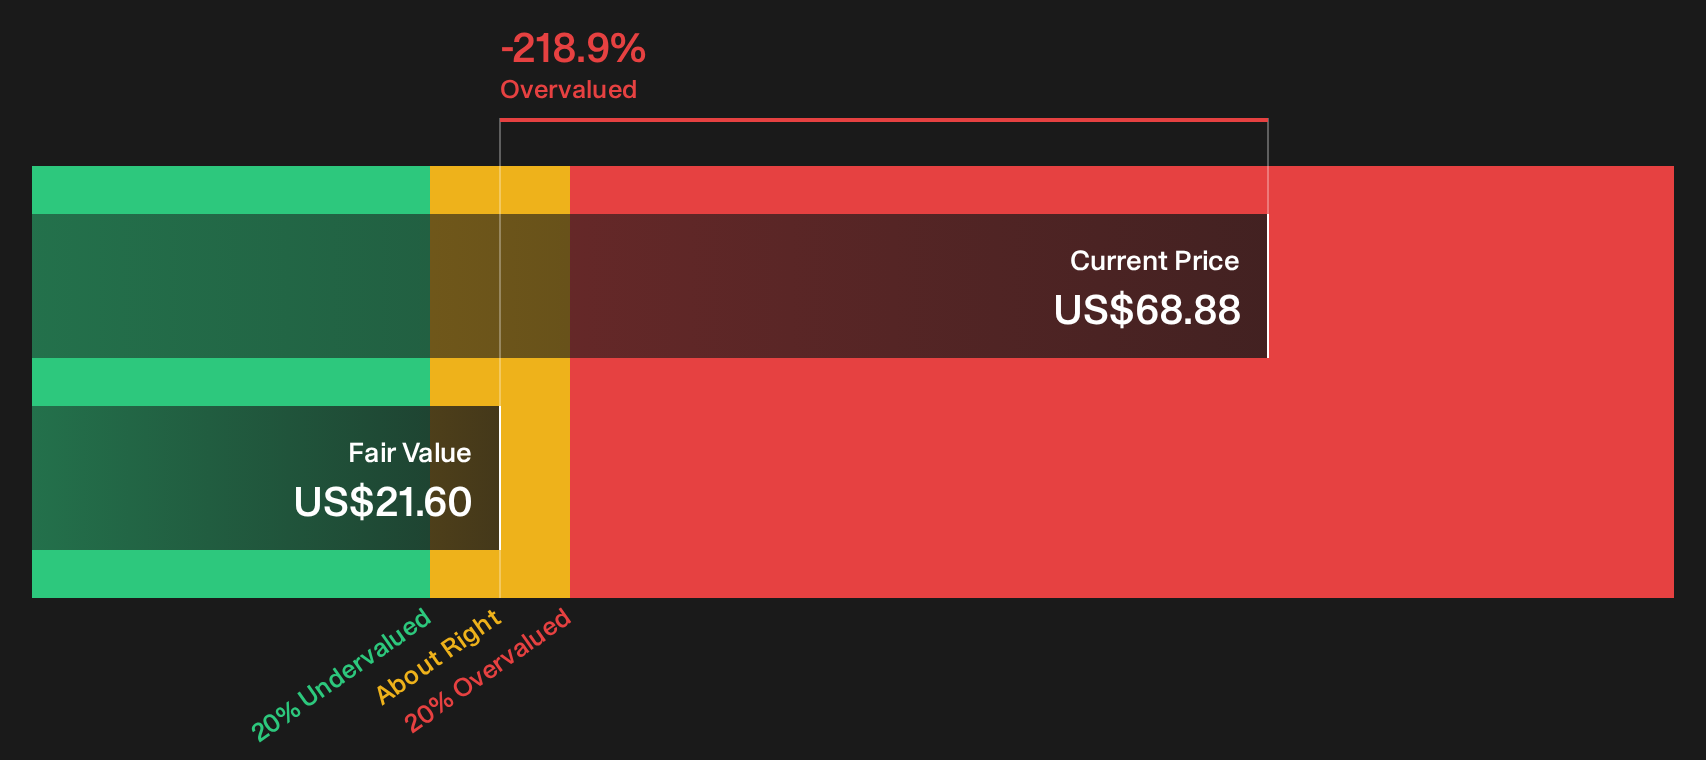
Inter & Co matters for this higher for longer rates screen because its Brazilian banking engine can benefit when loan yields and investment spreads stay elevated while it works to control funding costs and credit risk.
"High interest rates may pressure both funding and credit quality."
What really moves the needle for Inter & Co is how one unresolved pressure shapes the gap between rising asset yields and future margins.
That margin gap is exactly where the full narrative for Inter & Co digs in, laying out how Inter & Co could turn pressured funding costs into an accelerating digital banking story.

HomeTrust Bancshares (HTB)
Overview: HomeTrust Bancshares is a US community and commercial bank providing loans, deposit accounts, and cash management services to households and businesses.
Operations: HomeTrust Bancshares generates about US$210 million from banking activities, with all revenue currently earned in the United States.
Market Cap: US$768 million
HomeTrust Bancshares is directly tied to the higher for longer theme because its profits lean heavily on net interest margins and loan spreads across a US deposit base. Net interest income reached US$45.29 million in Q2 2026 with a 30.6% profit margin and fresh buybacks. This places more emphasis on how results could change if a single key assumption about credit losses were to shift.
If that credit loss assumption is wrong in either direction, the 4 key rewards and 1 important warning sign shows where HomeTrust Bancshares margins could surprise or slip before the market reacts.

Seeking Fresh Alternatives Beyond Banks?
Fresh ideas do not stay under the radar for long. Once momentum builds, the best entry points can get caught and start dropping fast. Move before the crowd and act now.
- Spot potential breakout income plays by scanning curated high-yielders in the 8 dividend fortresses while yields still reflect today’s pricing and not tomorrow’s headlines.
- Track early momentum in real-world AI adoption by reviewing the hand-picked group in the 39 profitable AI stocks that aren't just burning cash before valuations fully reflect their cash generation.
- Position for long-run infrastructure shifts by checking the targeted list in the 43 power grid technology and infrastructure stocks while these stories are still flying mostly under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com