


Is Richer Interim Dividend Altering The Investment Case For Santander (BME:SAN)?
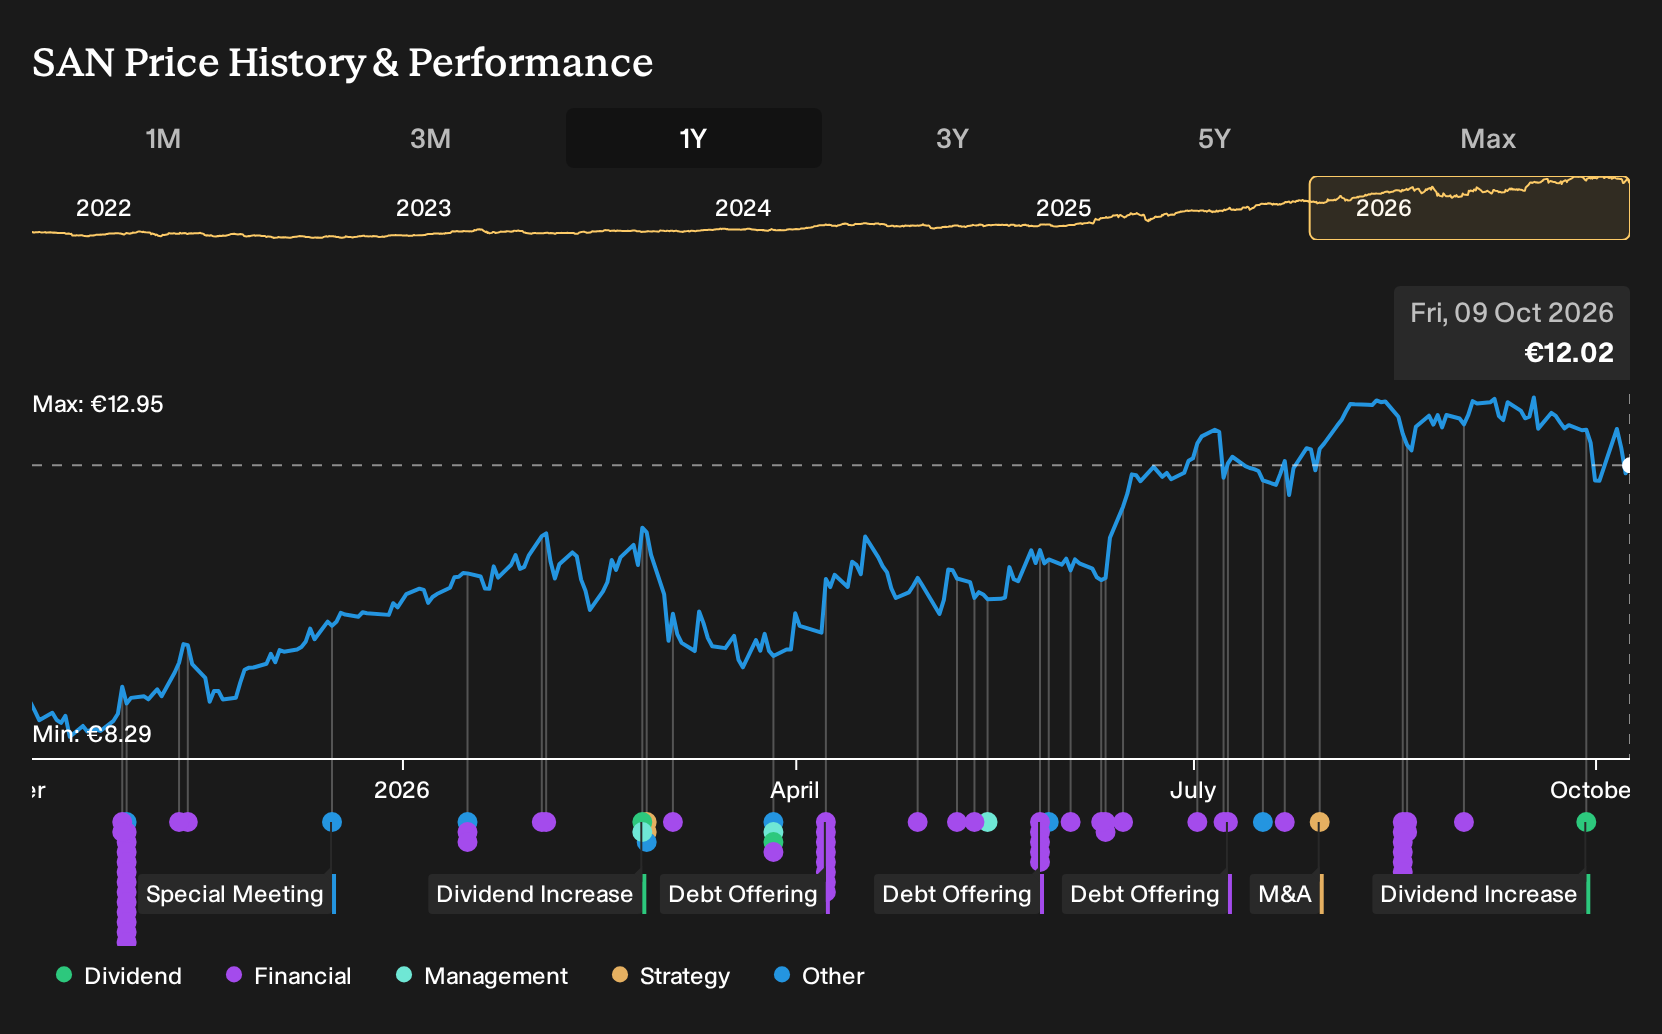
- Banco Santander's board approved an interim cash dividend of €0.127 per share against 2026 results, equal to about 25% of first half 2026 underlying profit, with the payout scheduled for 2 November 2026 and an ex dividend date of 29 October 2026.
- The richer interim payout, coming alongside reported 15% first half core profit growth and benefits from higher interest rates, reflects Banco Santander's current earnings capacity and capital deployment choices.
- The focus now turns to how Banco Santander's higher interim dividend fits within its broader investment narrative around earnings resilience.
Scan how Banco Santander’s richer interim payout compares with peers by reviewing hand picked income ideas in the 223 dividend fortresses.
Banco Santander Investment Narrative Recap
To own Banco Santander, you need to be comfortable with a global retail and commercial bank that leans heavily on diversified earnings, a higher for longer rate backdrop, and a big technology overhaul to support returns. The richer interim dividend signals confidence in current earnings power, but the key near term swing factor remains how net interest income and fees hold up if credit costs pick up.
The biggest risk circles back to loan quality and emerging market exposure, especially where bad loans already sit around 3% and provisioning coverage is relatively low at 65%. The higher payout does not remove those credit and regulatory pressures. The investment case still hinges on execution of the ONE Transformation program and the digital banking push.
The most relevant announcement for this catalyst story is the interim cash dividend of €0.127 per share, equal to roughly 25% of first half 2026 underlying profit. For income focused holders, the size and timing of this payment matter because they translate earnings headlines into cash in the account.
For Banco Santander, that dividend also interacts directly with capital management and risk. A higher cash distribution depends on the bank continuing to generate profits while dealing with elevated bad loans, regulatory costs, and ongoing tech investment. If credit quality pressures intensify, investors are likely to focus most closely on how the bank balances funding dividends, absorbing provisions, and investing in digital growth.
Banco Santander Growth Assumptions Behind The Dividend Story
Analyst forecasts sketch out what needs to happen in the background for Banco Santander's richer interim dividend to look sustainable rather than opportunistic. The projections align rising capital returns with expectations of a larger, more profitable group several years from now.
Consensus assumptions point to revenue expanding by 14.9% a year over the next three years, helped by a mix of higher volumes and efficiency gains. Profit margins are expected to move from 26.6% today to 27.5% in three years, which would modestly lift the share of each euro of income that turns into profit.
On earnings, analysts currently expect Banco Santander to move from €12.9b of profit today to €20.3b by 2029, with earnings per share of €1.45. That shift implies an increase of about €7.4b in annual earnings, which is a sizeable step up in absolute profit that would need to be backed by both revenue growth and margin discipline.
Banco Santander's narrative projects €73.7b revenue and €20.3b earnings by 2029. This requires 14.9% yearly revenue growth and an earnings increase of about €7.4b from €12.9b today.
Uncover why Banco Santander's fair value indicates a 13% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view on Banco Santander puts credit risk front and center. Some of the lowest ranked analysts were already cautious, even while assuming revenue of about €75.8b and earnings of €20.8b by 2029. They worried that heavier exposure to unsecured and cyclical lending could bite. That is a very different tone to the current dividend headline. Remember these forecasts came before this payout decision, so treat them as moving pieces and explore how your own expectations might differ.
Explore 4 other Banco Santander fair value estimates, including one that suggests it could be worth just €11.61.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Banco Santander research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Banco Santander. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banco Santander's overall financial health at a glance.
Looking For More Investment Ideas Beyond Banco Santander?
If this Banco Santander update has sharpened your income and risk radar, broaden the search and line up a few more contenders using the Simply Wall St screener before making any portfolio moves.
- If capital preservation comes first for you, start with companies that combine steadier balance sheets with fewer red flags by reviewing the 222 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, scan through the 174 high quality undervalued stocks and see which businesses currently screen as both financially strong and priced below their estimated worth.
- If you want potential future leaders that are not yet widely followed, spend some time with the 618 high quality undiscovered gems and line up a watchlist of lesser known stocks with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com