


Battery Project Approvals Could Be A Big Moment For Engie Stock (ENXTPA:ENGI)
- Engie secured approval from PJM Interconnection for two large battery storage projects in the United States: an 860 MW facility in Crawford, Pennsylvania, and an 800 MW site in Morrow, Ohio, both currently targeted to enter service in mid 2029.
- The 1.66 GW of planned storage capacity increases Engie’s presence in U.S. power markets, where batteries can support grid reliability, reshape how the group earns from flexibility, and add another scale pillar to its global renewables and infrastructure portfolio.
- This development provides a basis to examine how Engie’s investment narrative is influenced by its 1.66 GW U.S. storage initiative within PJM’s interconnection process.
What Is Engie's Investment Narrative?
To own Engie, you need to believe this is a utility that can steadily shift from legacy gas and nuclear assets toward renewables, grids and flexibility while still funding a sizeable dividend and heavy capital spending. The PJM battery approvals fit that story as another plank in Engie's Renewables & Flex Power segment, but they sit on a long development runway to 2029, so they are unlikely to move near term earnings or cash flow on their own.
In the short term, the bigger swing factors remain how Engie manages debt that is not well covered by operating cash flow, a dividend yield around 5.93% that is not well covered by free cash flows, and execution on its existing €70.6b revenue base. The stock trades on a P/E of 13.6x, below both the French market and integrated utilities peers. Analysts expect around 8.4% annual earnings growth and a 34.3% upside to their average target, but your conviction still has to rest on Engie delivering cleaner growth without stretching the balance sheet further.
That said, there is one pressure point in the Engie story that only really jumps out once you focus on...
There's only one way to know the right time to buy, sell or hold Engie. Head to Simply Wall St's company report for the latest analysis of Engie's Fair Value.
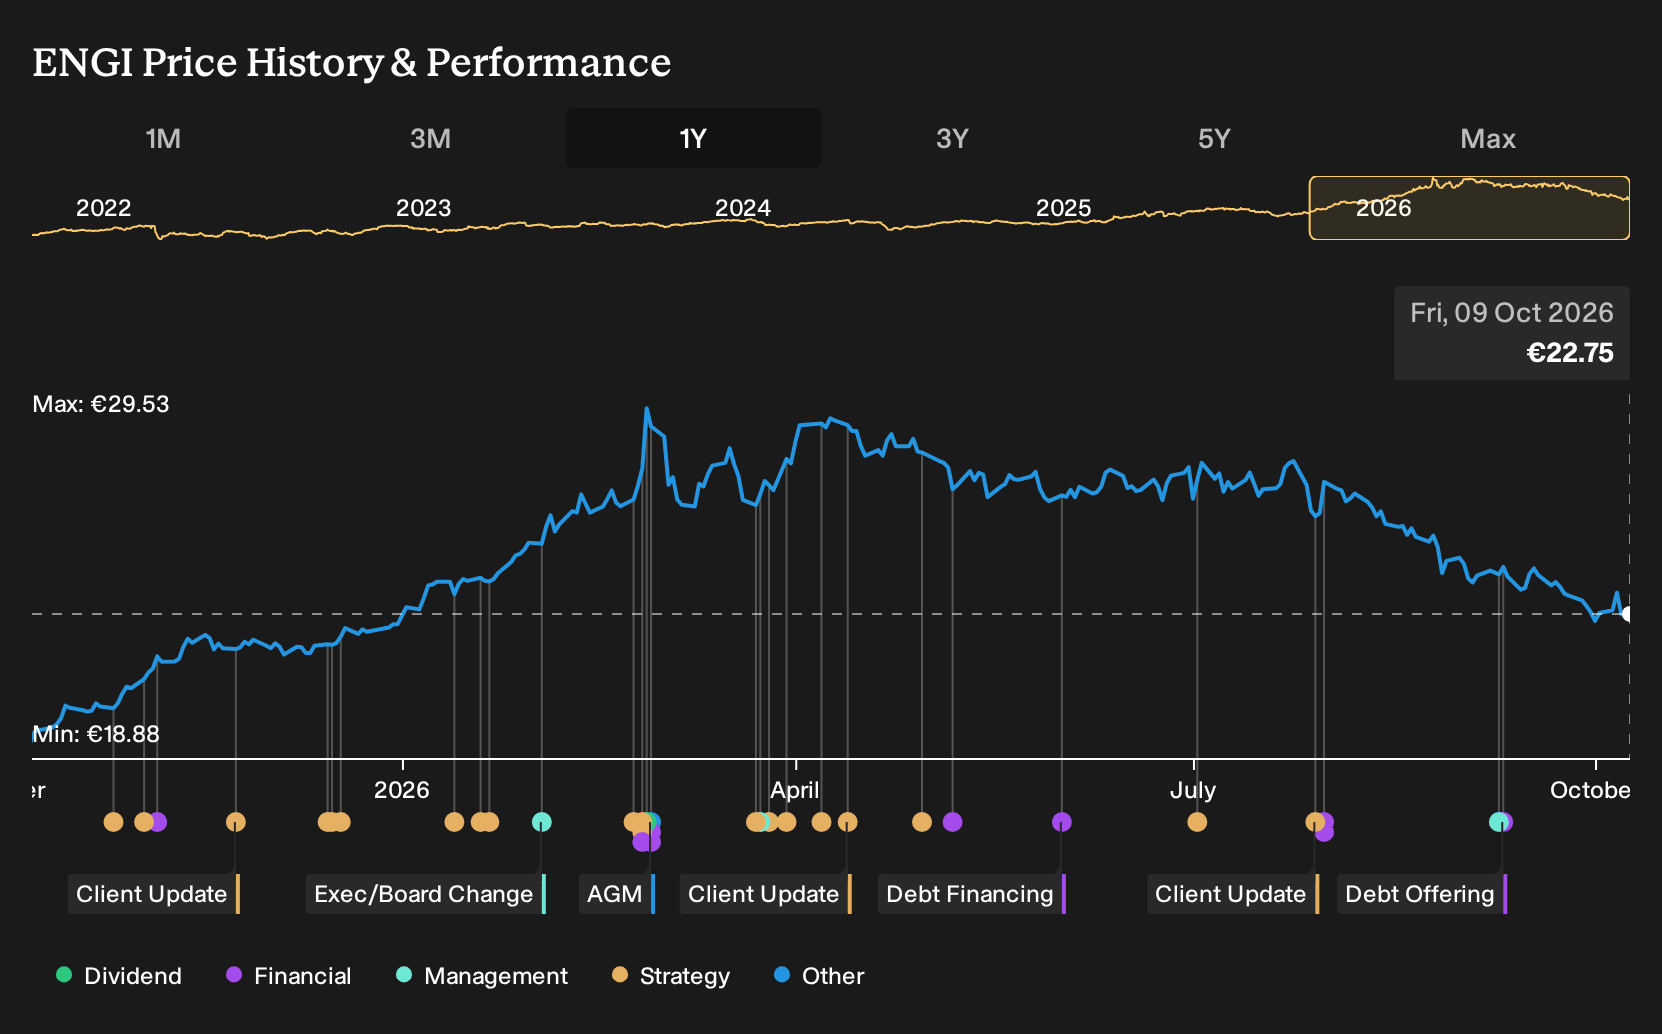
Exploring Other Perspectives
You have an upbeat alternative on Engie that leans hard on those bullish forecasts. The highest analysts were pencilling in revenue of about €100.2b and earnings near €5.8b by around 2029, well ahead of consensus. If you think the PJM battery projects reinforce that optimism, it is worth exploring how those views might shift after this news.
Explore 3 other Engie fair value estimates, including one that suggests as much as 34% potential upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Engie research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Engie. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Engie's overall financial health at a glance.
Looking For More Ideas Beyond Engie?
If you want to stress test your view on Engie against other opportunities, the Simply Wall St Screener helps you quickly scan for shares that match your own income, value, or risk preferences.
- If capital preservation ranks high for you, start with a set of 222 resilient stocks with low risk scores that score well on resilience and downside protection.
- Income focused investors can compare Engie's payout with a curated group of 223 dividend fortresses that combine higher yields with robust cash support.
- For investors hunting for overlooked opportunities, there is also a hand picked pool of 618 high quality undiscovered gems that pair quality fundamentals with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com