


Does Earnings Outlook Upgrade Change The Bull Case For H&R Block Stock?
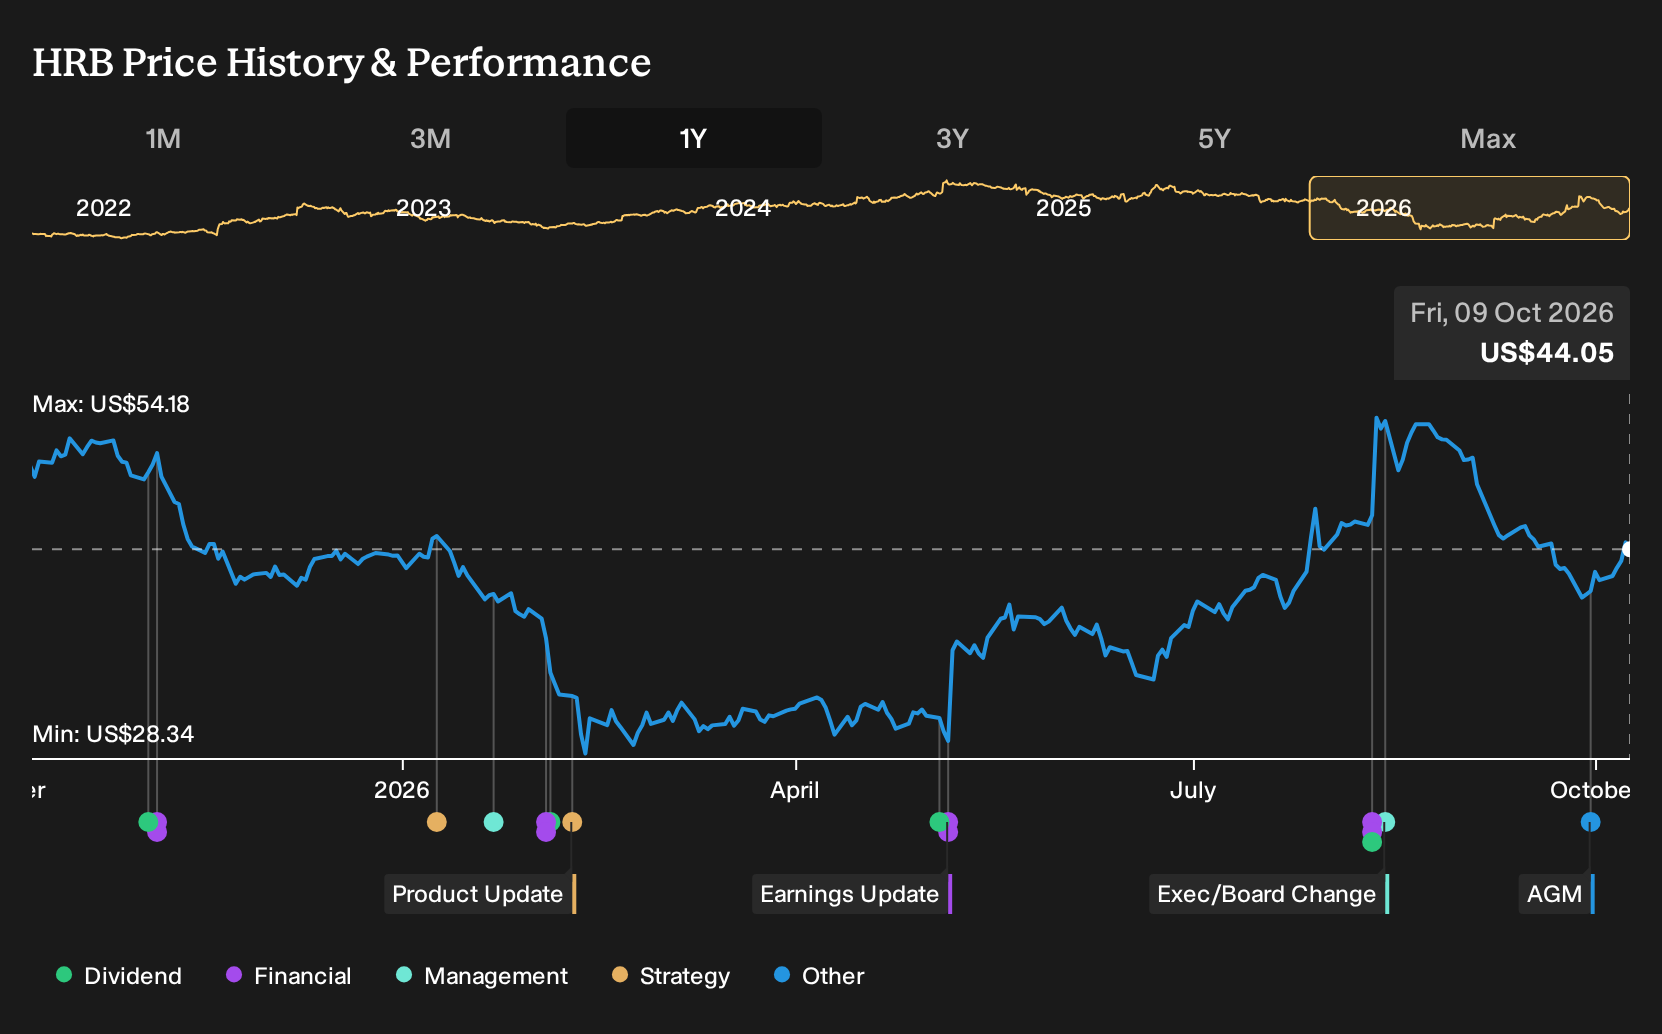
- H&R Block has recently been highlighted for an improved earnings outlook, with the Zacks Consensus Estimate for full year earnings moving 8.1% higher over the past quarter and the ticker now carrying a Zacks Rank of #2.
- The firm has also outperformed the broader Consumer Discretionary group so far this calendar year. This brings fresh attention to how its tax preparation model and related financial services are connecting with clients despite wider sector pressures.
- We will look at how H&R Block's upgraded earnings outlook reshapes the investment narrative that was built before this update.
Scan how H&R Block's earnings momentum compares with other potential opportunities by reviewing our curated list of 28 high quality undervalued stocks.
H&R Block Investment Narrative Recap
To own H&R Block, you need to believe its expert plus AI tax model can keep attracting higher value filers and small businesses while offsetting structural worries around DIY tools and slower industry growth. The recent earnings outlook upgrade points to progress on mix and efficiency, but the bigger question for you is whether that can counter long term share pressure.
The most important near term swing factor remains how the next tax season shapes volume and pricing in both assisted and digital. The main risk is that market share losses and high leverage persist together. If that happens, it could compress flexibility just as AI tax products from rivals get more capable.
The clearest announcement tied to this story is the upgraded full year earnings outlook, reflected in an 8.1% move higher in the Zacks Consensus Estimate and a Zacks Rank of #2. That shift matters most when set against H&R Block’s recent earnings growth of 20.8% and higher net margin of 18.6% compared with 16.1% a year earlier.
For you, the question is whether that improved earnings view lines up with the underlying engines. AI Tax Assist usage in the 2026 season, growth in Wave’s small business revenue and ongoing cost tools such as Sidekick are all practical levers. Execution on those, against the overhang of debt and slower expected revenue growth than the broader US market, will likely drive how durable this earnings momentum feels.
H&R Block’s current analyst setup points to revenue of US$4.5b and earnings of US$751.3m by 2029, based on expected yearly top line growth of 4.6%. That outcome would mean earnings need to rise by about US$18.7m from US$732.6m today to reach the consensus forecast.
Uncover why H&R Block's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative angle on H&R Block focuses on margin risk rather than the upgraded outlook. The most bearish analysts were penciling in revenue of about US$4.6b and earnings of roughly US$741.9m by 2029 before this news, paired with a lower 6.9x P/E. That sets a clearly more cautious story that could shift as new information lands.
Explore 3 other H&R Block fair value estimates, including one that suggests as much as 18% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your H&R Block research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for H&R Block. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate H&R Block's overall financial health at a glance.
Looking for more H&R Block style investment ideas?
If this review of H&R Block has sharpened what you want from a stock, you can use the Simply Wall St screener to hunt for other businesses that better match your checklist on value, income or resilience.
- If you want potential mispricing with quality behind it, scan our curated set of 28 high quality undervalued stocks that share a mix of strong fundamentals and attractive valuations.
- If cash returns matter most to you, narrow the field to income ideas by reviewing our 8 dividend fortresses that focus on higher yielding payers.
- If balance sheet strength is your anchor, start with the list of solid balance sheet and fundamentals (25 results) so you can filter for businesses with sturdier finances than the average stock.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com