


Equinix (EQIX) Could Be 37% Undervalued As AI Growth Meets Earnings Hopes
Equinix (EQIX) is back in focus as investors weigh fresh commentary on AI driven data center demand and interconnection growth, along with expectations for higher EPS and revenue in the upcoming October 28 earnings release.
Over the past year, Equinix has seen strong momentum, with a year-to-date share price return of 34.28% and a 1-year total shareholder return of 30.90%. The recent 90-day share price return declined 2.39% as investors digest rapid gains and fresh commentary on AI driven expansion, interconnection growth, the capacity pipeline, and the upcoming earnings release on October 28.
Compare Equinix's AI driven data center story with other potential breakout infrastructure plays using our hand picked 92 AI infrastructure stocks.
After a 34.28% year to date run and a recent 2.39% pullback, Equinix now trades at a 37.32% intrinsic discount and a 20.28% gap to analyst targets. Is that caution about AI driven demand sensible or stretched?
Most Popular Narrative: 17% Undervalued
Equinix’s most followed valuation narrative pegs fair value at $1,233, above the last close of $1,026.06. This puts the current discount in the spotlight as AI driven demand and interconnection usage stay front of mind for investors.
Equinix plans to invest US$5b to US$7b per year in development from 2027 to 2029, targeting low to mid 20% cash on cash returns with 2 to 3 year stabilizations. If achieved, this could support higher revenue and AFFO growth than currently reflected in the stock. Control of roughly 3 GW of designed power, with about 600 MW under some form of development and an expected 1 GW under production by early next year, positions Equinix to convert power constrained market demand into incremental rental revenue and cash flow over time.
See why 94 investors see Equinix as 17% undervalued.
Result: Fair Value of $1,233 (UNDERVALUED)
Still, the bullish Equinix narrative can crack if grid constraints, community pushback, or rising build costs slow that US$5b to US$7b annual development plan.
Find out about the key risks to this Equinix narrative.
Another View: Equinix Through The P/E Lens
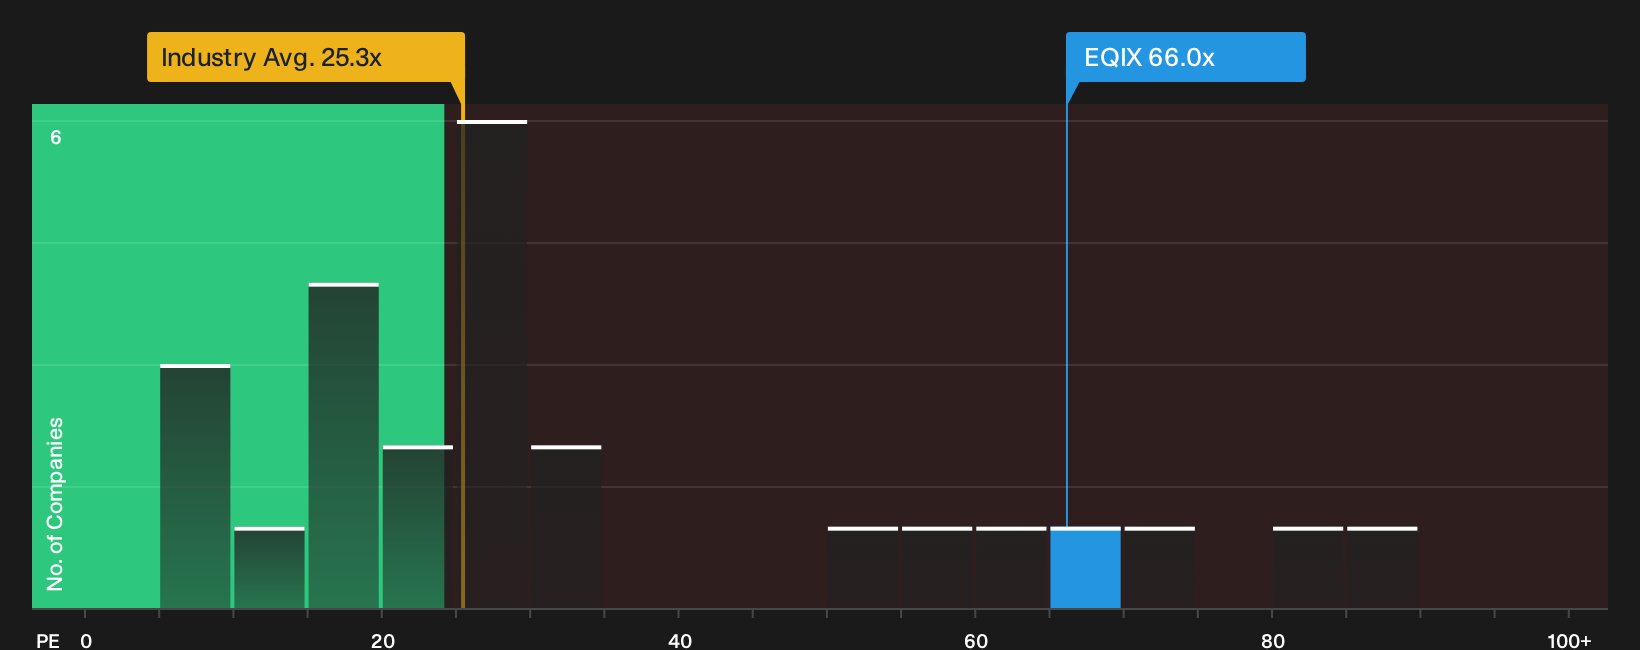
The DCF story points to upside, yet Equinix screens as expensive on earnings. The stock trades on a P/E of 66x, compared with 42.8x for peers, 25.3x for the broader Specialized REITs group, and a fair ratio estimate of 37.6x. That gap signals real valuation risk if growth or sentiment cools.
Before leaning too heavily on any one framework, it helps to see what the numbers imply side by side, then decide which picture of Equinix you trust most over the next few years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions are mixed on whether Equinix’s current discount adequately compensates for the risks and rewards outlined here. Act while the data is fresh and weigh both sides using the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Equinix?
If Equinix has you thinking differently about opportunity and risk, do not stop there. Fresh ideas across sectors can sharpen your whole portfolio.
- Target long term compounding potential by scanning a curated set of 28 high quality undervalued stocks that pair stronger fundamentals with prices that have yet to catch up.
- Strengthen the foundation of your portfolio by focusing on companies with durable finances using our list of solid balance sheet and fundamentals (25 results) so short term shocks hurt less.
- Hunt for tomorrow's potential standouts before the crowd pays attention by running a focused search across 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com