


Is BJ's Restaurants (BJRI) Fully Valued Despite Its Long Term Rally?
BJ's Restaurants (BJRI) drew fresh attention after its recent share price move, with the stock closing at $59.87. That shift invites a closer look at how the business is currently positioned.
The recent 1-day share price return of 0.55% for BJ's Restaurants sits against a softer near-term picture, with the 7-day share price return down 3.33% and the 90-day share price return down 3.84%. However, the year-to-date share price return of 45.70% and 1-year total shareholder return of 102.67% point to strong momentum that has built over a longer horizon.
Spot emerging momentum stories beyond BJ's Restaurants by scanning our hand picked 20 high quality undiscovered gems that have strong fundamentals but still fly under most investors' radar.BJ's Restaurants has delivered strong shareholder gains over the past year, yet the recent cool down raises a sharper question. At about $59.87 a share, does that performance still line up with what the business is worth today?
Most Popular Narrative: 20.6% Undervalued
Against a last close of $59.87, the most followed narrative for BJ's Restaurants pegs fair value at about $75.43, which implies a material valuation gap based on its cash flow and earnings assumptions.
Planned acceleration of new restaurant openings based on a refreshed prototype, following gains in average unit volume, restaurant cash flow and an approximate 240 basis point margin improvement over the past two years, sets BJ's Restaurants up to apply strengthened unit economics to unit growth, which is aimed at expanding systemwide revenue and cash generation.
See why 1 investors see BJ's Restaurants as 21% undervalued.
Result: Fair Value of $75.43 (UNDERVALUED)
Still, the bullish narrative around BJ's Restaurants can fray if cost pressures squeeze its 15.3% gross margin or if slower digital and off premise execution restrains demand.
Find out about the key risks to this BJ's Restaurants narrative.
Another View: What BJ's Restaurants P/E Is Telling You
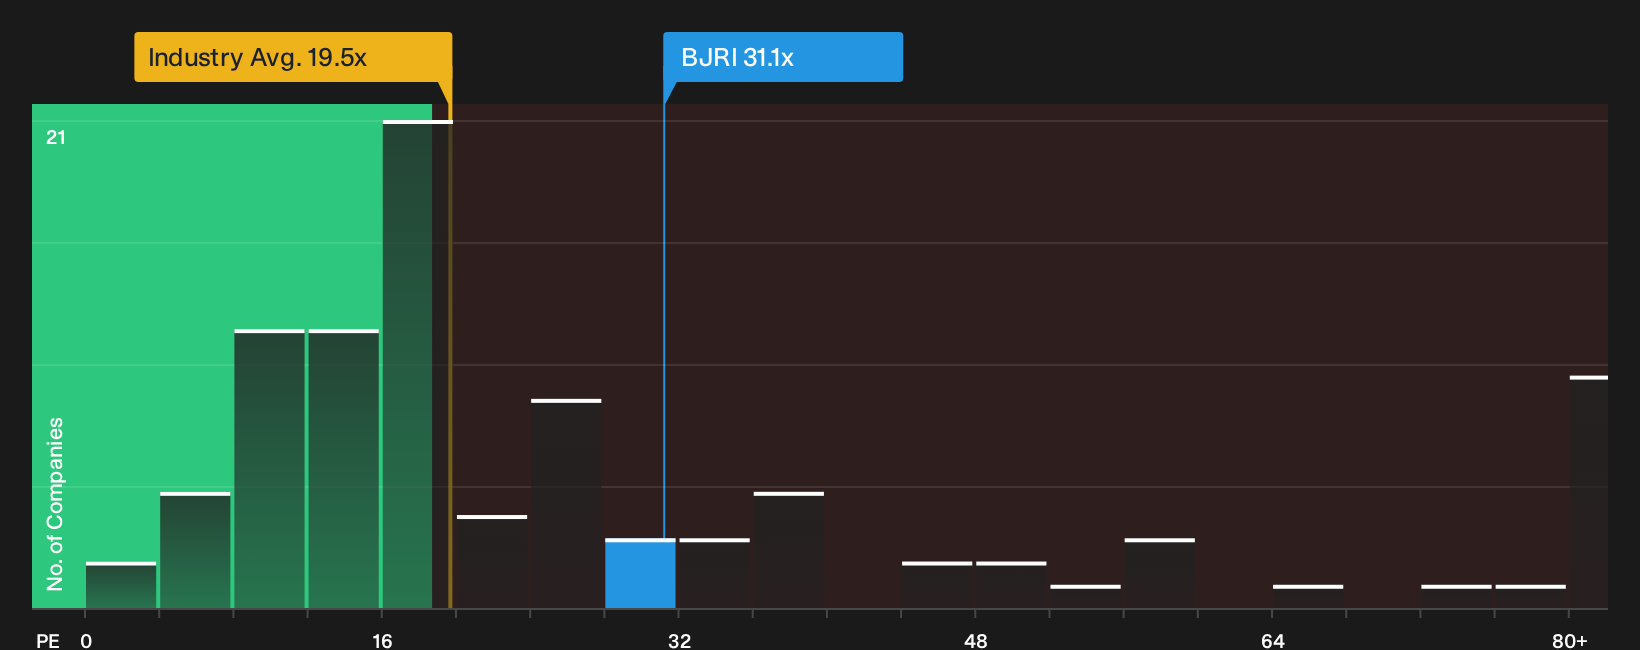
The cash flow driven fair value points to upside, yet the current P/E ratio of 31.1x paints a tougher picture. BJ's Restaurants trades richer than the US Hospitality industry at 19.5x and above its own fair ratio of 19.7x. This increases the risk that expectations are already stretched.
That kind of gap means even solid execution could leave less room for error before the valuation compresses. It raises a simple question for any holder or potential buyer: Is this a growth story you are comfortable paying a premium multiple for right now, or does it belong on a watchlist until the price or earnings profile shifts?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mixed message around BJ's Restaurants, with rich valuation multiples sitting beside underscored upside narratives, makes this a judgment call rather than a checklist decision. Act while the numbers and sentiment are fresh in mind and shape your own view by weighing the 3 key rewards and 1 important warning sign.
Looking for more BJ's Restaurants style investment ideas?
If BJ's Restaurants has sharpened your focus on where pricing and quality meet, do not stop here, better opportunities could be sitting just one screen away.
- Target steadier compounding potential by scanning a curated pool of resilient businesses in the 31 resilient stocks with low risk scores that aim to limit nasty surprises.
- Hunt for quality at a discount by running a valuation focused search across our 28 high quality undervalued stocks that combine strong balance sheets with appealing pricing.
- Build a watchlist of reliable cash distributors by reviewing companies in the 8 dividend fortresses that pair higher yields with underlying financial support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com