


Lam Research Earnings Preview: What to Expect
With a market cap. of $399 billion, Lam Research Corporation (LRCX) designs, manufactures, refurbishes, and services semiconductor processing equipment used in the fabrication of integrated circuits across the United States, Asia, and Europe. It offers a wide range of deposition, etch, cleaning, and wafer-processing systems, along with customer support services, spares, and upgrades for the semiconductor manufacturing industry.
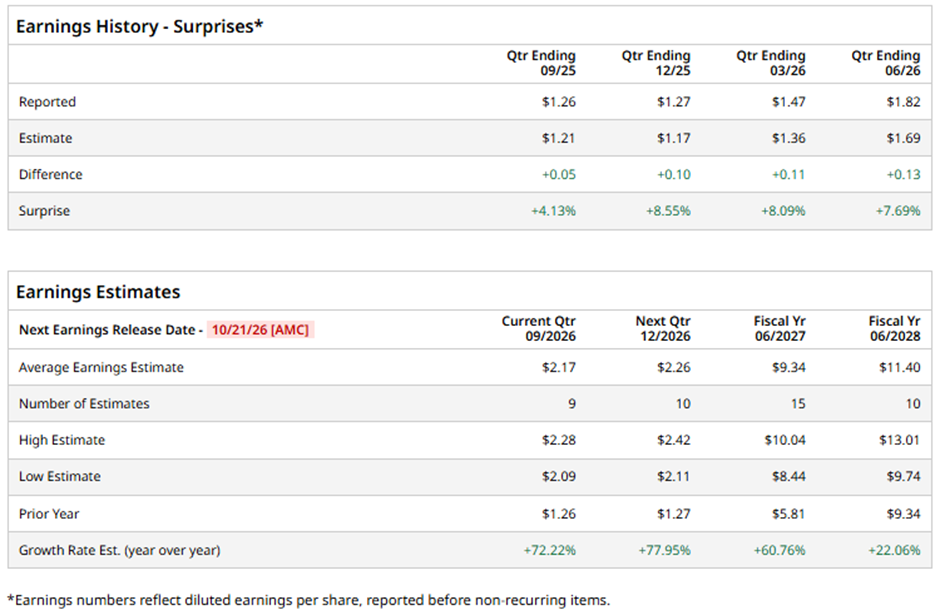
The Fremont, California-based company is slated to announce its fiscal Q1 2027 results after the market closes on Wednesday, Oct. 21. Ahead of this event, analysts expect LRCX to report an adjusted EPS of $2.17, a 72.2% surge from $1.26 in the year-ago quarter. It has exceeded Wall Street's earnings expectations in the past four quarters.
For fiscal 2027, analysts project the semiconductor equipment maker to post adjusted EPS of $9.34, a 60.8% jump from $5.81 in fiscal 2026.
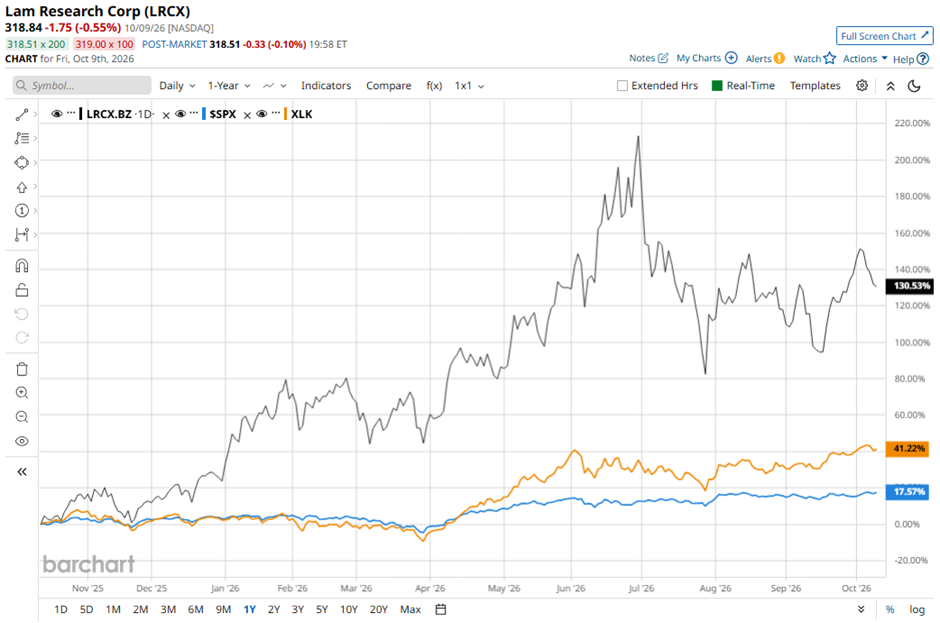
Shares of Lam Research have climbed 126.1% over the past 52 weeks, surpassing the broader S&P 500 Index's ($SPX) nearly 16% return and the State Street Technology Select Sector SPDR ETF's (XLK) 37% increase over the same period.
Lam Research shares surged nearly 18% following its Q4 2026 results on Jul. 29, driven by strong AI-related demand for semiconductor manufacturing equipment, with better-than-expected quarterly revenue of $6.72 billion and adjusted EPS of $1.82. Investor optimism increased after the company issued stronger-than-expected Q1 guidance, forecasting revenue of $8.10 billion, plus or minus $400 million and adjusted EPS of $2.15, plus or minus $0.15.
The upbeat outlook reflected rising investment in AI infrastructure and demand for advanced chips from major customers such as TSMC and Samsung, reinforcing expectations for continued growth in Lam Research’s deposition, etch, and cleaning equipment businesses.
Analysts' consensus view on LRCX stock remains bullish, with a "Strong Buy" rating overall. Out of 33 analysts covering the stock, 23 recommend a "Strong Buy," four have a "Moderate Buy," and six "Holds." This configuration is slightly more bullish than three months ago, with 22 analysts suggesting a "Strong Buy."
The average analyst price target is $375.62, suggesting a potential upside of 17.8% from current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.