


Should Climate Targets Approval Require Action From Cascades (TSX:CAS) Investors?
- Cascades recently introduced Cascades lithoURB, a 100% recycled and recyclable paperboard for high end lithographic packaging, and secured Science Based Targets initiative approval for its 2035 greenhouse gas reduction goals across Scopes 1, 2 and 3.
- The pairing of a premium recycled packaging launch with validated long term emissions cuts clarifies Cascades' pitch to brands that want low impact packaging without sacrificing print quality or operational reliability.
- This development may affect how investors view Cascades' approach to combining emissions targets backed by the Science Based Targets initiative with the launch of lithoURB.
Scan beyond Cascades to compare how other packaging and materials players are lining up their sustainability stories with earnings potential through our curated list of 9 high quality undervalued stocks.
Cascades Investment Narrative Recap
To own Cascades, you need to believe that cost cuts, mill efficiency gains and higher value recycled packaging can matter more than cyclical volume swings in boxes and tissue. The main near term swing factor is execution on the targeted CA$100 million profitability uplift by the end of 2026. The lithoURB launch and SBTi approval do not materially change that near term focus.
The biggest operational risk still sits with input costs and project delivery. Recovered fiber prices, energy and any delays or shortfalls at Bear Island or other mills could squeeze already thin margins and slow EBITDA progress. Sustainability announcements help long run positioning but do not remove these execution and cost pressures.
The SBTi backed 2035 greenhouse gas reduction targets are the news item that ties most directly into the current thesis. Cascades plans to cut Scopes 1 and 2 emissions by 67.2% and certain Scope 3 categories by 41.3% from a 2019 base. Management reports a 32.6% reduction in Scopes 1 and 2 by 2025, which suggests existing projects are already reshaping the asset base.
For you as a shareholder, the interesting link is between those decarbonization moves and the profitability initiatives already contributing roughly CA$10 million sequentially. Energy efficiency, electrification and greater use of renewable electricity can reinforce the push for lower unit operating costs. Execution risk sits in the capital required, potential downtime during upgrades and the fact that interest coverage is described as tight, which keeps financing discipline firmly in focus.
Cascades Forecasts and Valuation Check
Cascades' narrative projects CA$5.5b revenue and CA$322.8 million earnings by 2029. That profile assumes 4.8% yearly revenue growth and an earnings increase of about CA$196.8 million from CA$126.0 million today.
Uncover why Cascades' fair value indicates a 4% potential upside to its current price, before the discount to market expectations narrows.
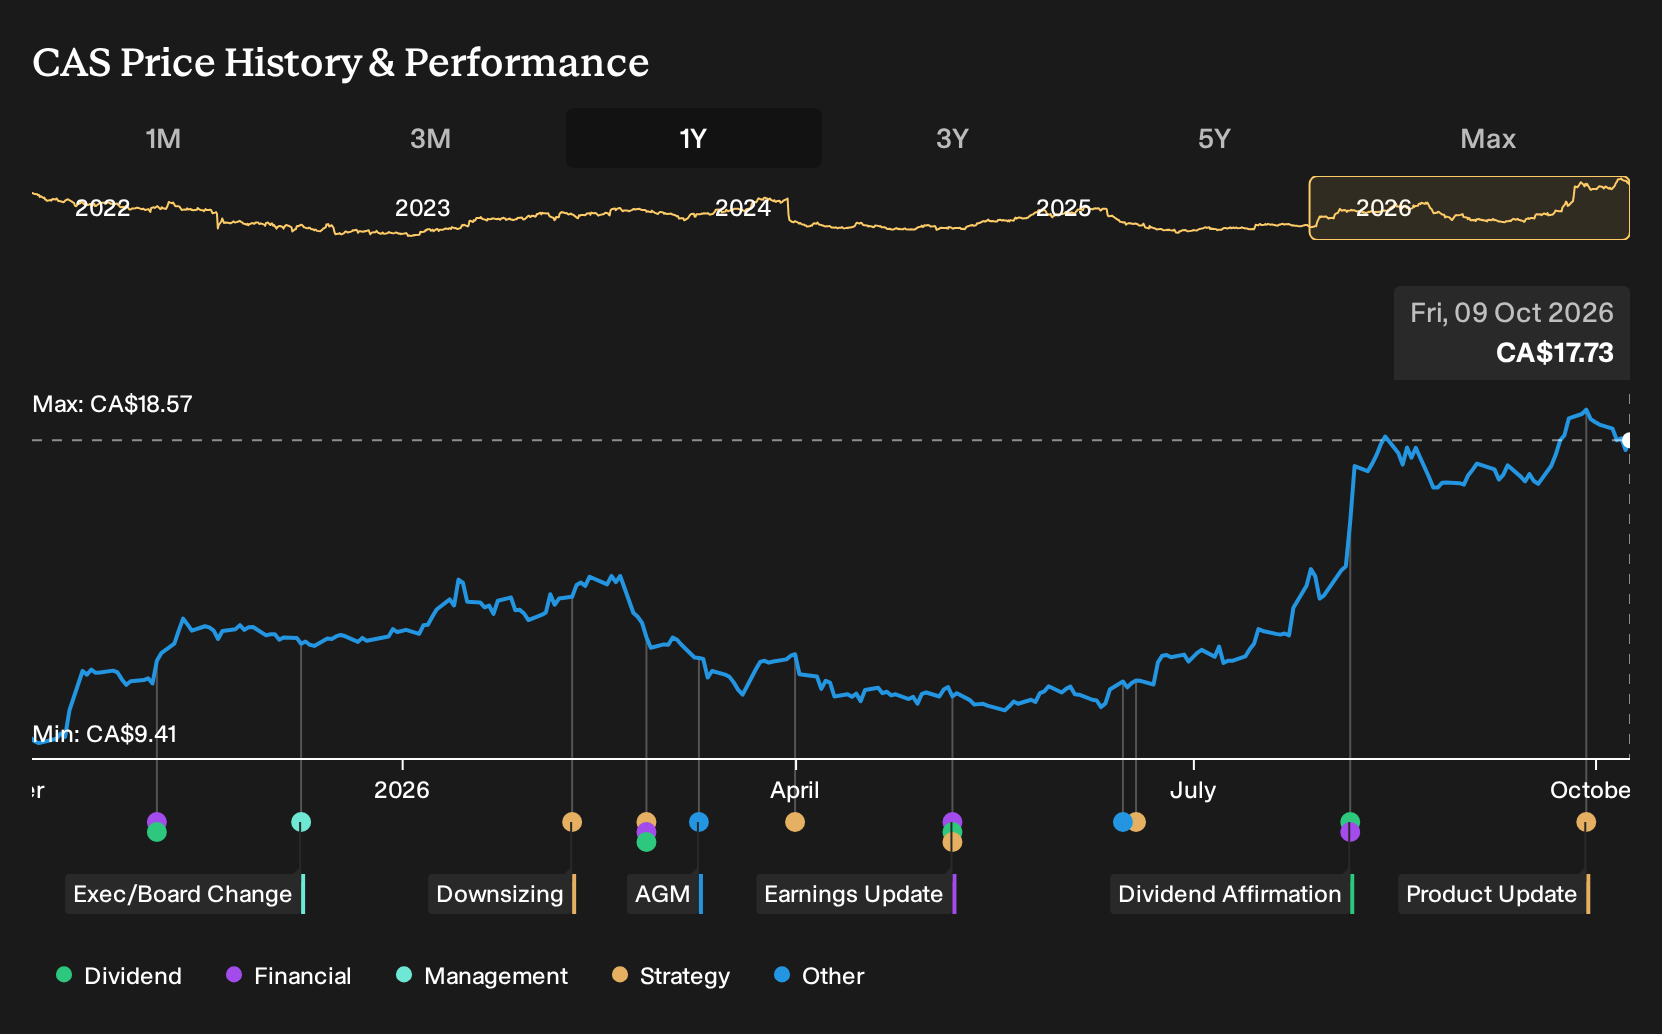
Exploring Other Perspectives
One alternate view puts the risk on Cascades’ capital burden rather than its volumes. The most pessimistic analysts were already baking in about CA$5.4b revenue and CA$337.4 million earnings by 2029, yet still only landed on a CA$17.0 fair value. Those estimates came before lithoURB and the SBTi targets, so your own take might shift.
Explore 2 other Cascades fair value estimates, including one that suggests it could be worth just CA$18.50.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cascades research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cascades. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cascades' overall financial health at a glance.
Looking For More Ideas Beyond Cascades?
If you want to stress test your view on Cascades against other opportunities, a quick pass through the Simply Wall St Screener can surface very different risk and reward profiles in a few minutes.
- For investors comfortable with higher volatility in search of meaningful upside swings, take a look at 19 elite penny stocks with strong financials that already show stronger fundamentals than the typical micro cap.
- If capital preservation sits high on your priority list, review a 7 resilient stocks with low risk scores that score well on resilience and more measured risk profiles.
- When you want quality businesses that are not yet crowded trades, scan a 9 high quality undiscovered gems that pair solid financials with relatively limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com