


17% Below Fair Value? Japan Hotel REIT Investment (TSE:8985) On New Rate Swaps
Interest rate swaps reshape Japan Hotel REIT Investment debt profile
Japan Hotel REIT Investment (TSE:8985) has moved to lock in more of its borrowing costs, signing new interest rate swap contracts tied to recent refinancing, including a green loan component.
The trust has hedged three term loans with MUFG Bank using swaps that exchange floating JBA 1‑month Yen TIBOR for fixed rates. This effectively sets all‑in interest costs between 2.73% and 3.30% on the covered borrowings.
After these contracts, management expects roughly 79% of its interest bearing debt to carry fixed rates. This provides income focused investors with clearer visibility on financing costs over the swap terms.
At a share price of ¥79,200, Japan Hotel REIT Investment has seen its 1 month share price return fall 5.83%, yet a 3 year total shareholder return of 29.42% and 5 year total shareholder return of 41.91% point to longer term holders still ahead. The latest move to increase fixed rate debt is likely feeding into how investors weigh interest rate risk against income stability.
Scan a hand picked set of income focused REITs managing rate risk in different ways through our 23 resilient stocks with low risk scores to see how Japan Hotel REIT Investment compares on balance sheet resilience.
Japan Hotel REIT Investment now trades at a discount to both analyst targets and intrinsic estimates, even after tightening its debt costs. How wide is the gap between that pricing and a reasonable view of fair value?
Preferred P/E of 17.9x for Japan Hotel REIT Investment: Is it justified?
On valuation, Japan Hotel REIT Investment closed at ¥79,200, which implies a P/E of 17.9x that screens as expensive against both its global hotel REIT peers and its closer peer set.
The P/E ratio compares the current unit price with earnings per unit and gives a quick sense of what investors are paying for each yen of profit. For a hotel focused REIT like Japan Hotel REIT Investment, this matters because distributions and asset purchases are closely linked to recurring earnings power.
Here, the trust trades on 17.9x earnings compared with 12.3x for the broader Global Hotel and Resort REITs group and 15.3x for its peer average, which means the market is paying a higher multiple for the same yen of profit. At the same time, the estimated fair P/E of 19x sits above the current ratio. This points to a level the market could move toward if sentiment and fundamentals stay aligned with that regression based view.
Explore the SWS fair ratio for Japan Hotel REIT Investment.
Result: Price-to-earnings of 17.9x (OVERVALUED).
Still, the 12 month total return has fallen 4.60% and annual net income growth has declined 3.16%. This could limit how far Japan Hotel REIT Investment re rates.
Find out about the key risks to this Japan Hotel REIT Investment narrative.
Another view on Japan Hotel REIT Investment valuation
P/E suggests Japan Hotel REIT Investment is on the expensive side, yet the SWS DCF model points the other way. At ¥79,200 the units trade about 17.2% below an estimated future cash flow value of ¥95,657.9, which frames the trust as undervalued. Which signal appears more compelling in your view?
Look into how the SWS DCF model arrives at its fair value.
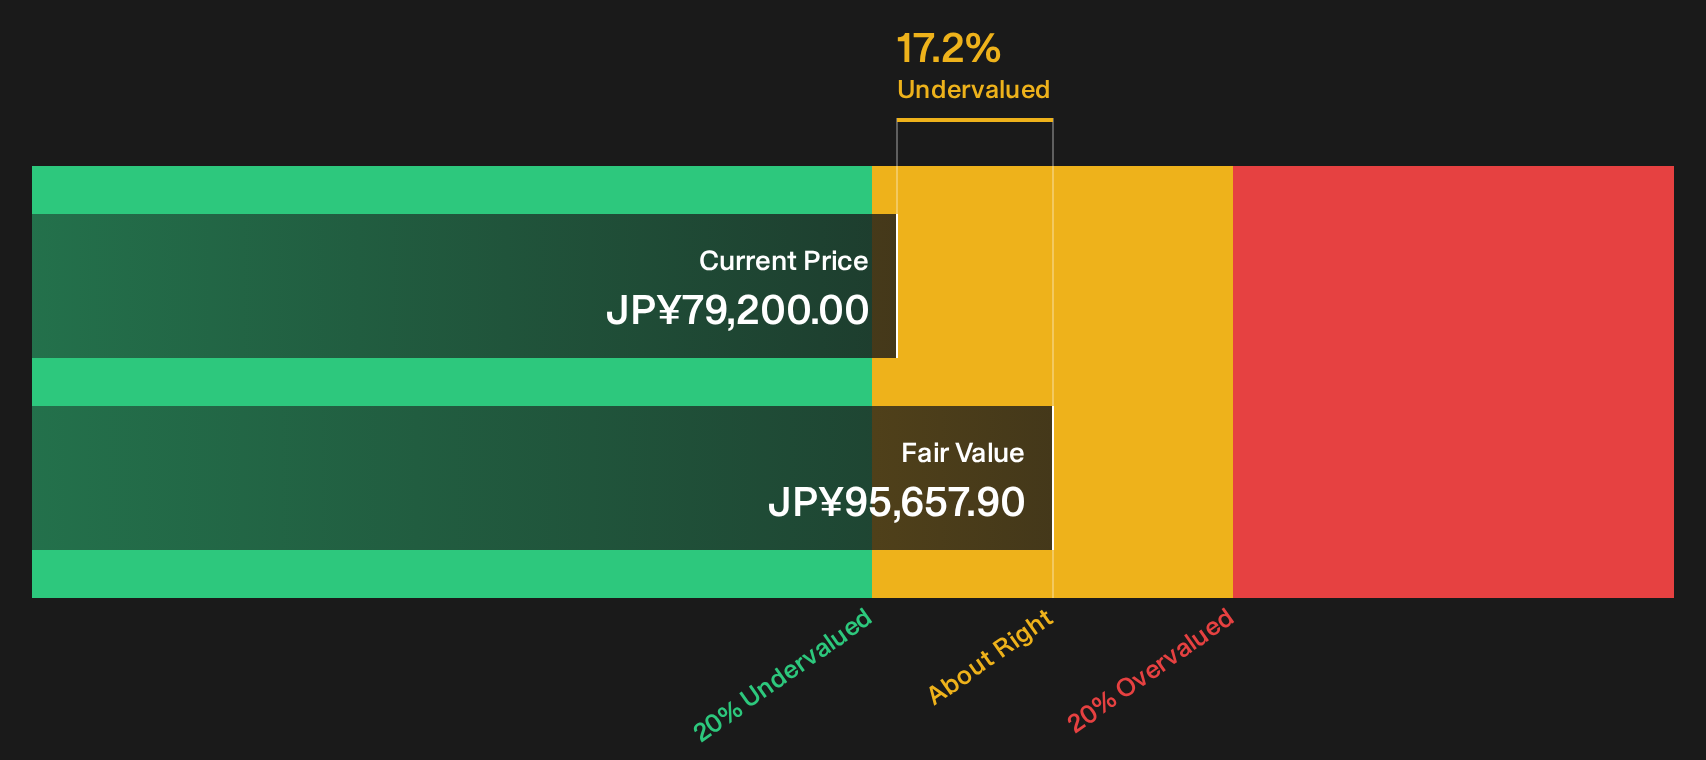
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Hotel REIT Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a simple mismatch between price, risk and opportunity around Japan Hotel REIT Investment? Act while the data is fresh in your mind and weigh the evidence yourself, then round out your view with 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Japan Hotel REIT Investment?
If Japan Hotel REIT Investment has sharpened your focus on price, risk and income, broaden your watchlist now with fresh ideas filtered by clear, disciplined rules.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (23 results) that highlight businesses aiming to keep financial risk in check.
- Hunt for potential mispricings with the 12 high quality undervalued stocks that surfaces companies where quality metrics and valuation screens currently look out of sync.
- Lock onto income focused opportunities using the 28 dividend fortresses that concentrates on higher yield payouts backed by underlying financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com