


Westpac Banking (ASX:WBC) Faces Rate Hike Scrutiny, Does It Look Fairly Valued?
Recent commentary around Westpac Banking (ASX:WBC) has sharpened after a central bank rate hike weakened Australian consumer sentiment and prompted investors to recheck the bank’s valuation and profit outlook.
At around A$33.72, Westpac Banking’s share price reflects a weaker tone in recent months, with the 90 day share price return down 7.72% and the year to date share price return down 13.43%. However, the 3 year total shareholder return of 83.08% and 5 year total shareholder return of 73.15% remain robust, suggesting momentum has cooled as investors weigh rate hike risks and questions over how efficiently the bank is using its capital.
Spot opportunities beyond Westpac Banking by scanning a curated 4 high quality undervalued stocks that already reflect solid cash generation and balance sheet strength.Westpac Banking has given investors a powerful three year run, only to hand back a chunk of it this year as rate hikes bite. Does that reset now tilt the risk reward toward caution or fresh buying interest?
Most Popular Narrative: 1% Overvalued
Compared to the most followed fair value estimate of A$33.47, Westpac Banking at A$33.72 screens as slightly rich but broadly in line with that narrative view, which leans on modest growth and tight margins.
Intense competition in the consumer banking segment, particularly in mortgages, is putting pressure on net interest margins, which is expected to compress net margins further in the future. Rising technology costs and investments in projects like UNITE have significantly increased operating expenses, which are expected to continue growing. This could negatively impact net margins as cost growth may outpace revenue growth.
See why 96 investors see Westpac Banking as 1% overvalued.
Result: Fair Value of A$33.47 (OVERVALUED)
Still, if Westpac Banking extracts efficiency gains from UNITE or maintains tight credit quality, that could soften margin pressure and challenge the slightly overvalued narrative.
Find out about the key risks to this Westpac Banking narrative.
Another View: What Westpac Banking’s P/E Is Saying
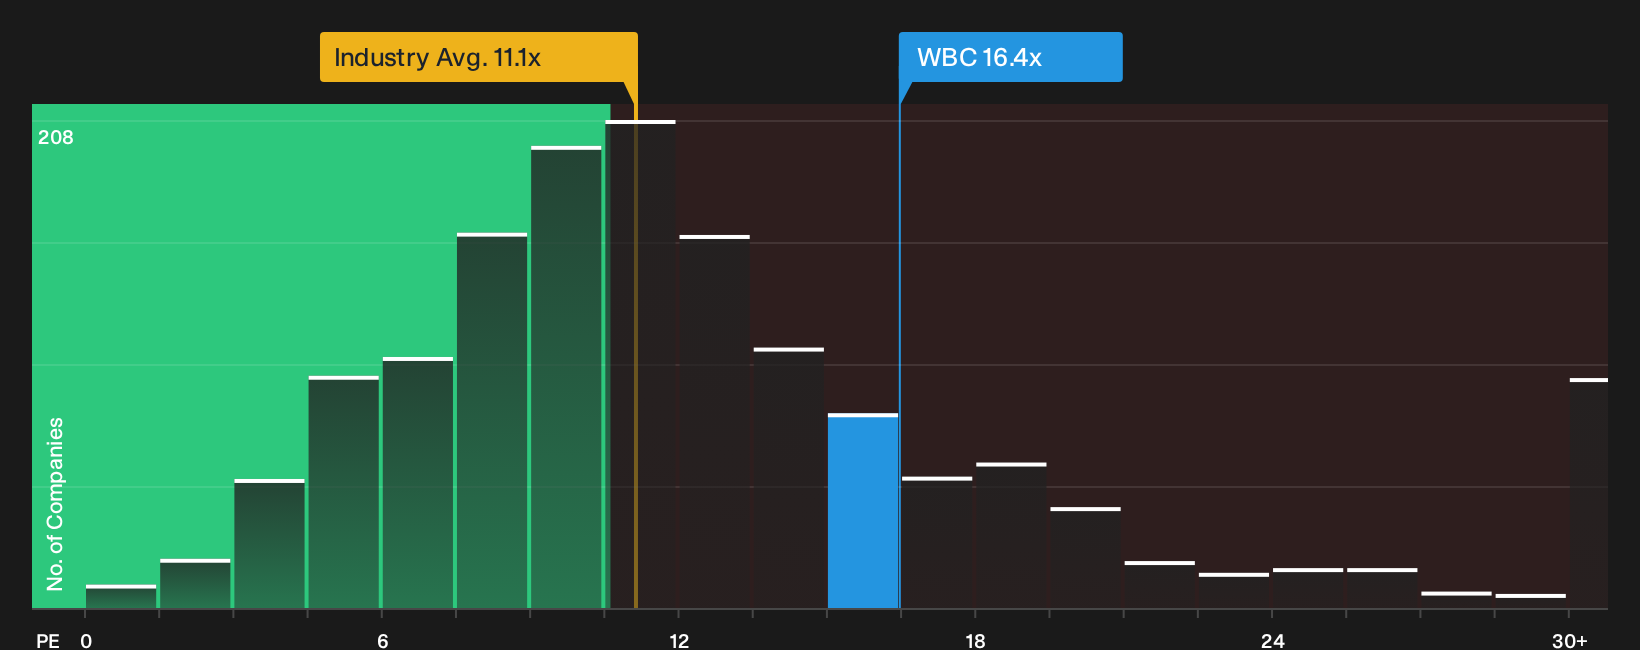
There is a different read on Westpac Banking when looking at its P/E. At 16.4x, the stock trades below the peer average of 17.5x, and below its own fair ratio of 17.1x. That points to a modest valuation cushion rather than clear overpricing. Could this gap close if sentiment steadies?
For a closer look at how this earnings multiple stacks up against peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Westpac Banking do not have to leave you on the fence. Move quickly from headline takes to your own evidence based view with the full breakdown of 1 key reward and 3 important warning signs
Want more ideas beyond Westpac Banking?
If you stop with just Westpac Banking, you risk missing out on other opportunities that could align more closely with your goals and risk comfort.
- Target stronger cash generation and potential mispricing by scanning companies flagged as resilient and potentially undervalued through the 4 high quality undervalued stocks.
- Prioritise capital protection and steadier compounding by reviewing companies identified as having sturdier financial profiles in the 7 resilient stocks with low risk scores.
- Hunt for under-followed opportunities with solid fundamentals by checking the 15 high quality undiscovered gems before the wider market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com