


Mondelez International (MDLZ) Teams Up With Portillo’s, Is The Stock Still 13% Undervalued?
Mondelez International (MDLZ) is back in the headlines after Oreo partnered with Portillo’s to roll out three limited-time desserts nationwide, putting the cookie brand at the center of Halloween-season indulgence.
For Mondelez International, the Oreo and Portillo’s tie-up lands at a time when short-term momentum is mixed, with a 7-day share price return of 3.82% but a 30-day share price return that declined 3.22%. At the same time, the year-to-date share price return of 12.60% and 5-year total shareholder return of 14.99% signal steadier progress in the background.
Scan other snack and beverage players that analysts highlight for brand strength and potential mispricing using our curated list of 28 high quality undervalued stocks.
After a sharp Halloween themed spotlight and a mixed near term return pattern, Mondelez International now asks a simple question of investors. Does the current price still leave enough upside in the risk reward to justify new money?
Most Popular Narrative: 13% Undervalued
At a last close of $60.41 against a narrative fair value of $69.13, the Mondelez International story leans toward upside in the model, with that gap hinging on how well reinvestment and cost trends translate into earnings over the next few years.
The company is continuing to reinvest upside into brands, emerging markets and distribution, with raised 2026 organic net revenue guidance to at least 2% and maintained EPS guidance alongside double digit advertising and consumer spending. This reflects an ongoing effort to build future revenue and earnings rather than maximize short term profit.
See why 99 investors see Mondelez International as 13% undervalued.
Result: Fair Value of $69.13 (UNDERVALUED)
Still, the Mondelez International narrative can break if cocoa costs spike again or if North American demand softens while reinvestment spending remains elevated.
Find out about the key risks to this Mondelez International narrative.
Another View: Mondelez International Through The P/E Lens
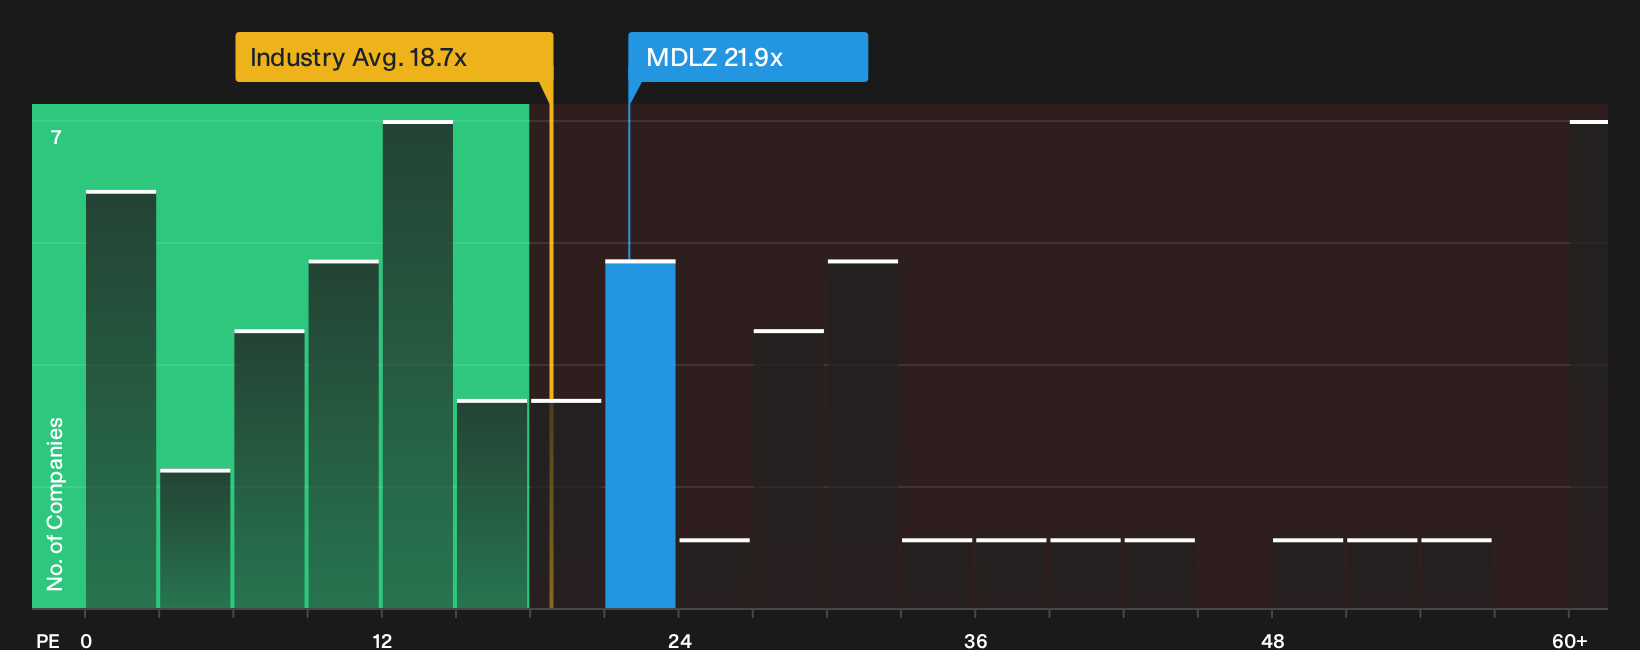
Mondelez International might look cheap on narrative fair value, yet its P/E of 21.9x tells a tougher story. The stock trades richer than the US Food industry on 18.7x and even above its own fair ratio of 21.3x, which points to less margin for error if earnings disappoint.
That richer rating leaves investors asking whether Mondelez International has enough earnings power to support a premium if sector sentiment cools, or whether the P/E eventually drifts closer to the fair ratio instead of the cash flow based upside implied elsewhere.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mondelez International now sits at a crossroads in this story of potential upside and real risk. Act quickly, review the data for yourself, and weigh both sides by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mondelez International?
You have the Mondelez International story. Now sharpen your watchlist by lining up a few more targeted ideas that fit the portfolio you actually want to build.
- Target potential mispricing in established businesses by checking a curated pool of companies that screen as attractively valued through the 28 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies that combine higher yields with resilience using the 8 dividend fortresses.
- Reduce portfolio stress by concentrating on businesses with healthier balance sheets and sturdier fundamentals through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com