


Is Rockwool (CPSE:ROCK B) Undervalued After Weaker Demand And Cost Pressure?
Rockwool (CPSE:ROCK B) is back in focus after RBC Capital Markets highlighted pressure on European building materials, citing weaker Q3 demand and higher costs, while the group reported softness in Germany and France.
Recent trading reflects that caution. Rockwool’s share price is up 2.68% over the last day to DKK183.8 yet still down 18.07% year to date, and the 1 year total shareholder return has declined 19.90%, signalling momentum that has faded despite a 21.27% gain over three years.
Scan beyond Rockwool and assess other building and industrial players facing similar demand and cost pressures with our hand picked list of solid balance sheet and fundamentals (204 results)
So is Rockwool’s recent bounce a sign that investors are reassessing the underlying insulation business, or just a brief sentiment swing in a sector still wrestling with weaker European demand and cost pressure that the current valuation needs to answer?
Most Popular Narrative: 21% Undervalued
Rockwool’s most followed narrative points to a fair value of DKK231.40, which sits well above the last close at DKK183.80 and puts the recent move into context as part of a wider valuation gap rather than just a one day reaction.
Ongoing and near-term capacity expansions in key growth markets (U.S., Romania, India, West Coast U.S., France), including new electrified production lines, position Rockwool to capitalize on surging demand from tighter building codes and energy efficiency mandates. This is expected to support both top-line growth and higher utilization-driven margin leverage over the medium
to long-term.
See why 15 investors see Rockwool as 21% undervalued.
Result: Fair Value of DKK231.40 (UNDERVALUED)
Still, Rockwool’s story can crack if weaker project demand lingers or if new capacity ramps up slowly, leaving factories underused and returns on fresh investment under pressure.
Find out about the key risks to this Rockwool narrative.
Another View On Rockwool’s Valuation
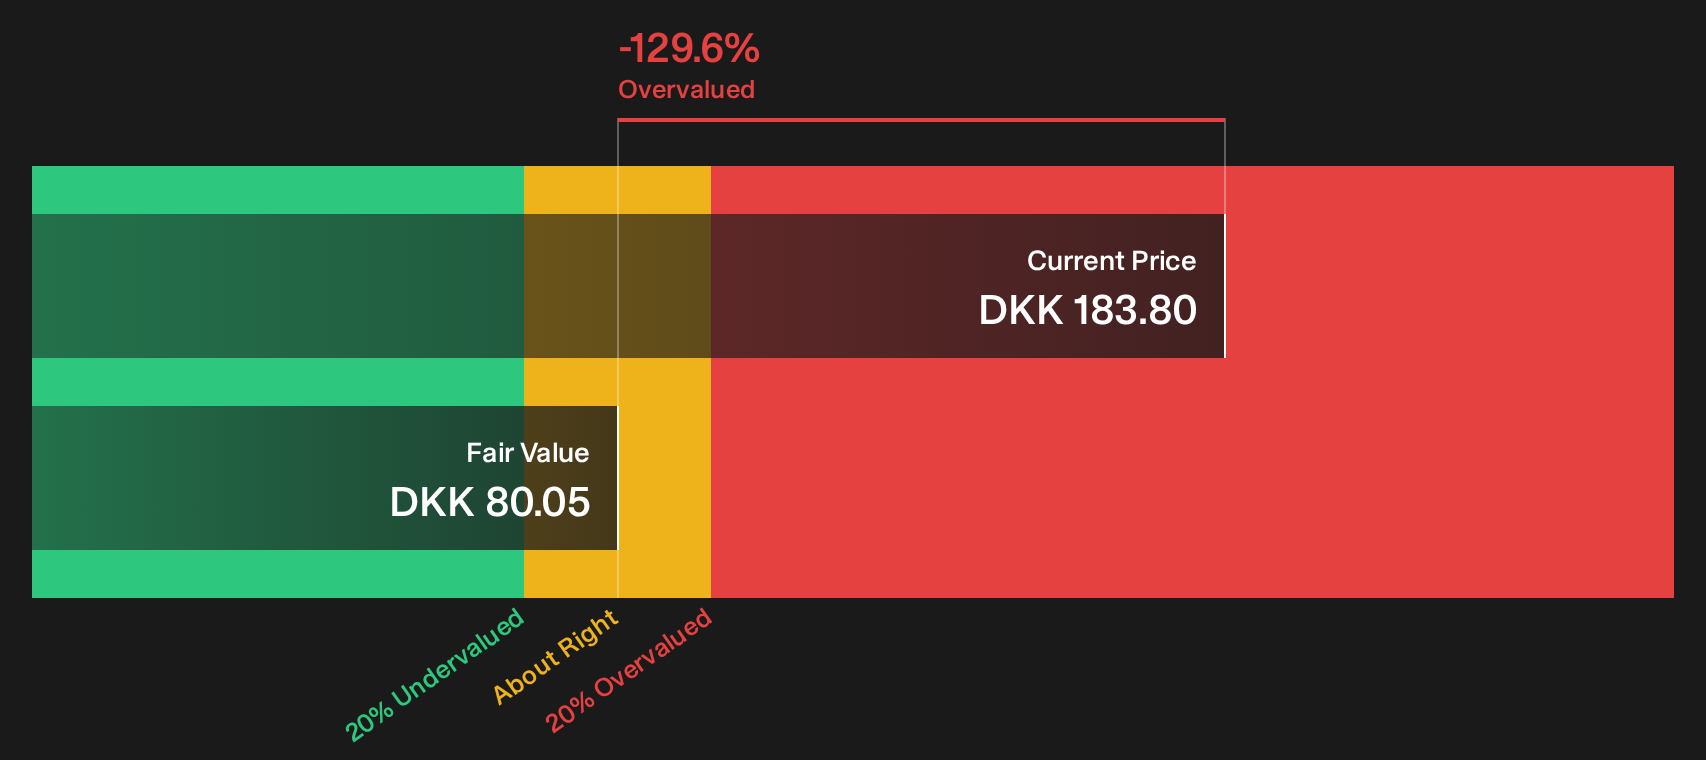
The analyst-driven fair value for Rockwool points to upside, yet the SWS DCF model paints a very different picture. On that framework, CPSE:ROCK B is trading well above an estimated future cash flow value of DKK80.05, which implies the shares screen overvalued rather than cheap. Which story do you trust more: the cash flows or the consensus?
For a closer look at how this model works in practice, including the key assumptions behind the cash flow path and discount rate, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Rockwool’s valuation and business outlook make this a moment to move quickly, review the underlying data carefully, and decide where you stand using the 2 key rewards and 3 important warning signs.
Looking for more Rockwool style investment ideas?
If Rockwool has you reassessing what real value looks like, do not stop here. Broaden your watchlist and give yourself better options.
- Target resilient balance sheets by scanning companies that pass strict financial strength tests with the list of solid balance sheet and fundamentals (204 results).
- Hunt for potential mispriced opportunities by reviewing our hand picked pool of 618 high quality undiscovered gems.
- Stack income ideas by lining up companies that feature 223 dividend fortresses and could complement more growth focused holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com