


Nagase (TSE:8012) Has Gained Ground, Is The Valuation Case Still Convincing?
Why Nagase Stock Is On Investors’ Radar
Nagase (TSE:8012) has drawn fresh attention after a recent move in its share price, with the stock last closing at ¥1,210.5 following a solid month of positive returns.
The recent 5.2% 30-day share price return adds to a stronger year-to-date move of 23.8%, while the 1-year total shareholder return of 55.6% and 5-year total shareholder return of 190.4% show that momentum in Nagase has been building over time.
See how Nagase’s recent strength compares with other potential breakout candidates in our hand picked list of 12 high quality undervalued stocks.
Nagase now trades about 20% below the ¥1,450 analyst target, yet recent gains and a modest intrinsic value discount hint at market hesitation. Is that caution misplaced, or entirely rational given the fundamentals?
Price-to-Earnings of 12.3x: Is it justified?
On simple valuation math, Nagase trades on a P/E of 12.3x, which sits below the wider JP market on 13.7x but above the Trade Distributors group on 10.3x. That split view is exactly what is feeding the current debate around whether the recent share price strength has run ahead of fundamentals or not.
The P/E ratio compares the current share price with earnings per share and gives a quick read on how much investors are paying for each unit of profit. For a diversified chemicals and materials trader like Nagase, earnings quality and consistency matter a lot, because this is what tends to drive how much of a premium or discount the market is willing to accept.
Here the signals are mixed. The stock looks inexpensive relative to the overall JP market, yet it screens as expensive against both the Trade Distributors industry average P/E of 10.3x and a peer group average of 10.7x. At the same time, the estimated fair P/E of 14.9x is materially higher than the current 12.3x, which suggests the market could still shift closer to that fair ratio level if the current earnings profile holds.
Explore the SWS fair ratio for Nagase.
Result: Price-to-Earnings of 12.3x (ABOUT RIGHT)
Still, the wide spread between Nagase’s trading multiple and sector P/Es could close quickly if earnings quality weakens or if analyst expectations on the ¥1,450 target shift.
Find out about the key risks to this Nagase narrative.
Another View: DCF Paints A Cooler Picture For Nagase
The multiple story on Nagase looks broadly fair, yet the SWS DCF model tells a different story. On that score, the shares at ¥1,210.5 sit above an estimated future cash flow value of ¥989.97, which leans toward overvaluation and puts more weight on execution risk than the P/E implies.
For readers who want to see how that cash flow based view is built step by step, Look into how the SWS DCF model arrives at its fair value.
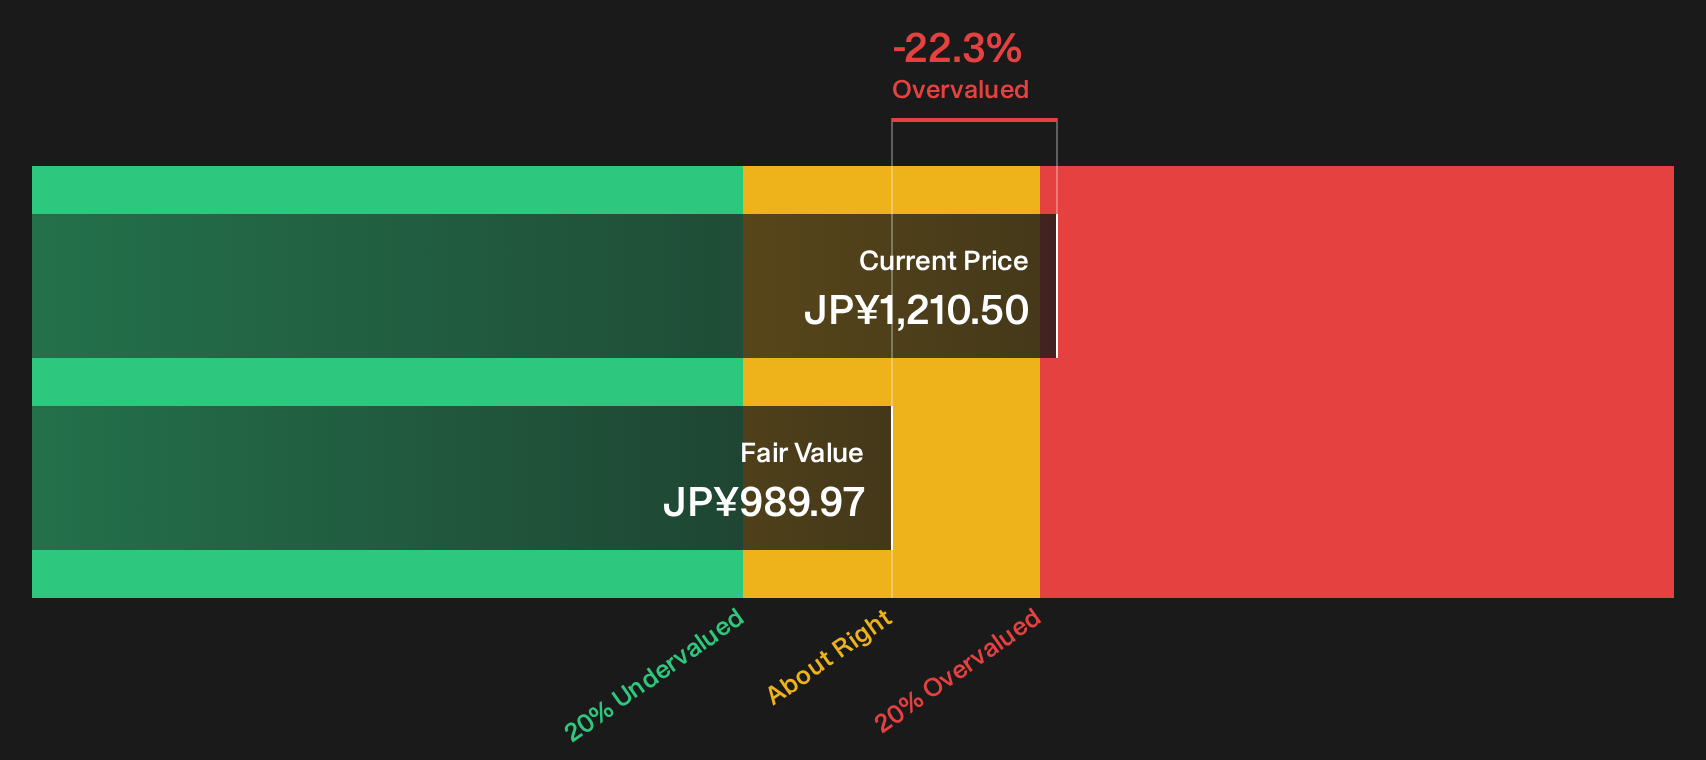
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nagase for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the signals on Nagase feel split, that is exactly the point. The data shows both risk and upside potential, so it pays to look closely at the full picture. To see the balance of caution and optimism that other investors are focused on, take a closer look at the 3 key rewards and 1 important warning sign
Looking for more Nagase sized investment ideas?
Do not stop your research with Nagase. Broaden your watchlist with a few focused stock ideas that match how you like to balance risk and opportunity.
- Target potential income streams by scanning a curated group of potential dividend payers through the 28 dividend fortresses.
- Focus on financial resilience by checking a list of solid balance sheet and fundamentals (23 results) that can help you avoid fragile balance sheets.
- Explore potential market leaders early by reviewing a focused set of 74 high quality undiscovered gems before the wider market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com