


How Investors Are Reacting To Unity Stock AI Gaming Partnership
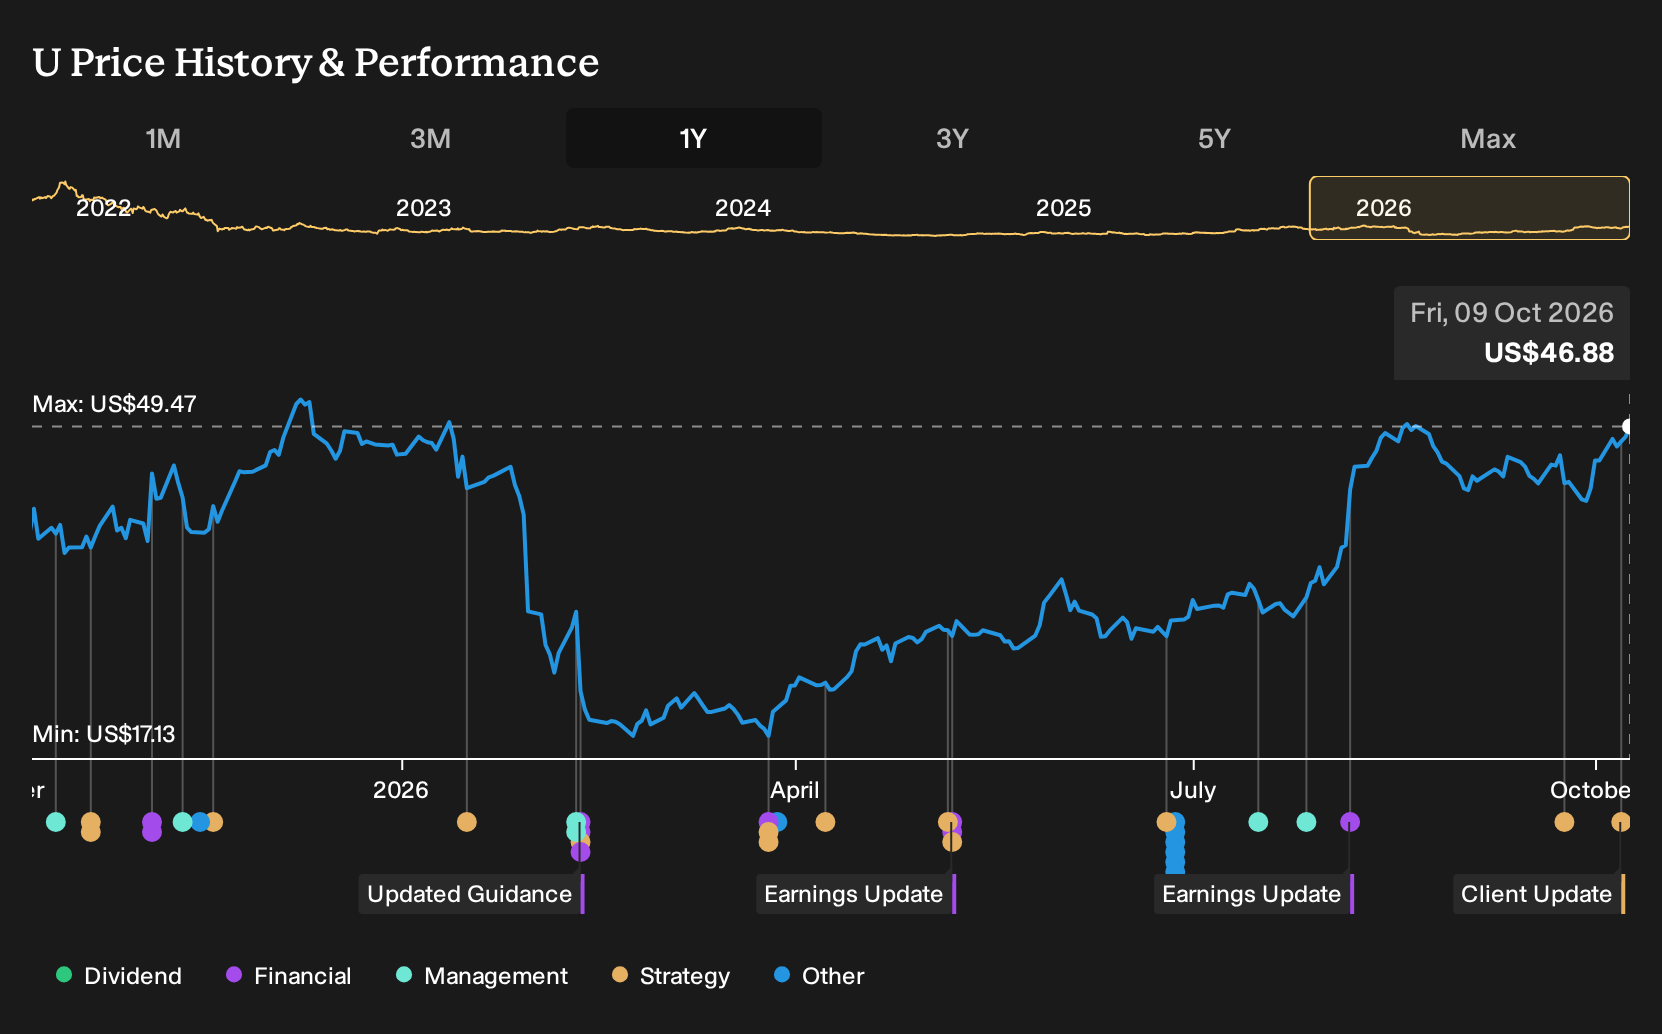
- Google and Unity Software announced a partnership in October 2026 to build an integrated AI-driven gaming platform, including the new Unity Spark creation experience built on Playground and tightly linked to Google’s consumer ecosystem.
- The collaboration ties Unity’s engine and creation tools directly into Google’s AI research, discovery channels, and community features. This development could reshape how the business attracts creators, drives engagement, and monetizes tools and services across its platform.
- Next, the focus shifts to how Unity Software's broader investment narrative could be influenced by this Google-backed AI creation platform.
Scan how Unity Software’s AI shift compares with other potential breakout plays by screening for 36 AI small caps riding similar creator and gaming trends.
Unity Software Investment Narrative Recap
To hold Unity Software, you need to believe its engine, AI tools, and ad products can turn a large creator base into growing, recurring cash flows. The Google partnership sits right in that story, because it plugs Unity’s creation stack into a large consumer funnel. The short term swing factor remains whether user and customer activity translates into higher margin software and services, not just buzz around AI.
The biggest near term risk is still cost and execution. Unity is spending heavily on AI and new products while it is unprofitable and trading on a rich P/S multiple. If Unity Spark and related tools do not gain traction quickly with paying users, the Google news may not meaningfully change that path to profitability.
Among Unity’s recent developments, the 24% rise in revenue from advertising solutions is most relevant to this Google announcement. The Playground and Unity Spark platform is built around discovery, matchmaking, and community features, which are closely connected to Unity’s Grow Solutions and ad products. Stronger engagement can support more ad inventory and more monetization opportunities if creators and players continue to use the platform.
For you as an investor, the link between this announcement and that advertising momentum is straightforward. If Google’s large user base drives more traffic into games built on Unity Spark, Unity has a larger pool of impressions to sell and optimize. The execution test is whether Unity can manage higher infrastructure and R&D spend while converting that usage into durable, cash generative advertising and subscription revenue.
Unity Software Forecasts and Valuation Check
Unity Software's analyst narrative points to revenues of US$3.6b and earnings of US$989.9m by 2029. That profile lines up with an assumed 20.6% yearly revenue growth rate and an earnings swing of about US$1.58b from a loss of US$587.5m today.
Uncover why Unity Software's fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You also need to weigh a very different worry from the alternate Unity Software narrative. Some of the most pessimistic analysts focus on simpler no code tools slowly squeezing Unity’s relevance, which is why they were only pencilling in about US$3.0b of revenue and US$850.9m of earnings by 2029. Their views, formed before this Google partnership, could shift materially. Treat them as one lens and compare several before deciding what feels reasonable for you.
Explore 3 other Unity Software fair value estimates, including one that suggests it could be worth just $49.39.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Unity Software research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Unity Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Unity Software's overall financial health at a glance.
Looking for more Unity Software investment ideas?
If this Unity Software story has you thinking about what else might fit in your portfolio, it can help to scan a broader set of stocks that share some of the qualities you care about most.
- If capital preservation is near the top of your list, start with 31 resilient stocks with low risk scores that pair steadier risk profiles with more resilient fundamentals.
- For investors hunting for mispriced opportunities, cast a wider net across 28 high quality undervalued stocks that screen well on both quality and valuation.
- If balance sheet strength gives you confidence to hold through volatility, focus on our list of solid balance sheet and fundamentals (25 results) and see which companies clear that bar for you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com