


Is Datang International Power Generation (SEHK:991) Cheap As Board Approvals Lift Nuclear And Loan Commitments?
Board decisions reshape Datang International Power Generation’s capital commitments
Datang International Power Generation (SEHK:991) has drawn fresh attention after its board on 9 October 2026 approved higher capital contributions to China Datang Corporation Nuclear Power Company Limited and special-purpose entrusted loans to certain enterprises.
The latest board decisions come after a strong run in Datang International Power Generation’s shares. The HK$2.72 share price has been supported by a 24.2% year to date share price return and a three year total shareholder return above 160%. However, the 30 day share price return has slipped, suggesting that recent momentum has cooled, even as the longer term total shareholder return remains very strong.
Scan how Datang International Power Generation’s latest capital commitments compare with other utilities reallocating capital into large projects by reviewing our curated list of 43 power grid technology and infrastructure stocks.
After a long stretch of strong total returns and fresh capital commitments into nuclear and entrusted loans, the question now is whether Datang International Power Generation still offers enough upside for the risk you take on at HK$2.72.
Preferred Price-to-Earnings of 6.3x: Is it justified?
Valuation on Datang International Power Generation currently leans heavily on earnings, with the shares trading on a P/E of 6.3x at a last close of HK$2.72, a level that screens as inexpensive relative to both its own cash flow valuation and key peers.
The P/E ratio compares what investors pay for each dollar of profit, so a lower figure often points to lower expectations or higher perceived risk. For a power producer generating income from coal, hydro, wind, nuclear and solar, this measure links directly to how reliably those earnings can support future capital projects and dividends.
Datang International Power Generation screens as good value on this basis, with its 6.3x P/E well below the Asian Renewable Energy industry average of 13.9x and the peer average of 12.2x. That gap suggests the market is assigning a clear discount to the stock relative to similar businesses, even as earnings grew 50.9% over the past year and net profit margins sit at 5.5%, up from 3.7%.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 6.3x (UNDERVALUED)
Still, Datang International Power Generation faces real pressure if capital heavy nuclear projects overrun budgets or if entrusted loans tie up cash without clear returns.
Find out about the key risks to this Datang International Power Generation narrative.
Another view on Datang International Power Generation’s value
The P/E of 6.3x makes Datang International Power Generation look inexpensive, yet the SWS DCF model points to a very different picture. That approach anchors on projected cash flows and puts fair value at HK$38.56, far above the current HK$2.72 level.
Such a wide gap between an earnings multiple and a cash flow model raises a practical question for you as an investor. Is the market correctly discounting long term cash generation risk, or is the DCF leaning on assumptions that are too optimistic for a capital intensive utility?
Look into how the SWS DCF model arrives at its fair value.
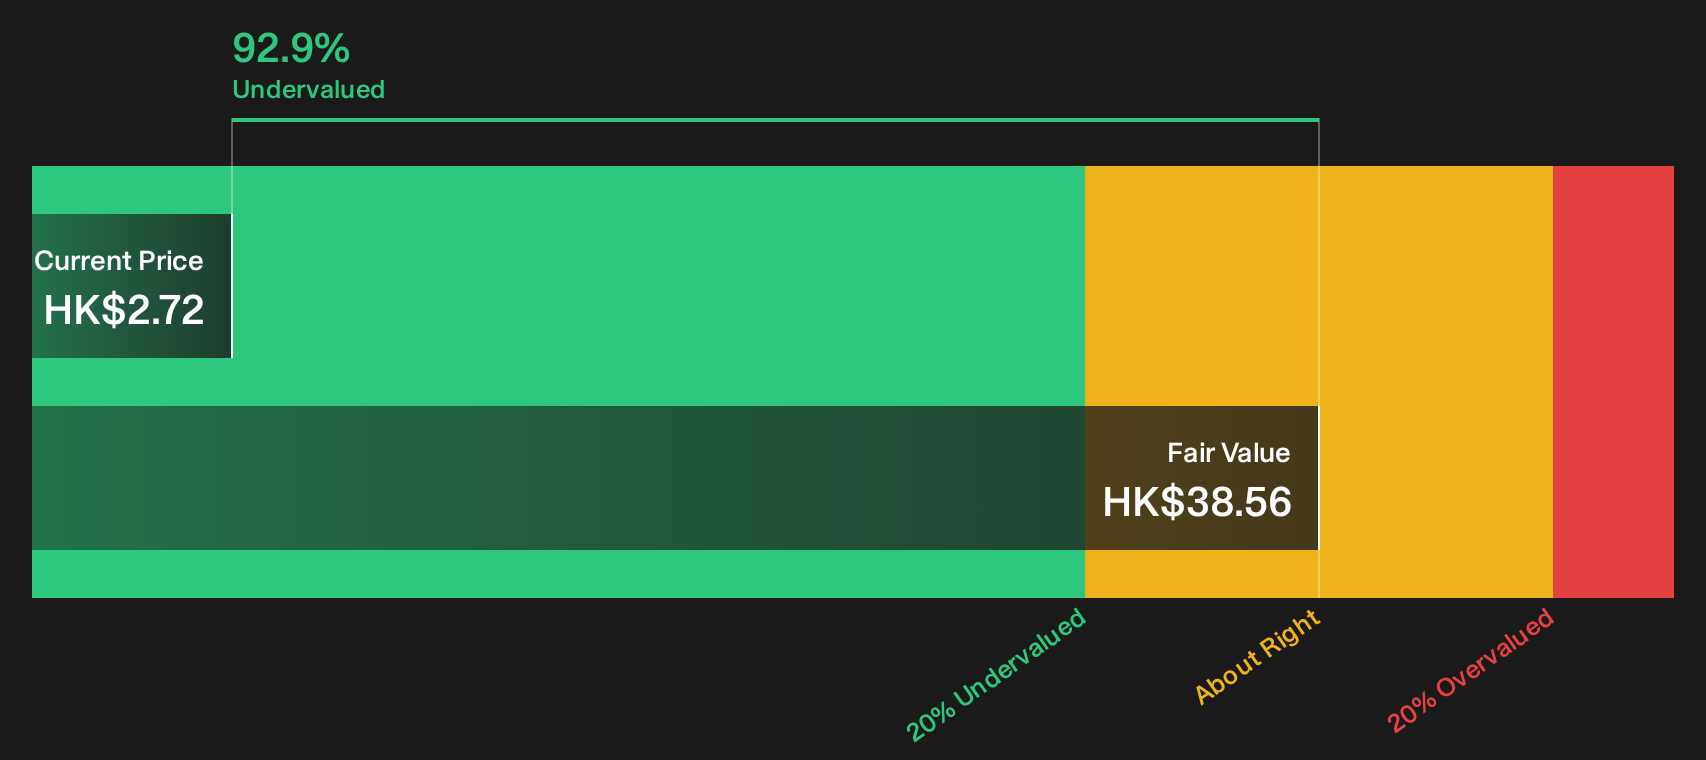
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Datang International Power Generation for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in Datang International Power Generation’s valuation and capital commitments can feel confusing, so review the data, weigh both sides, and then check the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Datang International Power Generation?
If Datang International Power Generation feels fully priced for your risk appetite, widen your watchlist and use data driven screeners to surface fresh opportunities.
- Target potential bargains by scanning a focused set of mispriced quality stocks with the 174 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by sorting companies through the 222 resilient stocks with low risk scores.
- Spot robust businesses that are not stretched thin by debt by using the list of solid balance sheet and fundamentals (204 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com