


Alnylam Pharmaceuticals (ALNY) Could Be 37% Undervalued After TTR Sales Probe
Investor focus on Alnylam Pharmaceuticals (ALNY) has sharpened after news of a securities fraud investigation tied to reduced TTR sales expectations, prompting a fresh look at earnings durability and the company’s broader RNAi pipeline.
Over the past year, Alnylam Pharmaceuticals has swung from a strong multi‑year total shareholder return to a sharp reset, with the share price down 41.85% year to date and the 1 year total shareholder return declining 49.47%. Recent 1 week and 1 day share price gains suggest sentiment is stabilising rather than clearly building or fading.
Position your Alnylam Pharmaceuticals view alongside other biotech reset stories by scanning a curated group of 20 high quality undiscovered gems that the market may not be fully pricing yet.Bulls see a premium RNAi platform unfairly penalised by a sharp reset, while bears see fragile TTR assumptions and legal overhangs. Which side does Alnylam Pharmaceuticals’ current valuation actually support as you line it up against the numbers?
Most Popular Narrative: 37% Undervalued
The most followed valuation narrative for Alnylam Pharmaceuticals pegs fair value at about $371 per share, well above the recent $232.68 close. This puts the current debate squarely on whether the RNAi pipeline can justify that gap.
The broad RNAi portfolio at Alnylam Pharmaceuticals, with more than 25 programs across rare, specialty and prevalent conditions and multiple pivotal studies underway, creates repeated opportunities for new approvals that could add incremental revenue streams and help spread fixed R&D and SG&A over a larger sales base, which may support earnings.
See why 28 investors see Alnylam Pharmaceuticals as 37% undervalued.
Result: Fair Value of $371.35 (UNDERVALUED)
Still, the narrative around Alnylam Pharmaceuticals can crack if AMVUTTRA pricing pressure deepens or if zilebesiran and other prevalent disease programs underperform expectations.
Find out about the key risks to this Alnylam Pharmaceuticals narrative.
Another View: What Multiples Say About Alnylam Pharmaceuticals
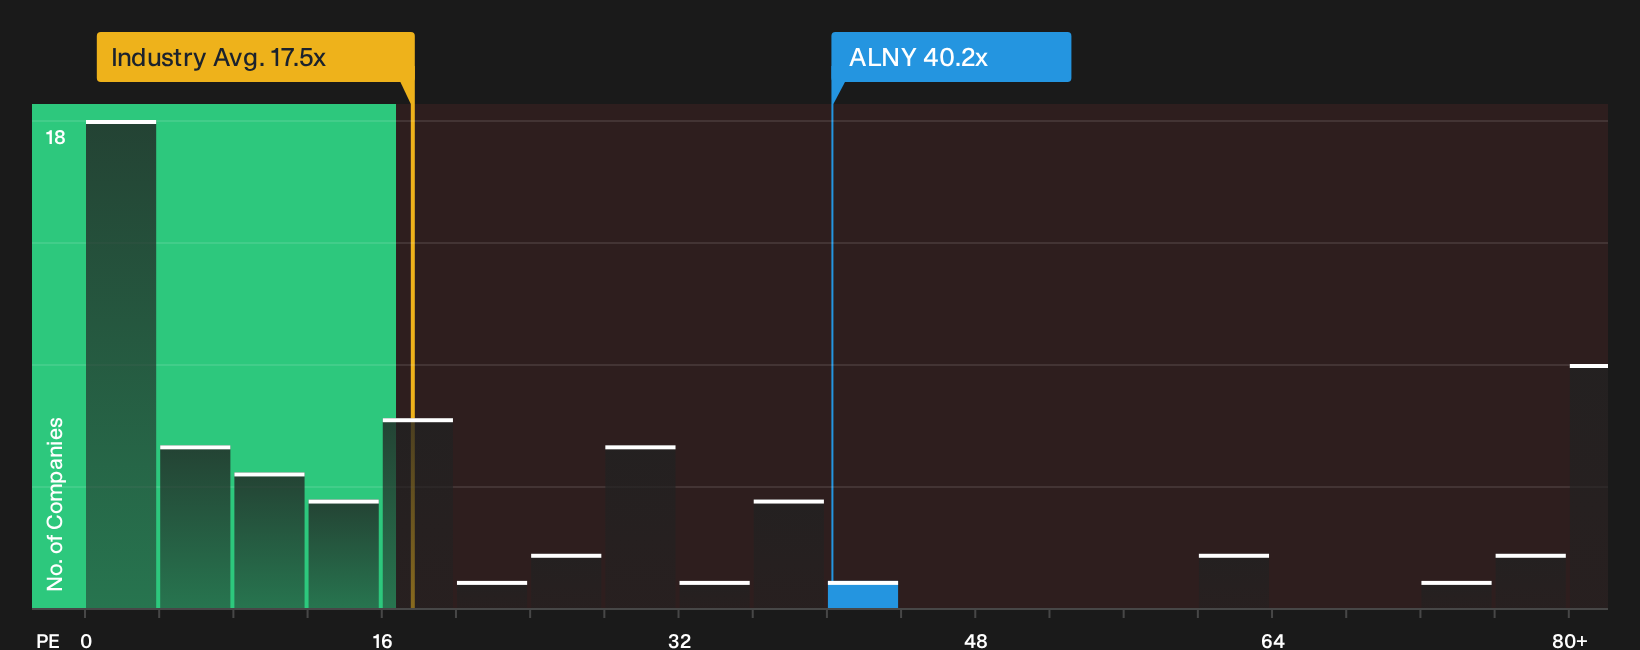
The DCF workup presents Alnylam Pharmaceuticals as deeply undervalued, yet the P/E ratio tells a tougher story. At 40.2x, the stock trades above both peers at 33.4x and a fair ratio of 31.9x. That premium raises a simple question: How comfortable are you paying extra for this RNAi story?
See what the numbers indicate about this price in more detail with our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about where Alnylam Pharmaceuticals really sits after the reset and legal questions, or already forming a strong view on the RNAi story? Act while sentiment is still recalibrating and review both sides of the ledger with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Alnylam Pharmaceuticals?
Do not stop with a single biotech reset story. Broader context helps you judge whether Alnylam Pharmaceuticals really earns a place alongside other high conviction positions in your portfolio.
Use the Simply Wall St Screener to pressure test your Alnylam Pharmaceuticals thesis against other opportunities before the next wave of sentiment shifts.
- Target quality first and filter out weaker balance sheets by reviewing companies in the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by lining up fresh candidates from the 28 high quality undervalued stocks.
- Dial down volatility risk by comparing Alnylam Pharmaceuticals with alternatives from the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com