


How Investors May Respond To American Financial Group Stock 10.2% Dividend Increase
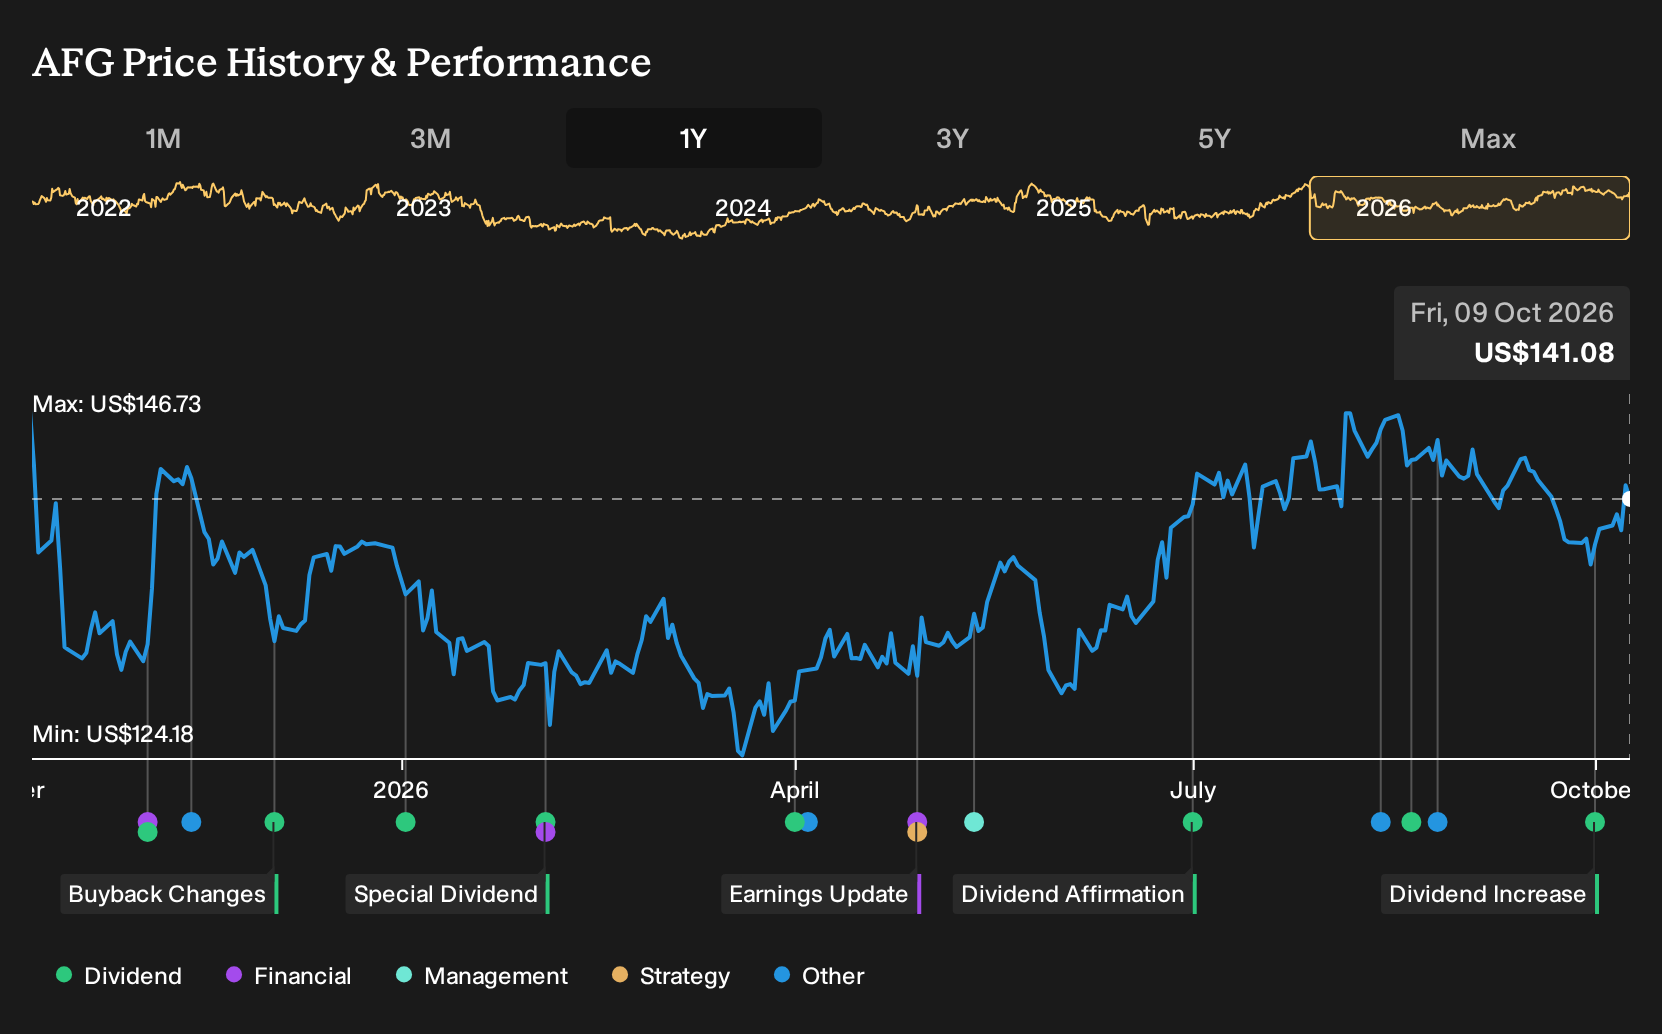
- American Financial Group declared a regular dividend of US$0.97 per share, paid on 23 October 2026 to holders of record on 15 October, reflecting a 10.2% increase over the annual rate in effect since late 2025.
- The higher regular dividend, alongside a payout ratio reported at 30% of earnings, signals management’s willingness to return a meaningful share of profits while still retaining capital for specialty P&C underwriting and investment income opportunities.
- We will look at how American Financial Group’s higher regular dividend affects the existing investment narrative built around underwriting and capital returns.
American Financial Group Investment Narrative Recap
To own American Financial Group, you need to be comfortable with a specialty P&C insurer that leans on underwriting discipline and investment income rather than fast premium expansion. The key short term swing factor is still underwriting quality in social inflation exposed lines and the behaviour of the alternatives portfolio. The higher regular dividend does not materially change that near term earnings profile.
The biggest risk remains pressure on loss severity and reserves in casualty and commercial auto if social inflation stays elevated, combined with volatile returns from alternative assets. The dividend increase, at a 30% payout ratio, slightly tightens the margin for error but still leaves meaningful earnings retained to support remediation efforts and reinvestment.
The most relevant piece of context for this dividend move is management’s wider capital return pattern. The business returned more than US$700m to shareholders in 2025 and around US$260m in Q1 2026 through regular and special dividends plus buybacks, alongside this 10.2% uplift in the ongoing dividend rate.
For you as a shareholder, that history of distributions helps frame expectations. The near term catalyst is execution in specialty casualty, commercial auto and AI driven efficiency, because those areas influence whether American Financial Group can keep funding dividends and repurchases while premium growth and book value trends have been slower than some peers.
What The Dividend Uplift Means Against Analyst Expectations For American Financial Group
Analysts expect American Financial Group to grow earnings from US$953.0 million today to US$1.0 billion by 2029, with revenue staying roughly flat but margins lifting from 11.8% to 13.1%. That backdrop matters for the higher regular dividend, because a rising profit base and a 30% payout ratio can help support larger cash distributions without relying on aggressive premium expansion. The current income stream you see from the stock therefore sits on analyst assumptions about steadier underwriting profitability, modest buyback driven share count reduction of 0.58% a year, and a gradual step up in investment income rather than on rapid top line growth.
Those same forecasts imply revenue of US$7.9 billion and earnings of US$1.0 billion in 2029, with the shares trading on a P/E of 15.1x if analyst price targets play out. That multiple sits above the 12.3x P/E attached to earnings today and above the 11.1x level cited for the wider US insurance sector. In that scenario, the market would be assigning American Financial Group a premium for consistent specialty underwriting, capital returns, and reinvestment of its fixed income book at the yields analysts reference. For investors who believe the underwriting and investment engines can support that type of earnings profile, the richer ongoing dividend may be viewed as one part of a broader return package that also includes specials and buybacks.
American Financial Group's narrative projects US$7.9 billion revenue and US$1.0 billion earnings by 2029. This implies fairly flat yearly revenue growth and about a US$47.0 million earnings increase from current earnings of US$953.0 million.
Uncover why American Financial Group's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Across 3 fair value views from the Simply Wall St Community, estimates stretch from US$122 to about US$299 per share, so retail opinions on American Financial Group are wide apart. When you set those against live risks around social inflation and alternative asset volatility, you get a reminder to test several viewpoints before leaning on any single dividend story.
Explore 2 other American Financial Group fair value estimates, including one that suggests as much as 14% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your American Financial Group research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Financial Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Financial Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Financial Group?
Once you have a view on American Financial Group, it can help to line it up against other opportunities with different income profiles, balance sheet strength, and risk levels. The Simply Wall St Screener lets you quickly filter for stocks that fit the way you like to invest, so you can build a watchlist that matches your preferred mix of quality, yield, and resilience.
- If you want potential income and steadier fundamentals, consider scanning a curated 8 dividend fortresses that pair higher yields with stronger balance sheets.
- If value is your focus and you prefer paying less for each dollar of earnings or cash flow, run through the 28 high quality undervalued stocks that meet tighter quality and pricing filters.
- If capital preservation ranks high on your checklist, start with a 31 resilient stocks with low risk scores that screen well on the Simply Wall St risk scoring framework.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com