


3 British Value Stocks For October 2026
With US Treasury yields sitting near multi decade highs and investors questioning how much risk to take, healthy cash flow has become a key comfort factor. For value hunters in UK equities, that creates an opening. When solid cash generators trade below independent estimates of fair value, the gap can be compelling. This article walks through three such British stocks that screen as attractively priced on their cash flows.
The three stocks covered next are only a sample, as the full cash flow screen highlights 23 more UK companies with similarly interesting stories that are not unpacked in this article.
To go straight to the full list of undervalued cash generators and start to identify which ideas best fit your portfolio, head into the Undervalued Stocks Based On Cash Flows screener.
Shell (LSE:SHEL)
Shell is a global energy and petrochemicals group whose integrated oil and gas operations generate the cash flows that anchor its place in this undervalued cash flow screener.
Shell runs a broad energy platform spanning Integrated Gas, Upstream production, marketing, chemicals, and renewables. The biggest revenue lines come from Marketing at about $135b and Chemicals and Products at roughly $132b, with Integrated Gas and Upstream together adding close to $93b. Renewables and Energy Solutions contribute around $42b, while the group’s market value sits near £217.1b.
With an LNG portfolio exceeding 60 million tons and extensive trading capabilities, Shell is positioned to benefit from volatility in the global gas market.
How resilient those cash flows appear if one unseen pressure on pricing and margins shifts will matter a lot for investors.
If that pressure point on pricing is what you are weighing, read the full narrative for Shell to see how Shell’s cash engine could still surprise on resilience.
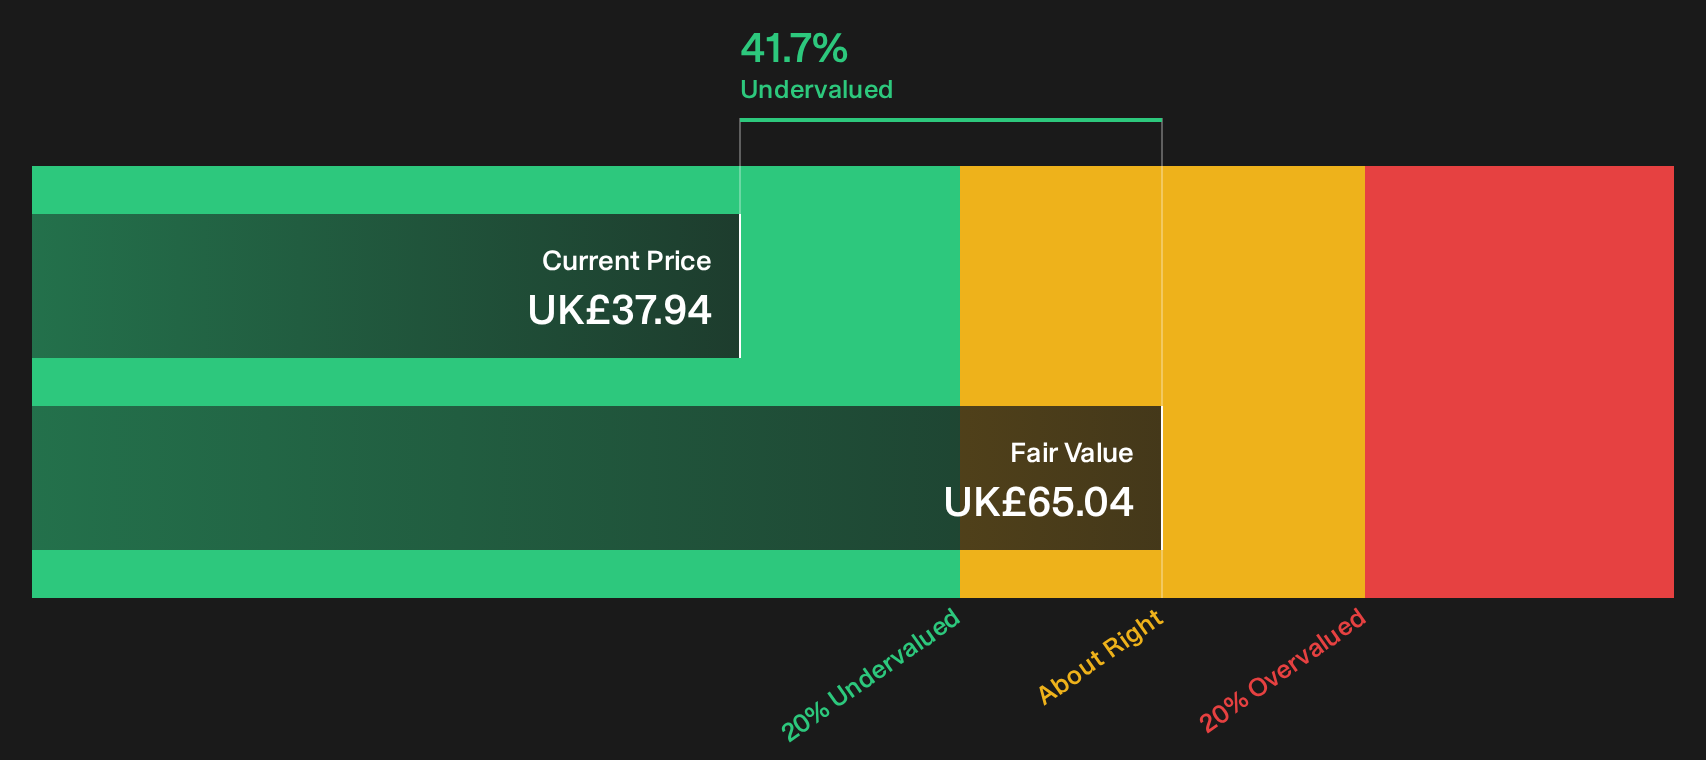
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings is an alternative asset manager built around real assets and private equity, with its renewable infrastructure funds and energy management projects providing the long term cash flows that tie it directly to this undervalued cash flow theme.
Real Assets generated about £114.8 million of revenue, with Private Equity adding roughly £50.1 million, giving Foresight a meaningful fee base from long term contracts and investment vehicles. The group is listed in London with a market value of around £491 million.
For investors focused on cash flow visibility, Foresight’s combination of fee based infrastructure income and more cyclical private equity and venture capital exposure creates an interesting blend that can require patience if the market continues to overlook those underlying cash streams.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is expected to support compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
This raises the question of what happens to that story if one assumption about how quickly fee income scales turns out to be too optimistic or too cautious.
If that pacing risk is on your mind, read the full narrative for Foresight Group Holdings to see how Foresight Group Holdings could turn slower fee momentum into accelerating compounding potential.
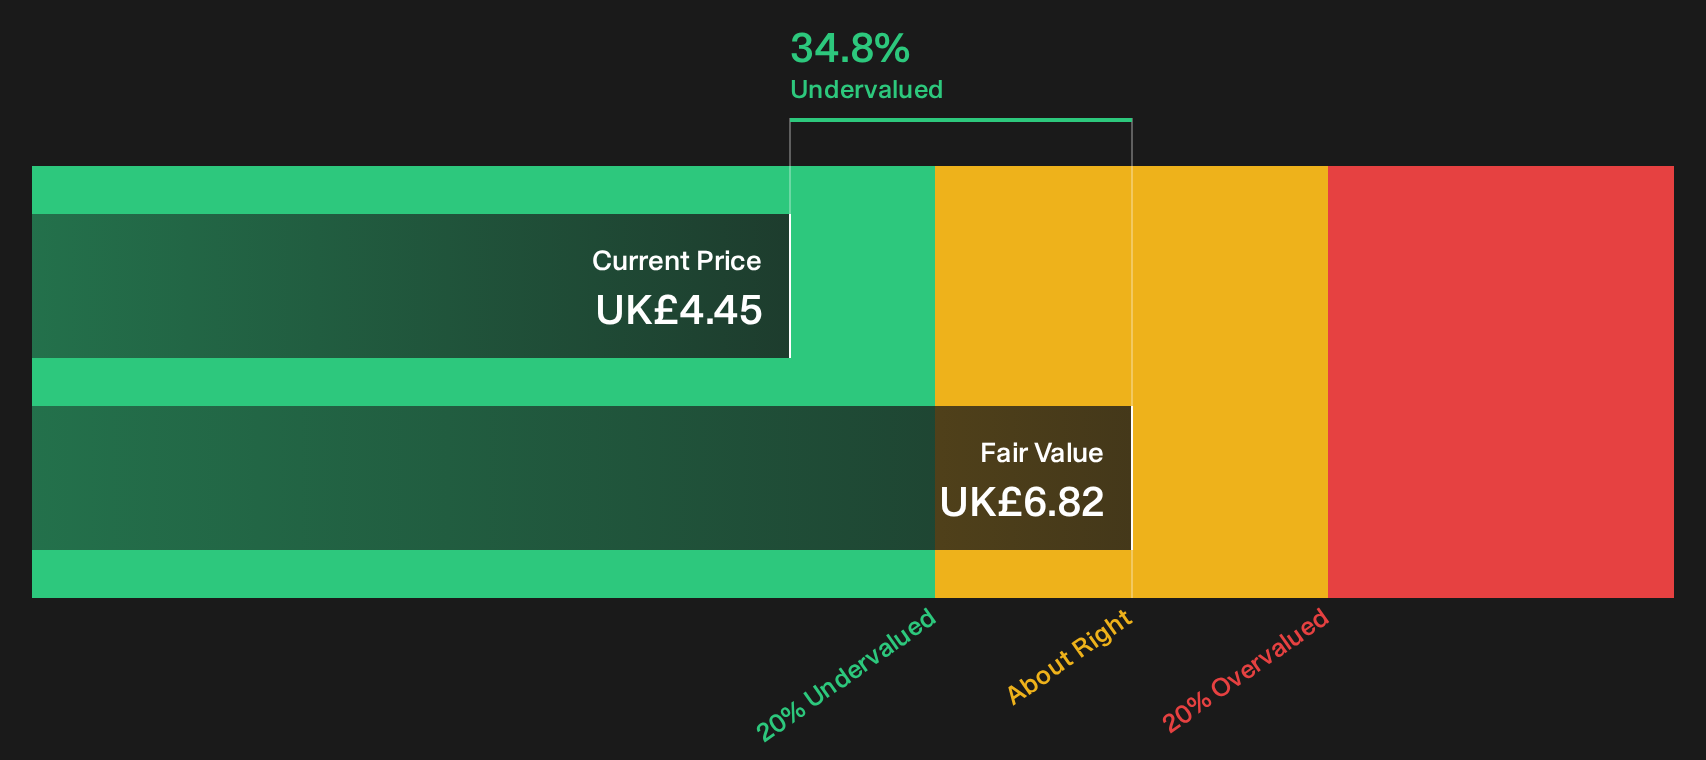
BAE Systems (LSE:BA.)
BAE Systems is a global defense and aerospace group whose Platforms & Services and Electronic Systems units anchor its cash flow appeal, with these long contract cycles supporting its place in an undervalued cash flow screen alongside a broader mix of air, maritime, and cyber activities.
Across its £52.6b market value, BAE Systems generates revenue mainly from Electronic Systems at about £7.8b, Air at roughly £7.7b, Maritime at around £6.7b, and Platforms & Services at close to £5.3b, with smaller contributions from Cyber & Intelligence.
For this screener, BAE Systems matters because those multi year defense programs line up closely with the kind of recurring cash generation investors often look for when weighing discounted cash flow gaps.
"The company's order backlog has surged to £75 billion, with a pipeline of new opportunities partly fueled by higher defense spending commitments across NATO, the US, UK, Europe, and Indo-Pacific, providing visibility on future revenues and supporting topline growth over multiple years."
What could shift the story is how one pressure on future defense program timing plays out across those tightly modeled cash flow assumptions.
If that timing risk is what you are weighing, read the full narrative for BAE Systems to understand how BAE Systems’ backlog, cash flows, and program cycles could be decoupling from headline defense budgets.

Seeking Fresh Alternatives For Your Curiosity?
Markets move fast. Breakout stories gain momentum, quiet compounders fly under the radar for now, and mispriced cash engines get caught before the crowd. Scan fresh ideas and consider your next steps with care.
- Explore income opportunities that aim to keep paying while others watch yields drop. Sort through a curated pack of potential income stalwarts in the 1 dividend fortresses.
- Look for resilient operators where balance sheets and fundamentals still appear solid while it matters. Work through the curated list of solid balance sheet and fundamentals (9 results).
- Review early movers in AI where profits already exist and cash is not just burning. Examine hand picked contenders inside the 39 profitable AI stocks that aren't just burning cash.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com