


Innovative Industrial Properties (IIPR) Stock Looks Like A Bargain On Earnings
Innovative Industrial Properties has seen a sharp reset in its share price over the past few years, which now puts the focus squarely on what investors are paying for its earnings. With the stock trading around US$51.83, the key issue is whether that current tag lines up with what the business actually earns.
- Over the past 5 years the share price has fallen 65.1%, which puts more pressure on the earnings story to explain where value might now sit.
- The recent decision to issue 2,000,000 shares of 9.25% Series B preferred stock for US$50m may support growth plans but also sets a clearer price for new capital that existing common shareholders need to weigh against future earnings power.
- There is a second opinion on Innovative Industrial Properties worth weighing. See what analysts think Innovative Industrial Properties's shares could be worth.
The issue now is whether the current share price can be justified by the earnings the company is producing today.
If you are weighing whether Innovative Industrial Properties at around US$51.83 makes sense on its earnings, it can help to line it up against other 28 high quality undervalued stocks.
Is Innovative Industrial Properties a Bargain on Earnings?
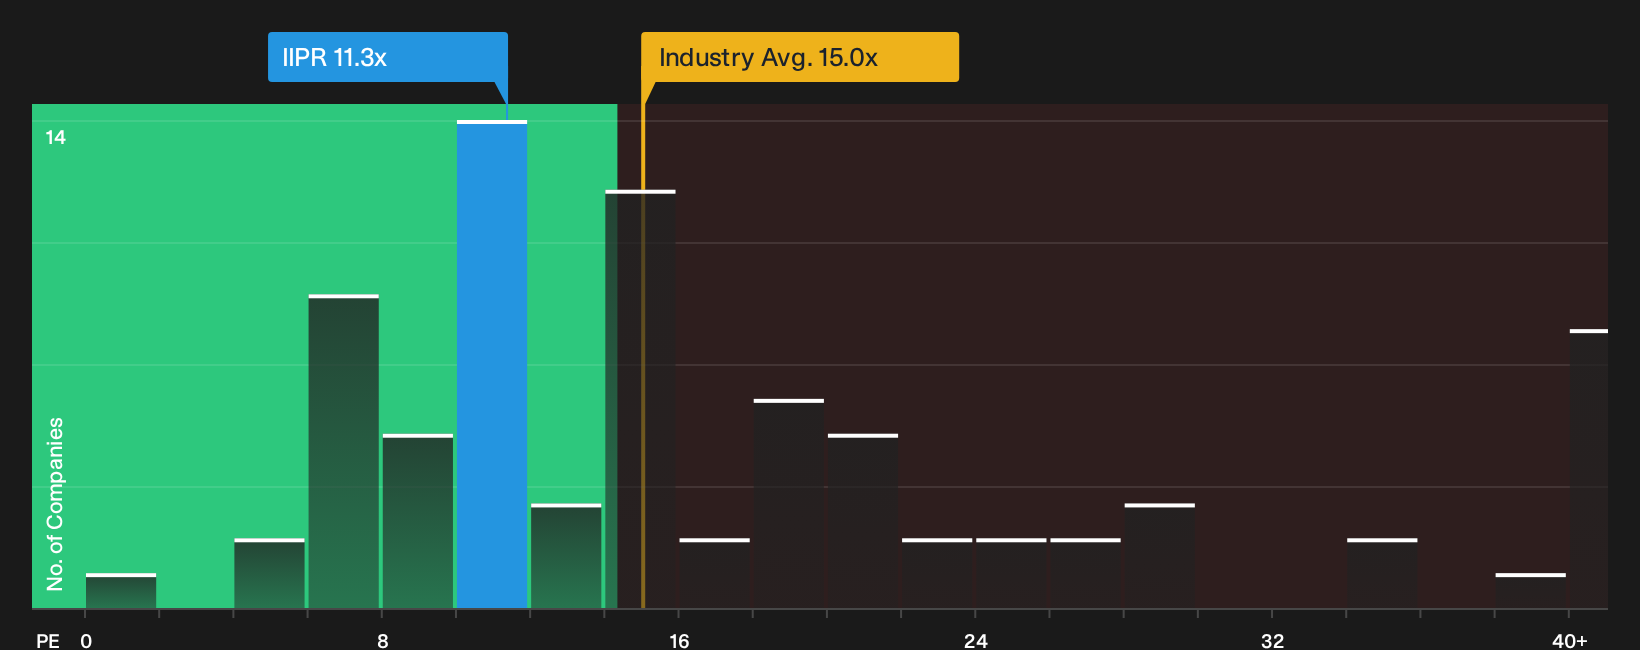
For a real estate investment trust like Innovative Industrial Properties, the P/E ratio gives a clear sense of what investors pay for each dollar of reported profit. At roughly 11.3x earnings, the stock changes hands at a lower multiple than the Industrial REITs group, which averages about 15.0x. It also trades at a steep discount to the broader peer set around 29.0x, so the market is assigning a much lower price tag to each unit of earnings here than for many comparable listings.
Because the P/E that might be expected for Innovative Industrial Properties, based on its business profile and risk mix, screens higher than the current 11.3x level, the shares appear undervalued on this framework. The recent decision to issue 9.25% Series B preferred stock sets a clear cost for new capital. Even with that in the picture, the P/E still sits well below both industry and peer benchmarks, which highlights a valuation gap that investors need to assess. Explore the numbers behind Innovative Industrial Properties's P/E valuation.
The Innovative Industrial Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this earnings puzzle leaves off for Innovative Industrial Properties by spelling out which future paths for growth, margins and cash generation would need to play out for the current valuation to look high or low. Each narrative ties a specific fair value estimate to a clear storyline about potential catalysts and key risks, so you can watch over time which version of the business case lines up with reality on the Community page.
One of the top community narratives on Innovative Industrial Properties: 16% undervalued
"Regulatory changes and access to cheaper financing for cannabis operators threaten demand for IIPR's core business model and future revenue growth..."
Discover why this Narrative puts Innovative Industrial Properties at 16% undervalued.
The valuation for Innovative Industrial Properties still leaves one crucial issue hanging
Price and earnings only tell part of the story for Innovative Industrial Properties, since separate checks have flagged potential pressure points that investors may want to weigh carefully before taking the next step. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com