


Could SpaceX Spectrum Deal Create A New Tower Tenant For SBA Communications Stock
- SpaceX previously agreed to acquire nationwide low band spectrum from Grain Management for about US$8b in cash, which raises the prospect that it could use existing wireless towers as part of a future ground network.
- This potential new tower tenancy from SpaceX highlights that incremental demand for low band infrastructure capacity may support SBA Communications' leasing opportunity set across its portfolio.
- We will look at how SBA Communications' investment narrative intersects with SpaceX's potential role as a new macro tower tenant.
Scan how SBA Communications compares with other tower and wireless infrastructure plays by reviewing our hand picked 43 power grid technology and infrastructure stocks aligned with similar long term connectivity themes.
SBA Communications Investment Narrative Recap
SBA Communications appeals to investors who want exposure to long term wireless infrastructure leasing, with much of the thesis hanging on steady U.S. densification, international tower usage and disciplined capital recycling. The key near term swing factor is whether new leasing, including potential satellite related demand, offsets known churn and higher interest costs as low coupon debt is refinanced.
Satellite networks such as SpaceX raise two questions for SBA Communications. On the upside, additional macro tower tenants could support lease up if ground networks are pursued. On the downside, wider satellite coverage could limit long term tower demand in some areas. The refinancing cycle and churn in Brazil still look like the most immediate operational risks.
With no fresh company specific announcements tied directly to the SpaceX spectrum deal, the most relevant existing catalyst is SBA Communications guiding to about US$35 million of U.S. lease up in both 2025 and 2026, with stated long term expectations of roughly 4.5% to 5% annual U.S. tower revenue growth. That guidance sets a reference point for how incremental satellite related demand might matter.
If SpaceX or other direct to device players choose to lean on terrestrial towers, that guidance range could frame upside to leasing expectations. If they build around towers or slow carrier spending, investors may end up focusing more on the international expansion in Central America and Tanzania, and on how well SBA Communications manages higher cash interest costs through 2027.
SBA Communications' narrative projects US$3.1b revenue and US$952.1m earnings by 2029. This assumes 3.0% yearly revenue growth and an earnings decline of about US$38.6m from current earnings of US$990.7m.
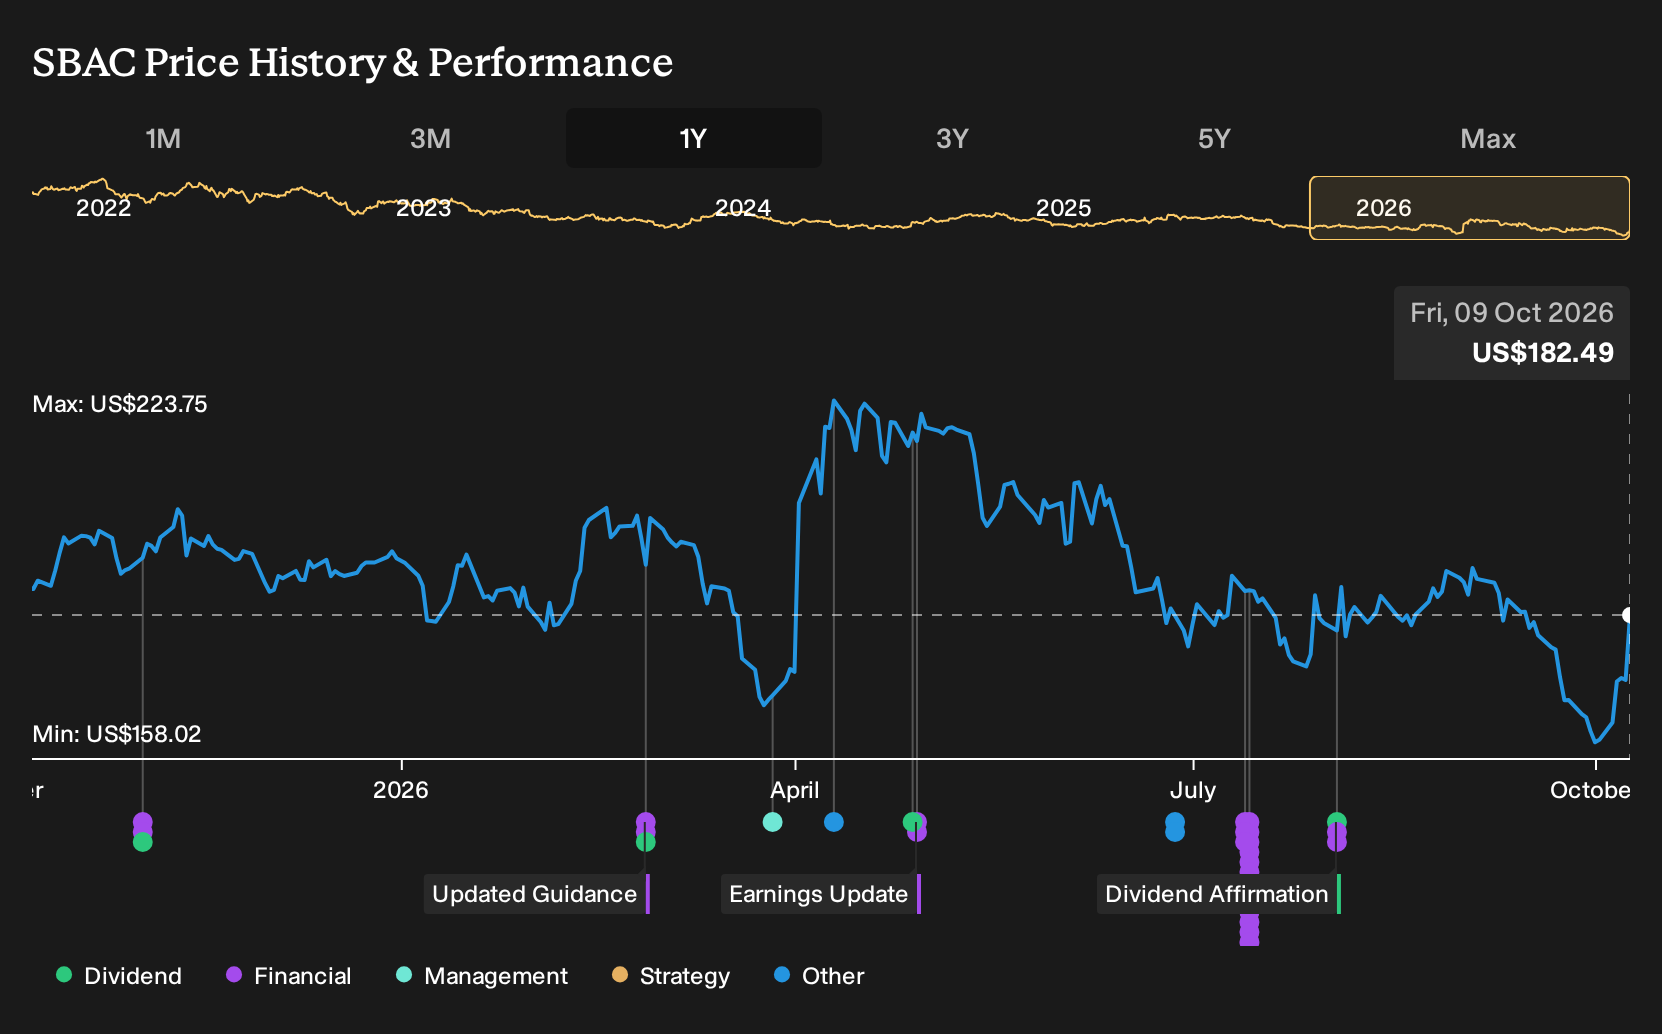
Uncover why SBA Communications' fair value indicates a 24% potential upside to its current price that could narrow more quickly than investors expect.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between about US$226 and US$261 per share for SBA Communications, so you are not looking at a single anchor. Those estimates pre date the SpaceX spectrum move, which could reshape tower demand, interest in satellite alternatives and your expectations for long run leasing power.
Explore another SBA Communications fair value estimate, including one that suggests up to 43% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SBA Communications research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SBA Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SBA Communications' overall financial health at a glance.
Looking for more investment ideas beyond SBA Communications?
If the SBA Communications story has you thinking about where recurring cash flows and balance sheet strength intersect, it can help to scan a wider field of potential opportunities using the Simply Wall St Screener.
- For investors who want income that might hold up through different cycles, run your eye over a curated set of high yield candidates with the 8 dividend fortresses.
- If capital preservation and steadier profiles matter most to you, narrow the field to companies with relatively low overall risk scores using the 31 resilient stocks with low risk scores.
- Readers hunting for quality that is not yet widely followed can start with a focused pool of under the radar ideas through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com