


Is Cinemark Holdings (CNK) A Bargain After Its SCREENX Expansion Push?
Cinemark Holdings (CNK) just pushed further into premium moviegoing by signing a deal with CJ 4DPLEX to install 20 additional SCREENX auditoriums across its U.S. and Latin American theater network.
Cinemark Holdings has been on a strong run, with the share price delivering a 25.34% 90 day return and a 54.70% year to date share price return, while total shareholder return over three and five years sits at 118.65% and 84.20% respectively. This suggests that recent premium format expansion and concessions experiments are feeding into growing momentum around the stock, despite a small 1 day pullback of 1.01%.
Scan how Cinemark Holdings compares with other cinema and entertainment chains on concession strength, premium formats, and recent share price momentum by reviewing our hand picked 20 high quality undiscovered gems in this space.
Cinemark Holdings now trades close to some analyst targets yet screens just below a simple intrinsic value estimate. Is the recent run already pricing in the SCREENX build out and popcorn delivery push, or not quite?
Most Popular Narrative: 9% Undervalued
Cinemark Holdings closed at $36.40, compared with a widely followed fair value estimate of about $39.82. This frames the SCREENX move within a broader premium and loyalty story for the chain.
Continued expansion of premium formats such as XD, IMAX, ScreenX and D BOX, including newly announced ScreenX locations, can lift average ticket prices and concession spend per guest and support both revenue and net margin strength over time.
See why 9 investors see Cinemark Holdings as 9% undervalued.
Result: Fair Value of $39.82 (UNDERVALUED)
Still, this Cinemark Holdings story can fray if recent record box office periods prove temporary or if premium upgrades and higher fixed costs squeeze margins and cash generation.
Find out about the key risks to this Cinemark Holdings narrative.
Another Take On Cinemark Holdings Valuation
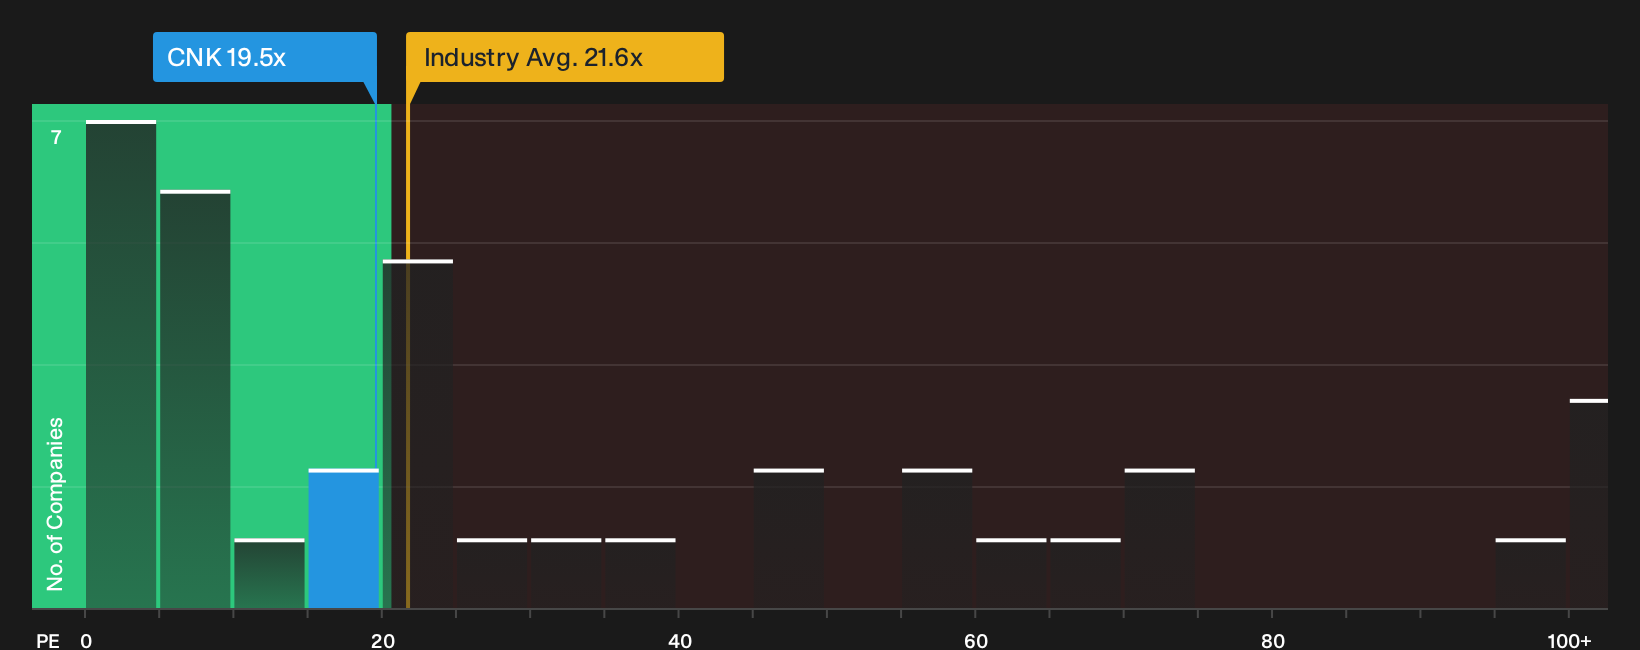
The earlier fair value story leaned on analyst earnings forecasts and price targets, which framed Cinemark Holdings as modestly undervalued. A different lens looks at the current P/E of 19.5x, compared with a fair ratio of 17x, the US Entertainment average of 21.7x and a peer average of 39.7x.
This mix leaves you with a split verdict. The stock appears expensive versus its own fair ratio, yet cheaper than the sector and direct peers. That gap can point to upside if sentiment shifts closer to peers, or to downside if pricing moves toward the fair ratio. Which crowd do you think the market will follow next?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Cinemark Holdings story so far. Consider the situation while sentiment remains divided and evaluate both the bullish and bearish angles in the 2 key rewards and 1 important warning sign
Looking for more ideas beyond Cinemark Holdings?
Do not stop with one ticker. Broaden your watchlist with a few targeted filters that can surface very different types of opportunities in seconds.
- Target potential mispricing by scanning a curated pool of quality stocks that still flag as undervalued through the 28 high quality undervalued stocks.
- Prioritize resilience by reviewing a 31 resilient stocks with low risk scores that filters for businesses with steadier risk profiles and fewer financial red flags.
- Hunt for future standouts early by using a focused 20 high quality undiscovered gems that spots under-followed companies with stronger fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com