


Magna International And 2 Canadian Dividend Stocks To Own
Higher US Treasury yields near 24 year highs have pushed up borrowing costs and made income harder to find without taking on a lot of risk. For Canadian dividend investors, that puts a spotlight on companies paying reliable cash every quarter. This article breaks down three high yield Canadian dividend stocks from a focused screener that targets payouts above 3% that appear well covered, growing and stable.
The three stocks highlighted below are just a sample from this idea, with the full screen surfacing 20 more companies that show similarly compelling income stories that are not covered here. To identify and analyze those additional dividend candidates with yields above 3%, head straight into the Dividend Powerhouses (3%+ Yield) screener.
Magna International (TSX:MG)
Magna International is a global auto parts group that supplies everything from body structures and seating to complete vehicles. Its Power & Vision and Complete Vehicles divisions use electrification and ADAS programs as important cash engines for a dividend-focused income story.
Its largest revenue streams come from Body Exteriors & Structures at about US$16.9b and Power & Vision at roughly US$15.7b, followed by Seating Systems near US$5.9b and Complete Vehicles around US$4.7b, while the stock carries a market value of roughly CA$24.1b.
For dividend investors, Magna International ties a 3%+ yield to vehicle electrification and advanced safety content. Together, these can help underpin recurring cash needed to keep quarterly payouts on a solid footing even as auto cycles shift.
"Magna International is focusing on operational excellence and restructuring actions, which are expected to result in meaningful margin expansion over the next two years."
The real swing factor is how one pressure on future cash generation ultimately resolves and feeds back into dividend headroom.
That swing factor is exactly where income investors should focus, and the full narrative for Magna International lays out how those pressures, opportunities and capital returns could be decoupling from old auto cycles.

Freehold Royalties (TSX:FRU)
Freehold Royalties is built around royalty income on oil and gas production. This means its cash flow, and therefore its dividend, comes in without the heavy capital spending that traditional producers carry.
Freehold Royalties acquires and manages royalty interests on crude oil, natural gas, natural gas liquids and potash, collecting about CA$322 million from oil and gas exploration and production royalties. The business, worth roughly CA$2.8 billion on the market, spans both Canada and the United States.
"The company does not bear any of the costs of drilling, completion, operation, or environmental rehabilitation on its land, receiving a "top-line" share of each barrel of oil or gas produced. US revenue, which was zero in 2020, reached 53% of total revenue in the first nine months of 2025, becoming the company's main revenue source."
For income investors, what happens to the cushion between those royalty inflows and the rich dividend payout will be the quiet swing factor.
That cushion is the real story, and the full narrative for Freehold Royalties unpacks how Freehold Royalties' royalty mix, US exposure and payout policy could be quietly reshaping its income profile.

North West (TSX:NWC)
North West runs grocery, general merchandise, fuel and discount stores serving remote parts of Canada, Alaska and island markets, where everyday shopping habits help support a 3%+ dividend yield. It generates about CA$1.5b of sales in Canada and CA$1.1b internationally, and is valued at roughly CA$2.6b.
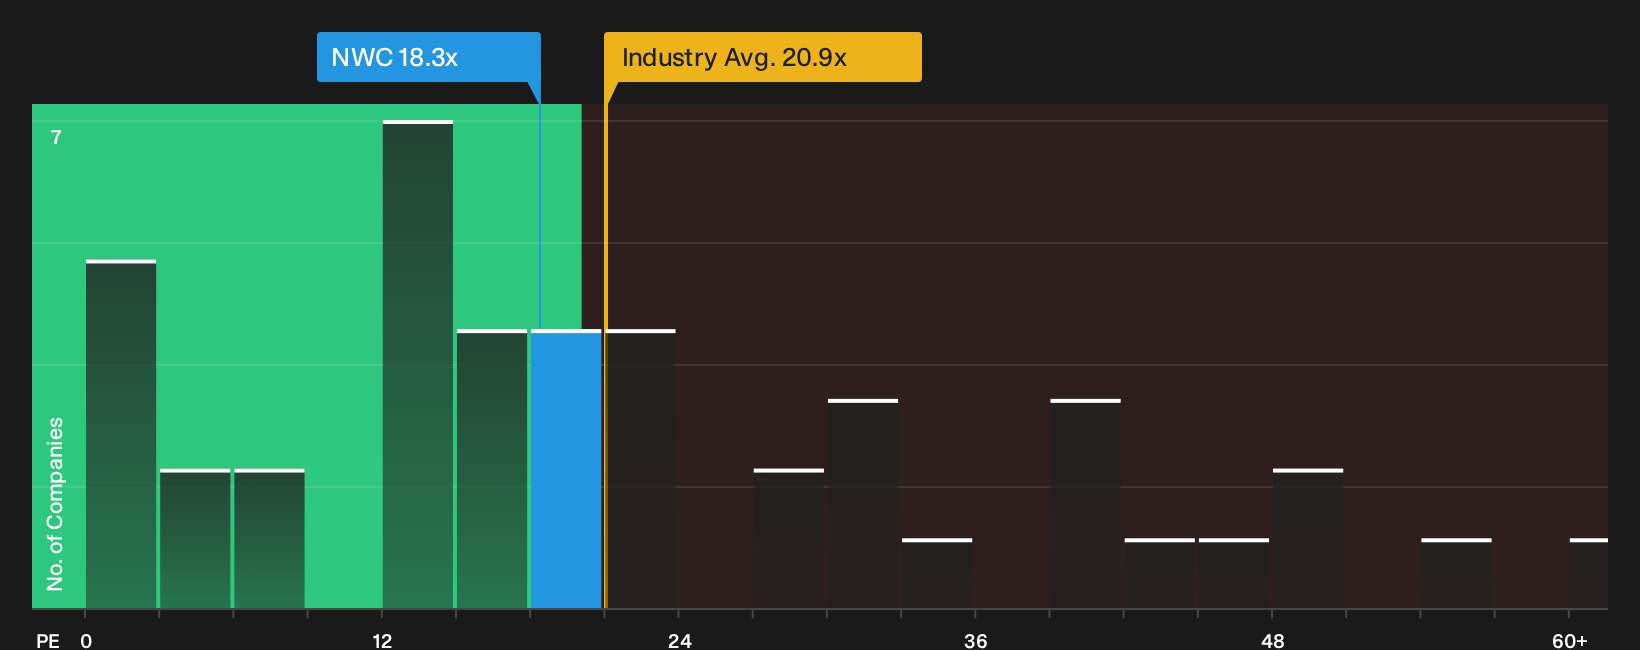
For dividend seekers, North West combines a 3.06% yield with high-quality earnings and a P/E of 18.3x that is cheaper than many retail peers. That combination of covered income and relative value rests heavily on how one quiet pressure shapes future cash generation from those far flung stores.
That quiet pressure is exactly where the story could shift, and the analysis report for North West shows how North West's cash generation and dividend headroom might be evolving.
Curious About Higher Yield Alternatives
Fresh ideas move first. Markets reward the investors who spot quiet momentum, solid balance sheets and durable cash flows before the crowd. Use these curated shortlists and get in early.
- Target steady income potential from high quality payers by running the 3 dividend fortresses while it is still flying under the radar for many income hunters.
- Hunt for resilient operators with room to compound by screening the 9 high quality undervalued stocks before attention and capital crowd into the same tickers.
- Position ahead of long term infrastructure themes shaping electricity demand with the 43 power grid technology and infrastructure stocks so you are not caught chasing after prices have moved.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com