


Will Pune Digital Centre Change KONE Stock's Narrative
- KONE Oyj recently opened India’s first Digital Experience Centre in Pune, giving customers a hands-on view of its AI, data and connectivity driven elevator and escalator solutions.
- The new Pune hub turns KONE Oyj’s digital capabilities into a live showroom, which can support higher value service conversations with large building owners.
- This article examines how KONE Oyj's investment narrative connects to the Pune Digital Experience Centre and its expanding digital services.
Scan beyond KONE Oyj and this Pune launch by sizing up other elevator and smart-building beneficiaries in our hand-picked list of 91 robotics and automation stocks.
KONE Oyj Investment Narrative Recap
For a shareholder in KONE Oyj, a central belief is that modernization, services and digital tools keep gaining weight in the mix, so earnings become more recurring and less tied to volatile new construction. The Pune Digital Experience Centre fits neatly into this picture as a way to showcase AI driven maintenance and connected solutions to large customers. On its own, however, it is not a major short term earnings catalyst.
The nearer term swing factors still look more basic. Execution on margin recovery after inflation and logistics pressures, together with disciplined pricing in weaker end markets such as Chinese new builds, matters more today. On the risk side, the planned TK Elevator combination and the extra leverage it brings remain a much bigger swing factor than one digital showroom.
With no fresh company announcement tied directly to the Pune opening, the most relevant context is KONE Oyj's wider push into connected maintenance. Management already reports 44% of the maintenance base as connected and uses dynamic maintenance planning on about two thirds of units. The Pune centre gives buyers a way to see those tools live on the ground in a key growth geography.
This is relevant when considering the catalysts that analysts highlight. Higher margin service work, roughly 15% growth in modernization sales in recent quarters and over 20% growth in impact revenue that helps customers cut energy use all rely on credible digital capabilities. The more convincingly KONE Oyj can show that these offerings work at scale, the more support it may give to the medium term earnings mix story.
KONE Oyj's current analyst narrative points to revenues of €13.7 billion and earnings of €1.5 billion by 2029, based on forecast revenue growth of 6.3% per year and an earnings increase of about €556.0 million from current earnings of €944.0 million.
Discover how KONE Oyj's fair value points to a 13% potential upside to its current price before that gap closes.
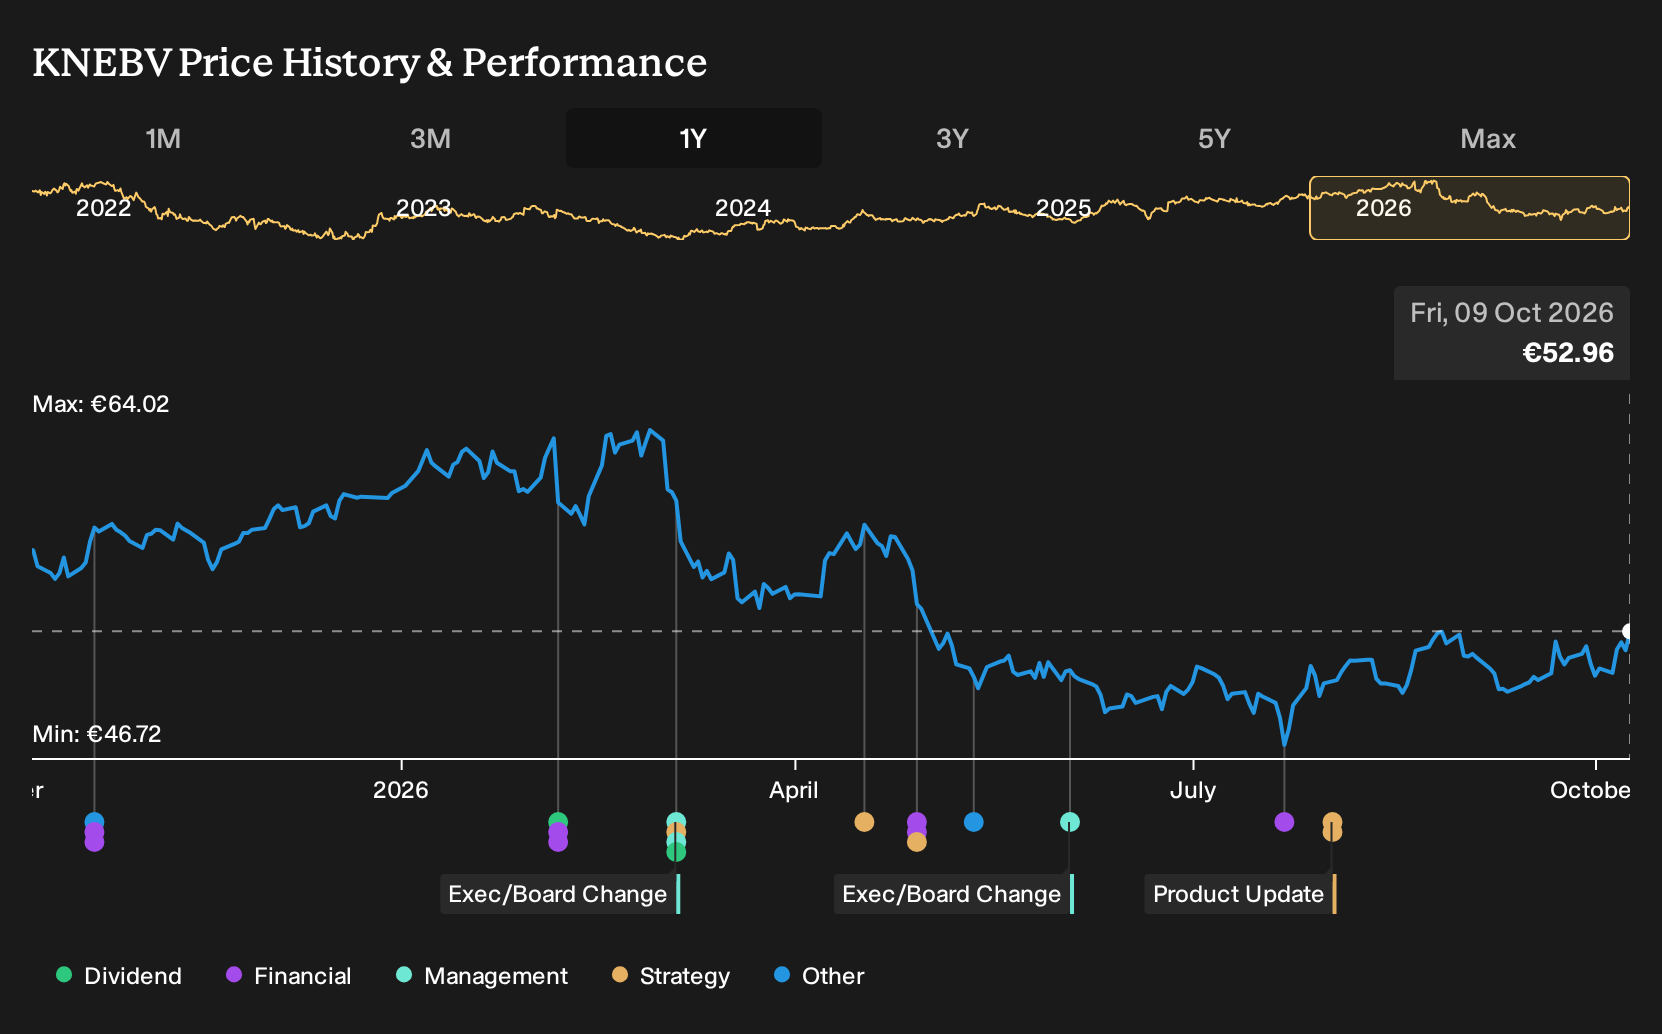
Exploring Other Perspectives
Some of the most optimistic analysts focus on the TK Elevator deal as the real swing factor for KONE Oyj, rather than a single digital centre in Pune. Before this news, they were sketching out revenues of about €14.3b and earnings near €1.6b by 2029. You can compare that upbeat view with your own and decide whether the Pune launch could nudge those expectations higher or lower.
Explore 4 other KONE Oyj fair value estimates, including one that suggests the potential for up to 50% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your KONE Oyj research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for KONE Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KONE Oyj's overall financial health at a glance.
Looking for more investment ideas beyond KONE Oyj?
Once the KONE Oyj story is mapped out, it helps to line it up against other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener can narrow a huge market into a small, workable shortlist that actually fits what you are trying to do with your portfolio.
- If you want stability to anchor your holdings, check out a list of solid balance sheet and fundamentals (204 results) that pairs cleaner balance sheets with solid fundamentals.
- For investors who put capital protection first, scan a 222 resilient stocks with low risk scores that highlights companies with lower risk scores based on our data.
- If you prefer to hunt for underappreciated opportunities, sort through a 618 high quality undiscovered gems that focuses on smaller, high quality businesses the market might be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com