


Nitto Kogyo (TSE:6651) Climbed, So What Is Behind The Fresh Attention?
Nitto Kogyo (TSE:6651) has called a board meeting for 28 September 2026 to review a Notice Regarding Price Revisions, putting its pricing playbook and potential effects on revenue and profitability under closer investor scrutiny.
Nitto Kogyo’s ¥4,490 share price comes after a 2.39% 1 day share price return and a 4.06% 30 day share price return, while the 90 day share price return has eased 1.86%. The 1 year total shareholder return of 32.11% and 5 year total shareholder return of 231.53% indicate momentum that long term holders will be weighing carefully against any pricing shifts discussed at the upcoming board meeting.
Scan how Nitto Kogyo’s pricing review compares with peers by lining it up against list of solid balance sheet and fundamentals (23 results), which could better handle margin pressure from future price moves.
Nitto Kogyo has already priced in a strong run, and the board is about to debate pricing that could reshape margins. Do you pay up now or wait for a clearer entry after the valuation workup?
Preferred P/E of 14.1x for Nitto Kogyo: Is it justified?
Nitto Kogyo closed at ¥4,490, and on a P/E of 14.1x the market is pricing its earnings slightly higher than both the internal fair ratio of 12.6x and the wider JP Electrical sector at 14x.
The P/E ratio compares what investors pay per share to the earnings that Nitto Kogyo generates per share. For a capital goods manufacturer producing electrical and mechanical equipment, this lens helps you see how much the market is willing to pay today for each unit of profit across a fairly cyclical industry.
Earnings growth of 30% over the past year, ahead of the Electrical industry at 23.4%, and 13% per year over five years shows that recent profitability has been strong relative to peers. At the same time, forecasts in the article point to earnings rising around 5% per year and revenue at 5.2% per year, which is slower than both the broader JP market and the 20% high growth bar, so the premium to the firm’s own estimated fair P/E of 12.6x suggests expectations already build in a significant portion of that outlook.
Compared with the sector, Nitto Kogyo screens as marginally expensive on a P/E basis, sitting at 14.1x versus the JP Electrical average of 14x. Against the estimated fair P/E of 12.6x, the current multiple appears meaningfully richer, which is a level the market could move toward if enthusiasm about recent earnings momentum cools.
Explore the SWS fair ratio for Nitto Kogyo.
Result: Price-to-Earnings of 14.1x (OVERVALUED).
Still, any shift in Nitto Kogyo’s pricing could squeeze demand, and cost inflation or weaker order volumes might pull that 14.1x P/E back toward earth.
Find out about the key risks to this Nitto Kogyo narrative.
Another View On Nitto Kogyo’s Value
The earlier P/E work paints Nitto Kogyo as slightly expensive, and the SWS DCF model points in the same direction on a different axis. At ¥4,490 against an estimated future cash flow value of ¥3,505.7, the stock screens as overvalued on cash flows as well. Which signal do you trust more when considering that upcoming board decision?
Look into how the SWS DCF model arrives at its fair value.
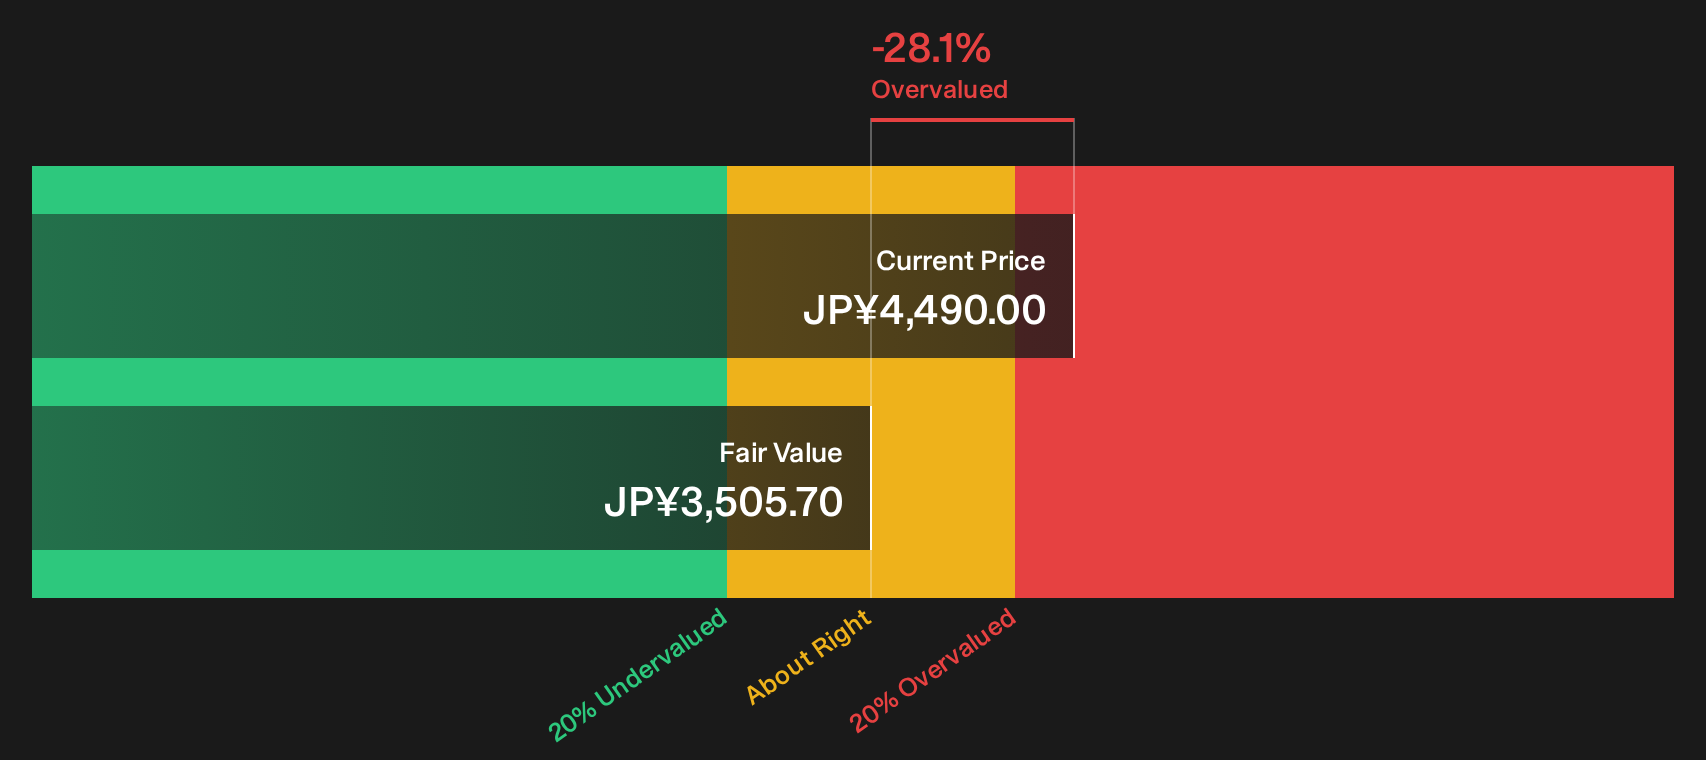
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nitto Kogyo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Opinions on Nitto Kogyo are mixed after all that. Take action while the pricing review is still recent and test the data yourself, starting with the 2 key rewards and 1 important warning sign.
Looking for more Nitto Kogyo style investment ideas?
If you only stop at Nitto Kogyo, you risk missing other opportunities that match your goals, risk tolerance, and income needs across the rest of your portfolio.
- Target future upside with quality at a reasonable entry by scanning our universe for 12 high quality undervalued stocks that pair solid fundamentals with attractive pricing.
- Secure potential income streams by focusing on companies built to keep paying investors through cycles using our screen of 28 dividend fortresses.
- Protect your downside by filtering for resilient businesses that can better handle shocks through the 23 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com