


BlackLine (BL) Faces A Fresh Valuation Test Following Its Industry Focused Product Push
BlackLine (BL) just pushed its financial operations platform deeper into industry-specific territory by rolling out preconfigured transformation blueprints, sector-focused templates, and PCI DSS compliant workflows aimed at payment-heavy customers in banking, insurance, energy, and life sciences.
BlackLine’s latest product push lands after a choppy run for the stock, with a 7 day share price return of 8.61% and a 1 day gain of 1.78% hinting at near term momentum, set against a year to date share price decline of 44.64% and a 5 year total shareholder return that has fallen 75.87%. This keeps recent enthusiasm firmly in the context of a longer period where investors have reassessed both growth potential and risk.
Scan how BlackLine’s push into industry-specific automation compares with peers by sizing up the hand-picked group of list of solid balance sheet and fundamentals (25 results).
BlackLine now couples sector specific workflows with a long track record in finance automation. The more important question is not whether the product set stacks up. It is whether the current share price does.
Most Popular Narrative: 22% Undervalued
BlackLine closed at $29.77 against a widely followed fair value of $38.10, so the key question is whether the business momentum is strong enough to close that gap or if the discount reflects deeper concerns.
Growing adoption of the Studio360 cloud platform, Verity agents, and the Finance Control Console positions BlackLine as a control and governance layer for AI driven financial operations. This can influence long term revenue growth and support margins as usage deepens across complex customers.
See why 2 investors see BlackLine as 22% undervalued.
Result: Fair Value of $38.10 (UNDERVALUED)
Still, the BlackLine narrative only holds if customer churn in the lower mid market eases and longer enterprise sales cycles no longer push large deals into later quarters.
Find out about the key risks to this BlackLine narrative.
Another View: What BlackLine’s P/E Is Telling You
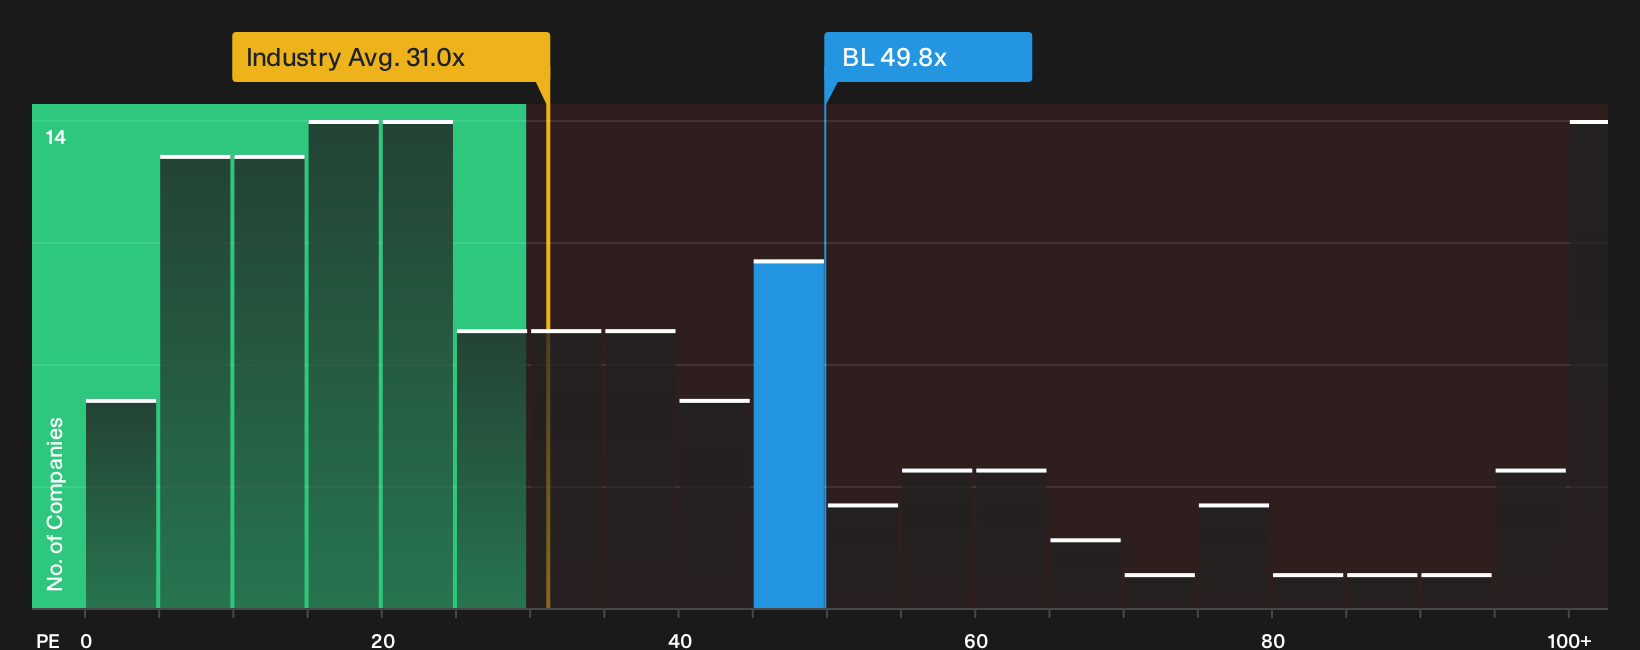
The fair value work points to upside, yet the market is still paying a rich P/E for BlackLine at 49.8x. That is higher than both the US Software sector on 30.9x and the peer average on 38.7x, and even slightly above the 48.8x fair ratio. For investors, that kind of premium can mean less room for error if growth or margins fall short.
Before leaning on any single earnings multiple, it helps to see how the current price stacks up against cash flow expectations and alternative ways of thinking about value. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around BlackLine is split, which is exactly why it helps to move fast, look through the data yourself, and stress test the bullish and cautious arguments side by side using the 2 key rewards and 2 important warning signs.
Looking for more BlackLine investment ideas?
If BlackLine has your attention, do not stop here. Use the same disciplined lens across other opportunities so you are not relying on a single story.
- Target quality at a discount by scanning companies that screen well on value and fundamentals with the 28 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with strong financial footing using the 31 resilient stocks with low risk scores.
- Hunt for under-the-radar opportunities by casting a wider net across financially solid smaller players with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com