


Elkem (OB:ELK) Backs Furnace Renewal, Is The Stock Still Trading At A Discount?
Why Elkem’s furnace renewal matters for investors
Elkem (OB:ELK) has approved a NOK 260 million renewal of one of its two furnaces at Elkem Rana in Northern Norway, targeting long-term ferrosilicon and Microsilica production and lower emissions.
The project is scheduled to start installation in the first quarter of 2027. It focuses on new off-gas equipment and greater biocarbon use, while the second furnace continues operating to keep output from the site running.
Elkem’s NOK33.68 share price sits against a mixed recent pattern, with the 30 day share price return down 8.58% even as the 90 day share price return is up 11.16% and the 1 year total shareholder return sits at 23.27%. This points to longer term momentum despite shorter term weakness.
Scan for other materials stocks focused on long-term production and emissions upgrades, similar to Elkem’s furnace renewal, by starting with our hand picked list of solid balance sheet and fundamentals (204 results).
Elkem trades at a sizeable discount to some fair value estimates and to analyst targets, yet the recent 30 day share price fall hints at market hesitation. Is that caution mispriced, or is it reflecting real risk before the furnace upgrade pays off?
Most Popular Narrative: 8% Undervalued
Elkem’s most followed narrative pegs fair value at NOK36.67, a touch above the NOK33.68 last close. This frames the furnace renewal against a modest implied discount rather than a deep value gap.
Analysts expect earnings to reach NOK 2.7 billion (and earnings per share of NOK 4.69) by about September 2029, up from NOK 278.0 million today. However, there is a considerable amount of disagreement amongst the analysts, with the most bullish expecting NOK3.3 billion in earnings and the most bearish expecting NOK1.5 billion.
See why 20 investors see Elkem as 8% undervalued.
Result: Fair Value of NOK36.67 (UNDERVALUED)
Still, weaker demand in China and Europe, along with ongoing trade and tariff risks, could pressure Elkem’s volumes and margins enough to challenge this undervalued story.
Find out about the key risks to this Elkem narrative.
Another View: What Elkem’s P/E Is Really Telling You
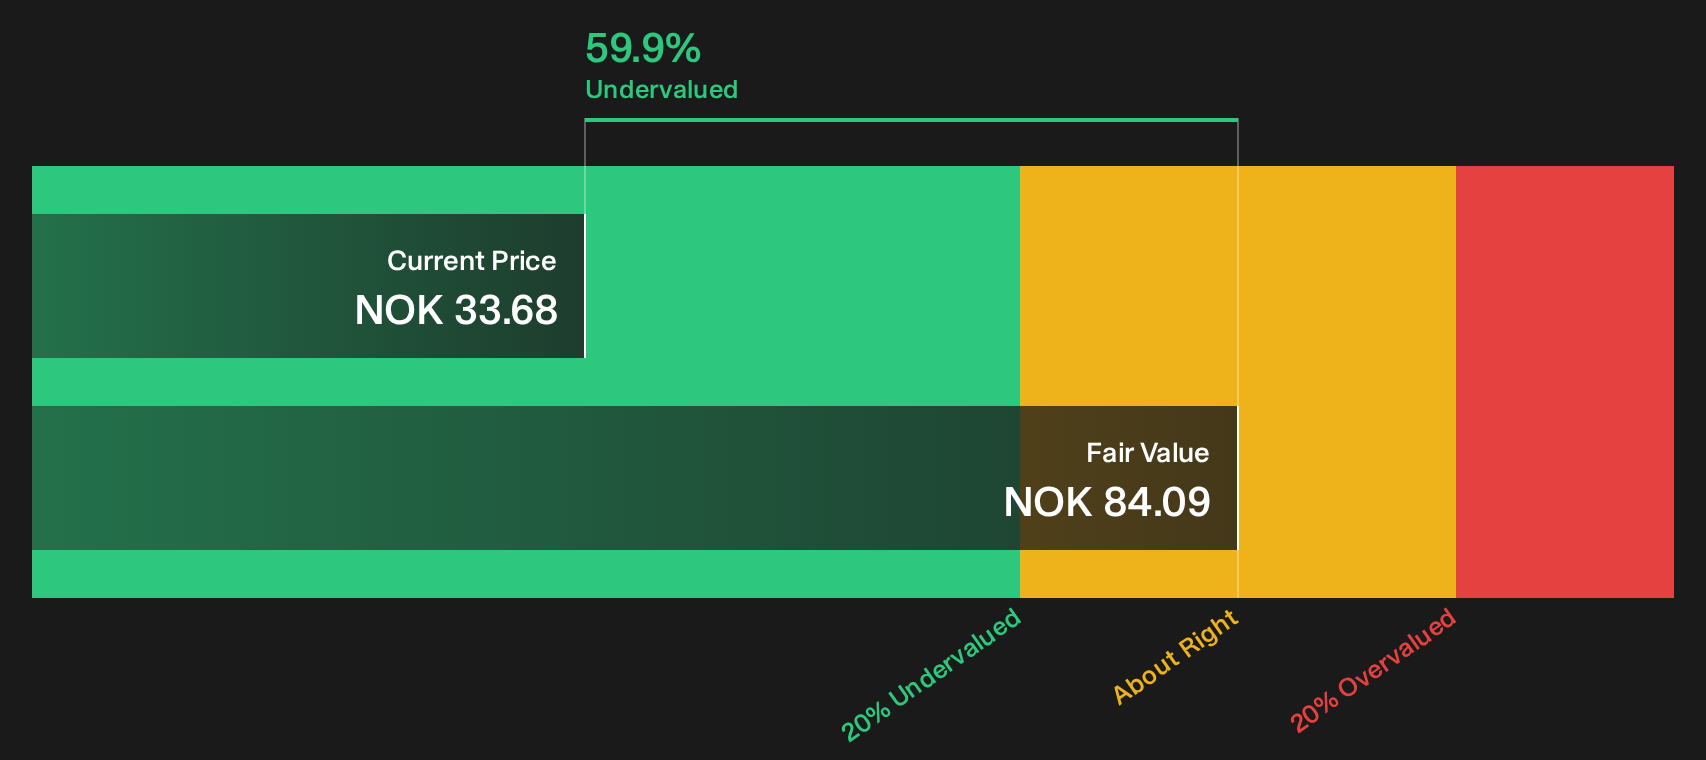
The SWS DCF model points to Elkem trading at about a 59.9% discount to its NOK84.09 fair value estimate, which leans firmly toward an undervalued story. Yet the share currently changes hands on a 43.9x P/E, well above the European Chemicals average of 16.9x and above peer levels of 37.1x. That mix of deep DCF upside and a rich earnings multiple leaves a simple question for you: Which signal should carry more weight in your own work on this stock?
To unpack how that cash flow view was built and what would need to go right for it to hold, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Elkem’s value and furnace renewal can cut both ways, so move quickly through the data, pressure test the risks and rewards, then let 2 key rewards and 2 important warning signs guide your next layer of research.
Looking for more investment ideas beyond Elkem?
The real edge rarely comes from a single ticker. It comes from lining up several strong ideas so you are not relying on one outcome.
Use the Simply Wall Street Screener to quickly test fresh concepts, compare fundamentals in minutes, and spot opportunities that many investors have not yet priced in.
- Target higher quality at lower prices by scanning companies that score well on fundamentals and valuation through the 618 high quality undiscovered gems.
- Prioritise resilience first and focus on businesses with sturdier financial profiles using the 222 resilient stocks with low risk scores.
- Hunt for stronger balance sheets and steadier fundamentals by building your next watchlist from the 126 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com