


Baytex Energy (TSX:BTE) Could Be 13% Undervalued After Bullish Analyst Commentary
Recent analyst commentary has pushed Baytex Energy (TSX:BTE) back into focus for value investors, as the stock is being framed as undervalued using traditional metrics such as the P/S ratio.
Baytex Energy’s CA$6.87 share price comes after a sharp year to date share price return of 51.32% and a 19.48% share price return over the past 90 days. The 1 year total shareholder return of 113.52% suggests momentum has been strong rather than fading.
Scan value opportunities aligned with Baytex Energy’s momentum by reviewing the hand-picked 9 high quality undervalued stocks that exhibit a similar pricing gap relative to traditional valuation metrics.
Baytex Energy has enjoyed a strong run and a rich story around its assets, yet a rising share price does not automatically mean a stretched valuation. Do the current numbers still point to a genuine value case?
Most Popular Narrative: 13.2% Undervalued
The most followed valuation view on Baytex Energy pegs fair value at about CA$7.92, above the recent CA$6.87 close, which frames the current share price as a discount rather than a premium.
The ongoing replacement of over 100% of production on both 1P and 2P reserve bases suggests sustainable reserve growth, which supports future production levels and could result in increased revenue and long-term company valuation.
See why 52 investors see Baytex Energy as 13% undervalued.
Result: Fair Value of CA$7.92 (UNDERVALUED)
Still, Baytex Energy’s story can change quickly if oil prices retreat toward US$60 for a prolonged stretch or if tariffs on Canadian exports tighten further.
Find out about the key risks to this Baytex Energy narrative.
Another View: Baytex Energy Looks Rich On Sales
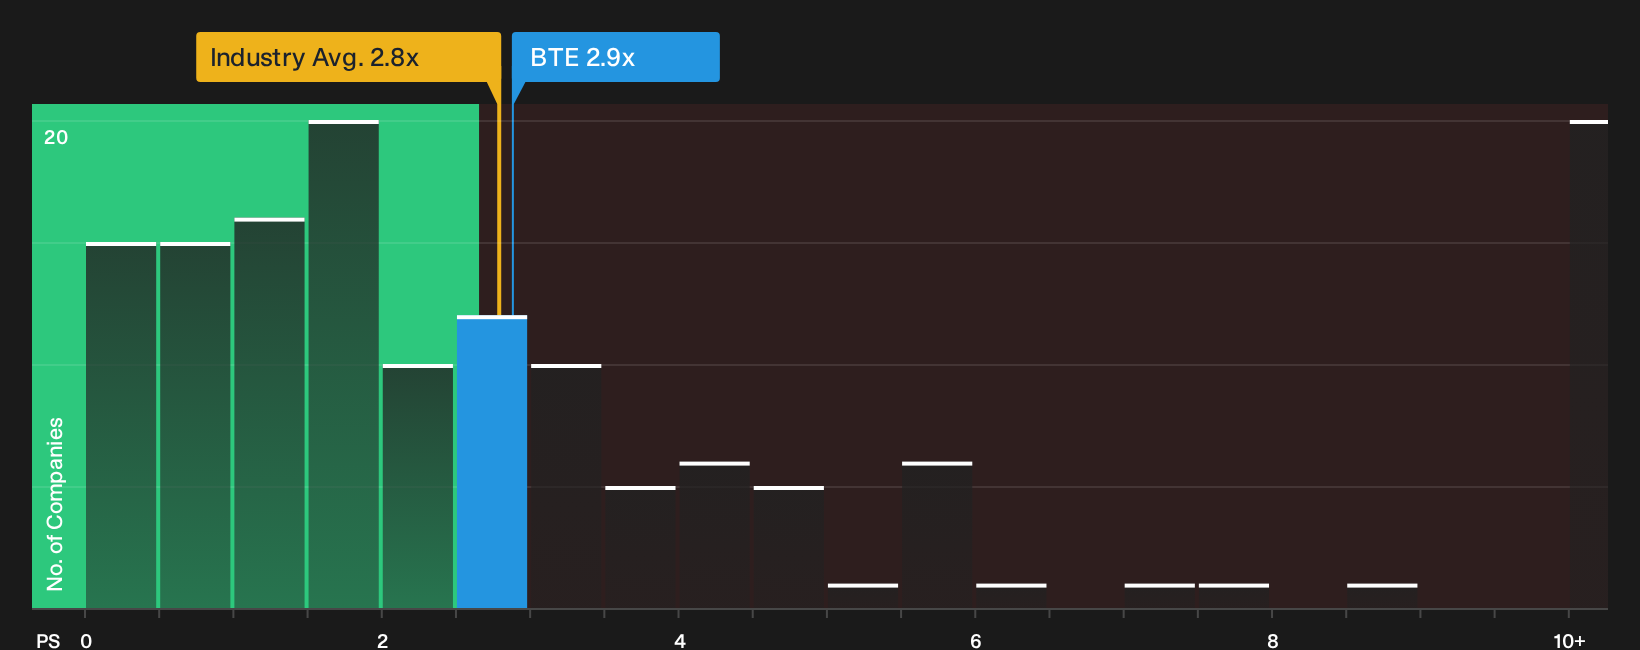
The first narrative paints Baytex Energy as 13.2% undervalued on fair value estimates. A simple P/S lens tells a different story. At 2.9x sales, the stock trades above the Canadian Oil and Gas average of 2.7x and the fair ratio of 2.1x, even though it screens cheaper than peers at 6.6x. If the market ever leans closer to that fair ratio, are investors taking on more valuation risk than they think?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Baytex Energy’s valuation can be confusing, so move quickly from commentary to evidence and stress test the numbers yourself. To see what has investors optimistic about the upside case, review the 1 key reward.
Looking for more Baytex Energy style opportunities?
If Baytex Energy has you thinking about what else might be mispriced, do not stop here. Broader idea hunting often reveals the most interesting setups.
- Chase overlooked potential in smaller companies that already show solid financials by scanning the 19 elite penny stocks with strong financials.
- Zero in on companies that combine quality fundamentals with a pricing gap that may work in your favor through the 9 high quality undiscovered gems.
- Prioritize resilience first and filter for businesses with balance sheets built to handle shocks using the 7 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com