


Wondering Why ABFRL Fell? Here's What The Bears Saw
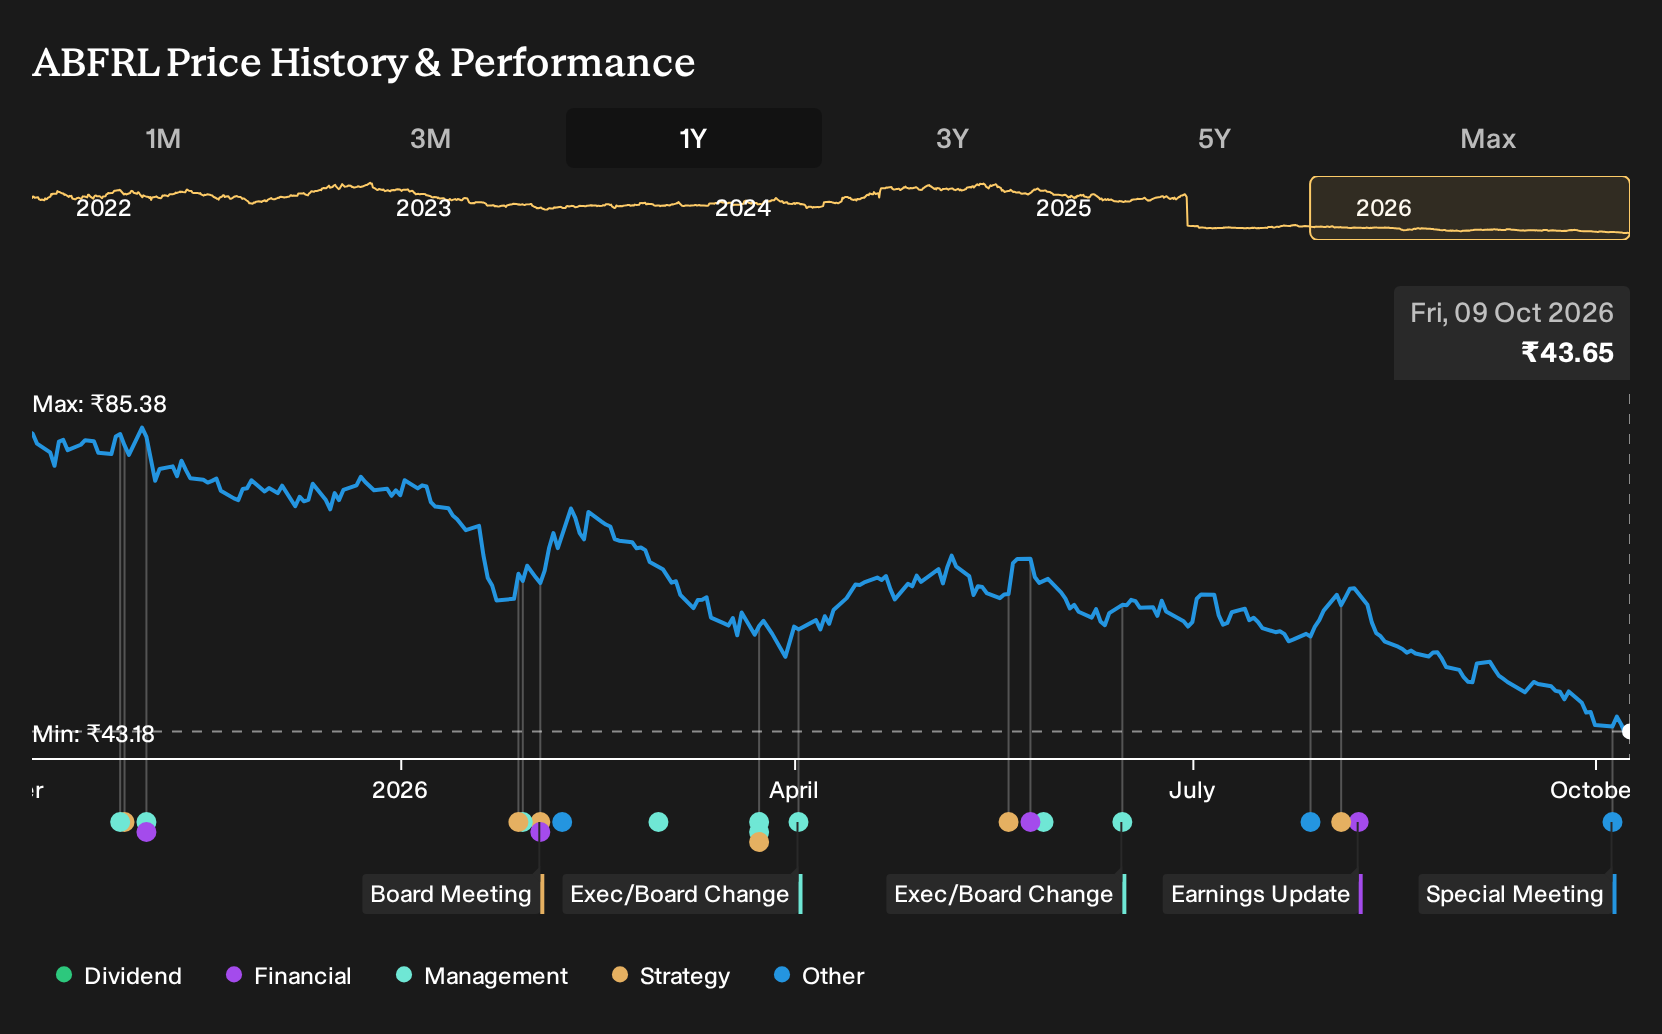
Holding Aditya Birla Fashion and Retail over the past year would have meant a 47.5% loss, including dividends. If you had committed fresh capital in October 2025, that outcome would sting, especially with Q1 2027 showing higher revenue but a continued net loss and only a modestly better margin. So what, exactly, did the original bullish and bearish cases miss about demerger benefits, digital momentum, and margin normalization assumptions?
If the move has made Aditya Birla Fashion and Retail harder to judge, start where the gap is still open and scan 175 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Aditya Birla Fashion and Retail
The shares cost ₹84.57 at the start of the period, and anyone looking at Aditya Birla Fashion and Retail then had two very different stories to consider.
On the bullish side, the Fair Value was framed at ₹103, a notional price based on assumptions about what the business could earn if things went right. The thesis leaned on rapid urbanization and digital commerce, along with potential benefits from the demerger and capital raise.
The bearish view pointed to a Fair Value of ₹58, again a price implied by its own expectations. This perspective focused on rising e-commerce competition, ESG scrutiny, high leverage, and the risk that complex brand portfolios would pressure margins.
What The Results Changed For Aditya Birla Fashion and Retail
Q1 2027 put Aditya Birla Fashion and Retail’s profitability claims under the spotlight. Revenue moved from ₹18,314.6m in Q1 2026 to ₹20,255.6m, while the business still reported a loss, with net income slipping further to ₹2,152.4m in the red. A less negative net margin, from 11.6% to 10.6%, only partly backed the bullish margin story, so the evidence cut both ways.
The lesson is simple. When a thesis leans on margin repair, track net margin alongside sales. Healthy topline growth without a clear path from loss to profit should prompt investors to test how much improvement is already priced into any retail stock.
What Aditya Birla Fashion and Retail’s Drop Leaves You Weighing Today
Aditya Birla Fashion and Retail trades at ₹43.65 today, after a 47.5% loss over the past year. The selected Narrative’s Fair Value sits above this level and rests on the idea that format mix, funding choices and portfolio evolution could eventually reshape earnings and cash generation.
For that higher figure to be supported, a buyer today would have to believe newer platforms and ethnic concepts can collectively reach and sustain profitable scale roughly along the glidepath management has outlined.
"Key Takeaways: Bullish analysts expect Aditya Birla Fashion and Retail to scale its multi-banner portfolio, with both established formats and newer platforms contributing more meaningfully to consolidated growth and improving EBITDA over time. The main thing that has to go right is that investment-heavy newer businesses such as TMRW, OWND, Tasva and other ethnic and premium offerings reach brand and portfolio level profitability broadly in line with management timelines, while Pantaloons and ethnic wear sustain healthy margins."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Before The Next Story Makes Headlines
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 27% below our estimate - uses digital investing platforms to modernise retirement savings and advice workflows.
- Company 2 - 33% below our estimate - supplies power systems and liquid cooling hardware for advanced artificial intelligence data centers.
- Company 3 - 39% below our estimate - scales artificial intelligence tools that score job and service listings for relevance.
Three companies from the same screener. Open every one of the 204 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com