


Cash Recycler Rollout Could Change The Bull Case For Diebold Nixdorf Stock
- Diebold Nixdorf disclosed that stc pay Bahrain has rolled out its first self-service network using DN Series cash recyclers and DN Vynamic Software, connecting physical kiosks with digital wallets, cards and a wide range of payment and remittance services across the country.
- The partnership with stc pay Bahrain highlights Diebold Nixdorf’s push to serve telecom-affiliated financial platforms, extending its hardware and software into emerging, non-bank financial ecosystems that mix cash handling with digital-first services.
- This development may influence how investors view Diebold Nixdorf's role in supporting stc pay Bahrain's digital ecosystem with DN Series.
Scan other payment and fintech operators building similar digital to physical bridges as Diebold Nixdorf with our hand-picked 20 high quality undiscovered gems.
Diebold Nixdorf Investment Narrative Recap
To own Diebold Nixdorf, you need to believe the shift toward higher margin software, managed services and cash recyclers can translate its US$3.9b revenue base into sturdier profitability and cash generation. The stc pay Bahrain rollout fits that story, but on its own does not change the near term picture. That still hinges on service productivity and backlog conversion.
The key near term catalyst remains execution on that US$814m product backlog and the cost programs that support service margins. The biggest risk is that high debt, service margin pressure and any delay in large tenders or deployments choke free cash flow, leaving less room to reduce leverage or reinvest.
The stc pay Bahrain deployment leans directly on DN Series hardware and DN Vynamic Software, the same tools analysts already highlight in branch automation pilots and Vynamic led managed services. That matters because it shows Diebold Nixdorf trying to apply its cash recycling and middleware stack beyond traditional banks into telecom affiliated wallets.
For you, the question is whether these kinds of projects scale quickly enough to offset risks like high memory costs in retail devices, higher cash taxes in Germany and ongoing fleet renewal pressure in North America. Analyst expectations for faster earnings growth remain secondary to whether these software heavy, service rich deals execute cleanly and turn into recurring revenue.
Diebold Nixdorf's current analyst story points to US$4.2b in revenue and US$358.7m in earnings by 2029, based on an assumed 2.6% yearly increase in sales and a move from US$111.2m in earnings today to that higher level, which is about a 3.2x step up from current profit.
Uncover how Diebold Nixdorf's fair value indicates a 54% potential upside to its current price, which could narrow quickly if sentiment follows the earnings story.
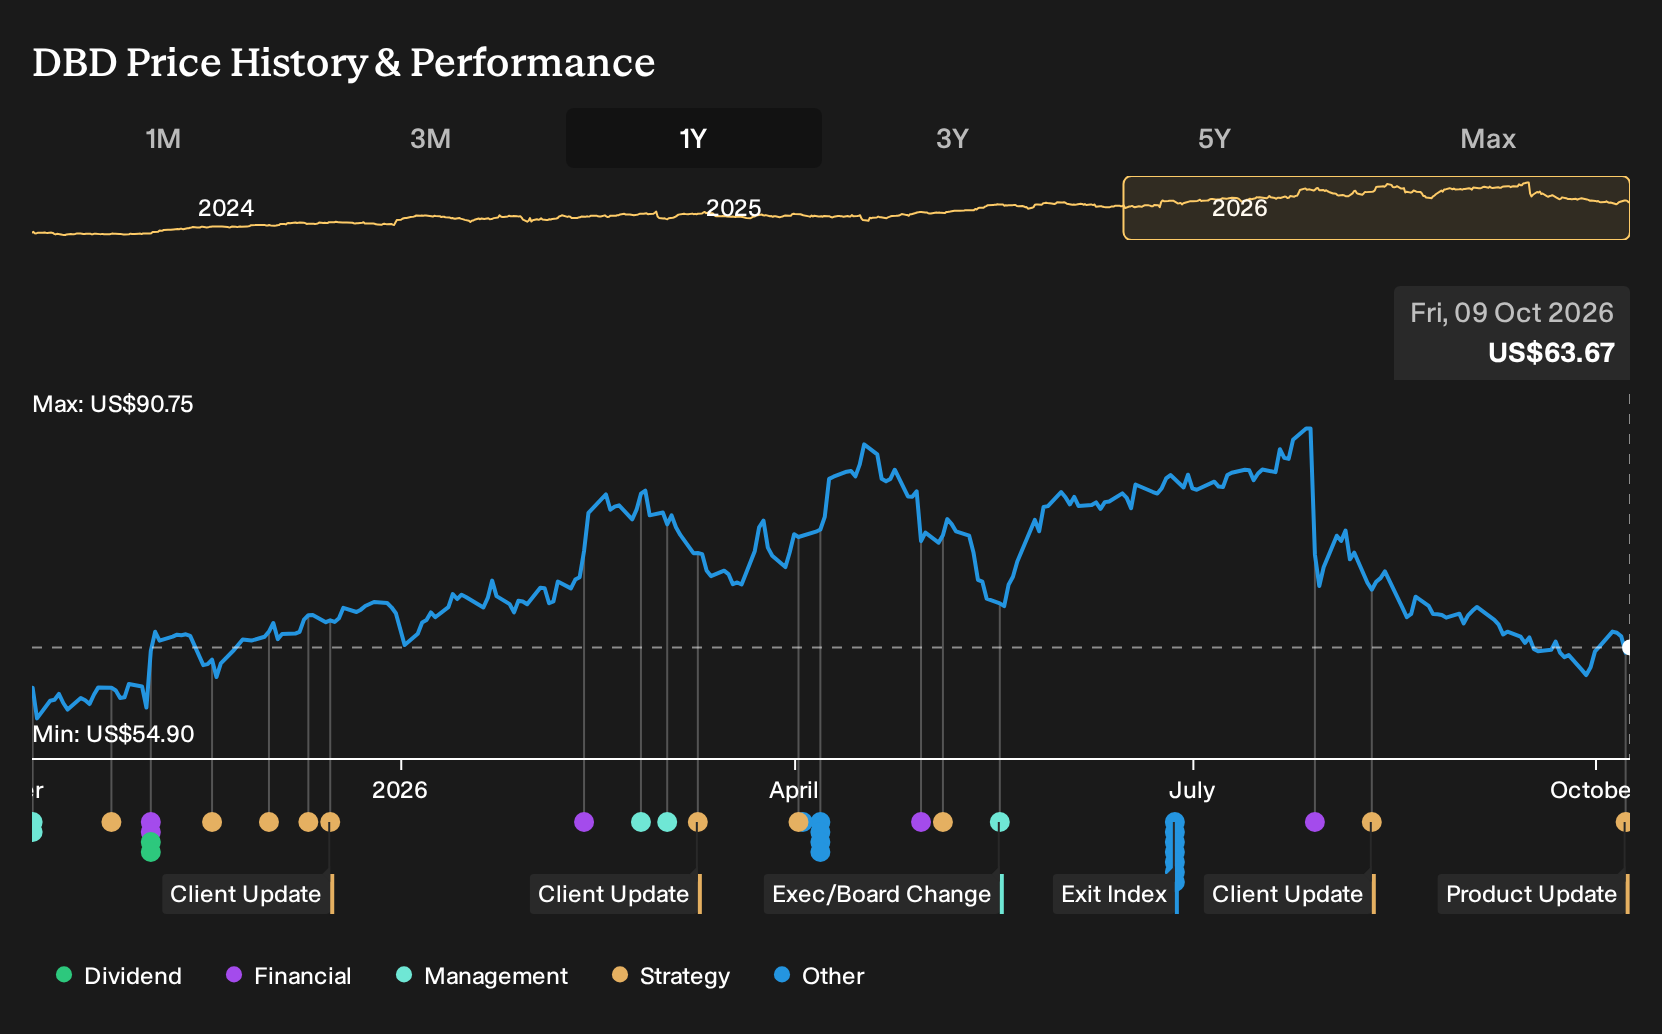
Exploring Other Perspectives
One alternate view is that Diebold Nixdorf’s biggest swing factor is not backlog conversion but weaker long term demand for physical banking gear as payments keep digitising. The most cautious analysts were modelling roughly US$4.2b of revenue and about US$355.7m of earnings by 2029 before this stc pay Bahrain rollout. That is only slightly below consensus, yet it reflects a more hesitant story that you might see shift if telecom linked deployments like this start to look repeatable. You do not need to pick a side today. Instead, treat this as a reason to compare several narratives and decide which assumptions feel closer to how you think this business could evolve.
Explore 7 other Diebold Nixdorf fair value estimates, including one that suggests there could be as much as 14% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Diebold Nixdorf research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Diebold Nixdorf. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Diebold Nixdorf's overall financial health at a glance.
Looking For More Investment Ideas Beyond Diebold Nixdorf?
If the Diebold Nixdorf story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you line up other potential opportunities that match your risk and income preferences.
- For investors who want quality and value in the same place, start with companies flagged as 28 high quality undervalued stocks that may offer stronger fundamentals at a discounted price.
- If balance sheet strength matters most to you, focus on businesses screened for resilient finances and cash support using our list of solid balance sheet and fundamentals (25 results).
- For readers who care about durability as much as upside, filter for companies with steadier profiles and muted risk markers using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com