


Cautious Outlook Might Change The Case For Investing In Tapestry (TPR)
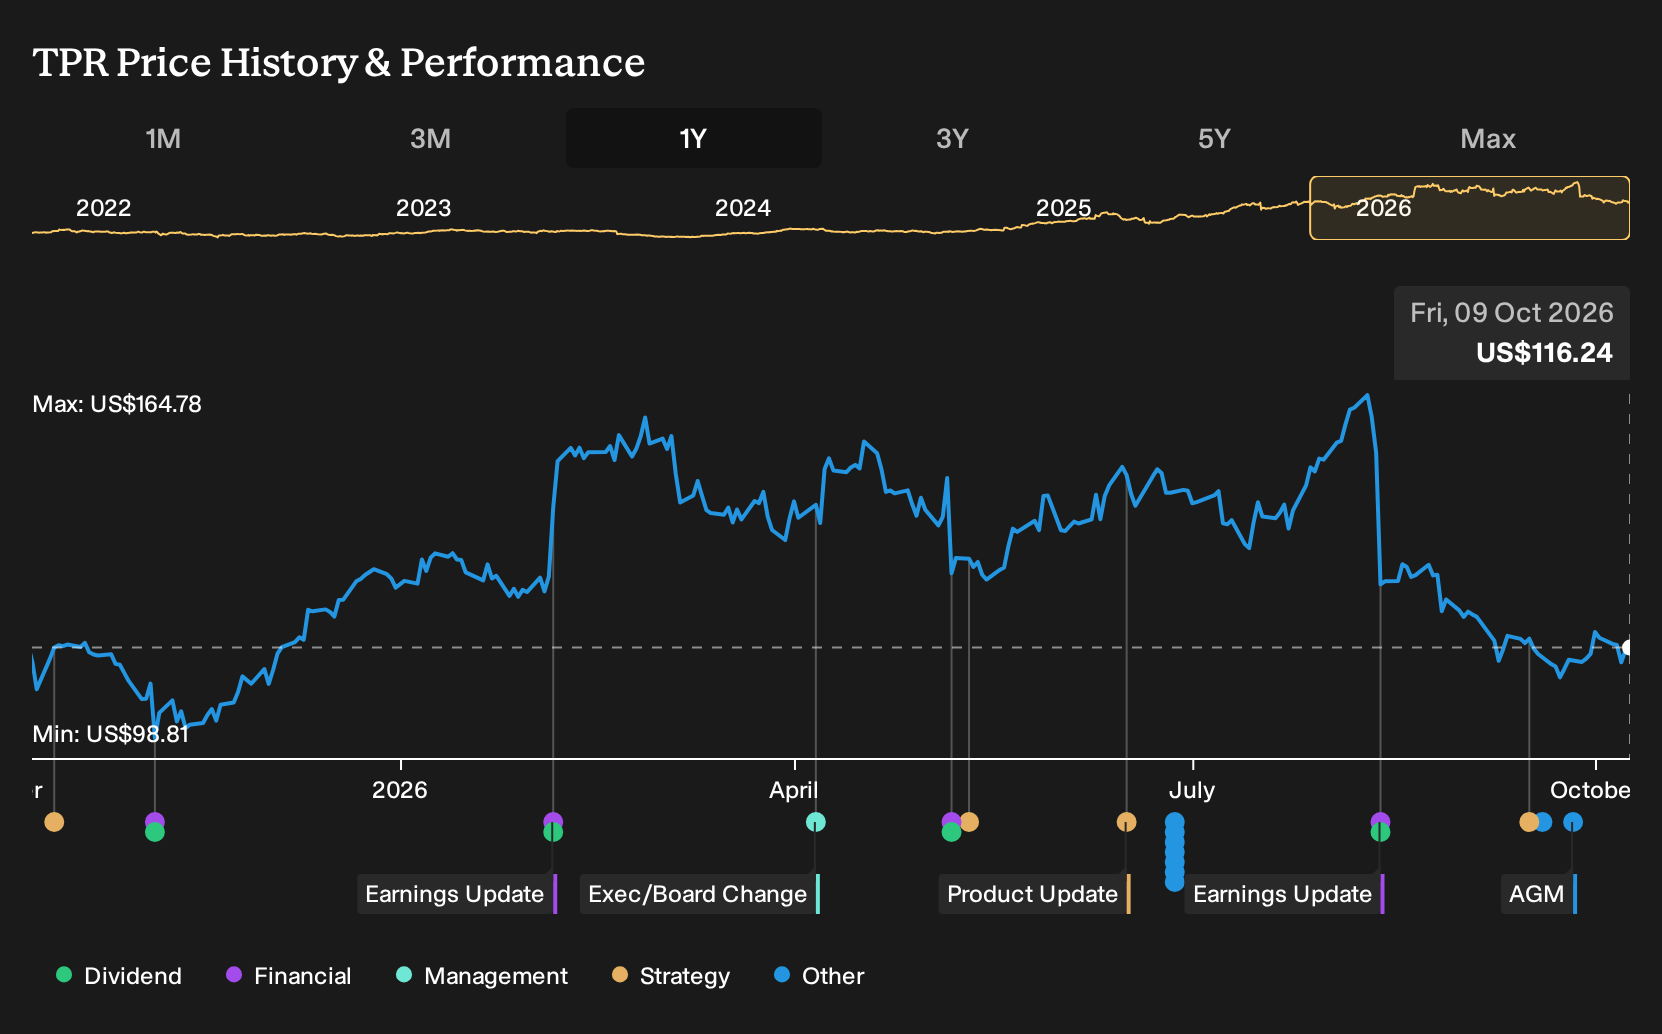
- Tapestry recently reported quarterly results with 8.9% revenue growth in line with forecasts, an EBITDA figure ahead of expectations, and full year revenue guidance that matched analyst estimates, while issuing a cautious outlook for the next quarter.
- Management lifted the quarterly dividend by 16% even as it signalled softer near term demand. This highlights confidence in cash generation but also sharper scrutiny on how resilient Tapestry’s profitability and brand portfolio really are.
- We will now see how Tapestry’s investment narrative could be reshaped by cautious guidance paired with a 16% dividend increase.
Tapestry Investment Narrative Recap
To own Tapestry, you need to be comfortable with a simple idea. The long term story leans on Coach and the broader direct to consumer engine continuing to draw in younger shoppers globally, while Kate Spade stops dragging on group results. The latest quarter, with revenue growth in line with forecasts and an EBITDA beat, does not materially change that bigger picture.
The short term hinge remains whether consumer demand justifies the heavier marketing and omnichannel spend that Tapestry is already shouldering. Cautious guidance puts more pressure on execution here. The main operational risk still sits with prolonged weakness at Kate Spade and any renewed tariff or duty cost pressure that crimps margins.
The 16% dividend increase is the clearest new data point for you to weigh against that backdrop. Management is effectively saying the business can return more cash while still funding direct to consumer expansion, AI and data projects, and brand work at Kate Spade, even as it guides more cautiously for the next quarter.
For income focused holders, this higher payout intersects directly with the key catalysts and the risk list. Stronger cash returns may look more attractive when the share price has cooled and analysts see Tapestry trading below some intrinsic value estimates. However, a richer dividend also leans on consistent free cash flow and a balance sheet already carrying a high level of debt.
Tapestry's narrative projects US$9.6b revenue and US$1.9b earnings by 2029. This projection assumes 6.3% yearly revenue growth and an earnings increase of about US$400m from US$1.5b today.
Uncover why Tapestry's fair value indicates a 43% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate Tapestry angle treats dividend growth as a side effect of a much bigger earnings story. The most optimistic analysts were pencilling in around US$8.4b to US$8.5b of revenue and US$7.80 to US$7.90 of EPS in FY27 before this update. That is a far brighter script than consensus, and it might shift again after this quarter. Use it as a reminder that your view can differ sharply from both camps.
Explore 3 other Tapestry fair value estimates, including one that suggests as much as 63% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Tapestry research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tapestry. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tapestry's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tapestry?
If you are weighing Tapestry against other options, it helps to scan a wider field of potential opportunities that suit your risk profile and income needs. The Simply Wall St Screener lets you filter for very specific traits so you can build a watchlist that actually reflects how you like to invest, rather than a generic basket.
- For investors who want cash returns without stretching on quality, you can focus on income opportunities with our curated list of 8 dividend fortresses.
- If your priority is financial resilience and you care about balance sheets first, narrow your choices with a list of solid balance sheet and fundamentals (25 results) that can help you sleep better at night.
- For those hunting for under followed opportunities with robust fundamentals, broaden your research with a 20 high quality undiscovered gems that might not yet be on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com