


CAE (TSX:CAE) Moves To Settle Class Action, Is It Still 23% Below Fair Value?
CAE (TSX:CAE) is back in focus after agreeing to a proposed CAD 38.25 million class action settlement in Québec, a legal step that helps define potential costs and reduce uncertainty for shareholders.
CAE shares closed at CA$33.86 after the settlement news, with a 1-day share price return of 2.82% that contrasts with a year-to-date share price return down 20.24%. Short-term moves have been choppy, while the 3-year total shareholder return of 10.62% points to a mixed longer record.
Scan beyond CAE and compare how other contractors are pricing in legal and contract risk using our curated list of 7 resilient stocks with low risk scores to build a more resilient watchlist.
With the legal bill largely quantified and CAE at CA$33.86 after a sharp one day bounce, the real call now is whether to step in here or wait for a cleaner entry on price.
Most Popular Narrative: 23% Undervalued
CAE last traded at CA$33.86, while the most widely followed valuation narrative points to a fair value near CA$44.25, which frames the recent legal settlement against a larger story about cash flows and earnings power.
Accelerating adoption of digital, immersive, and simulation technologies, exemplified by CAE's recent partnerships with Apple and rollout of its Flightscape analytical platform, positions the company to capture new, higher-margin and recurring revenue streams as the industry modernizes and airlines seek efficiency. This may positively impact net margins and recurring cash flow.
See why 31 investors see CAE as 23% undervalued.
Result: Fair Value of CA$44.25 (UNDERVALUED)
Still, CAE's sizeable CA$3.2b net debt and softer civil training utilization could pressure earnings and risk undermining confidence in that 23% undervaluation story.
Find out about the key risks to this CAE narrative.
Another View On CAE’s Valuation
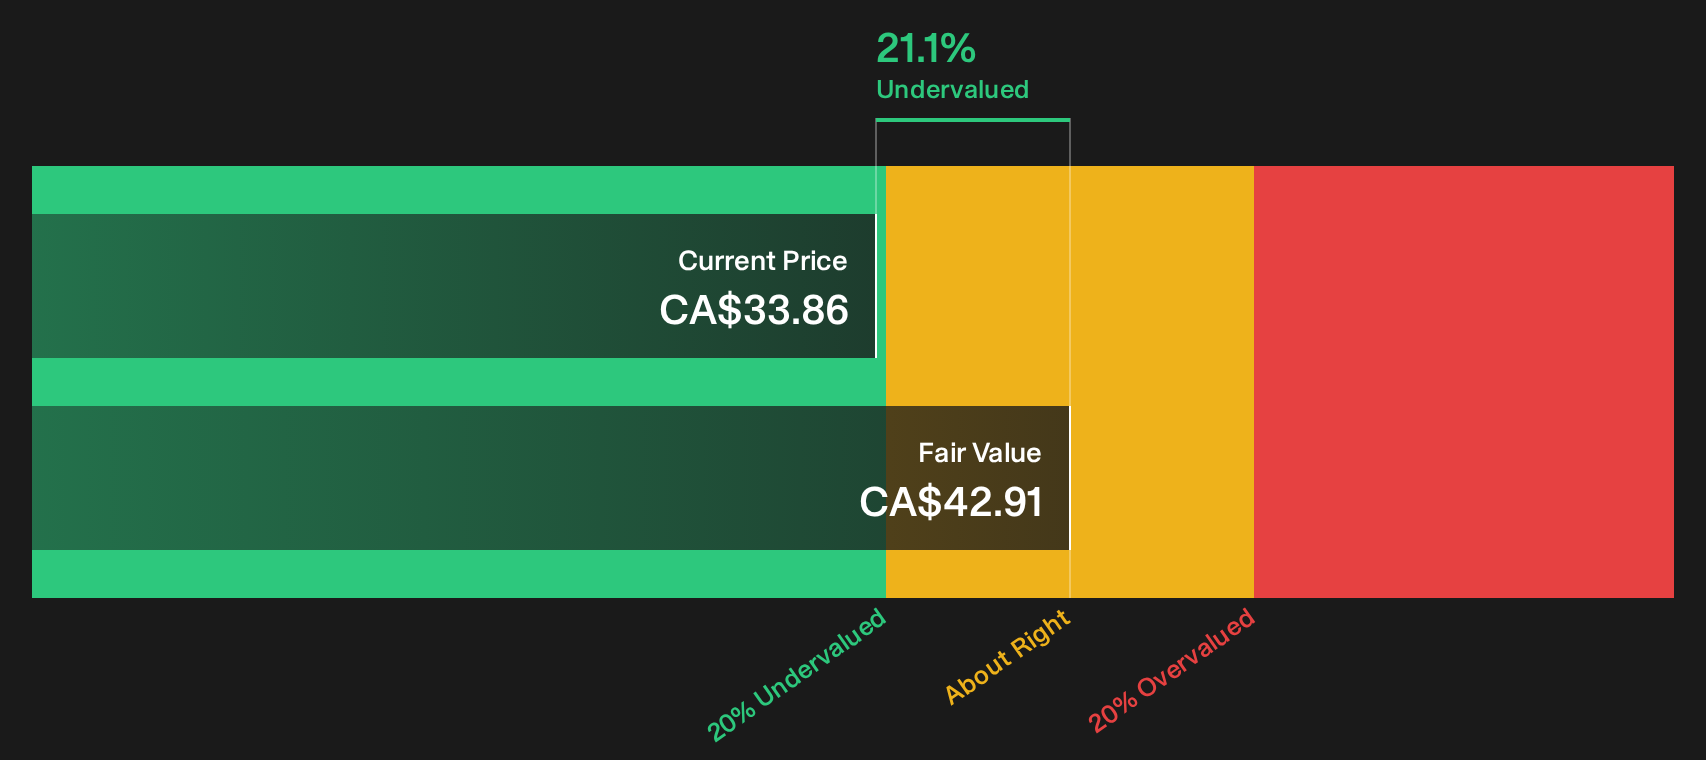
On one hand CAE screens as about 21% below an estimated fair value of CA$42.91 using the SWS DCF model, which points to undervaluation based on future cash flows. On the other hand, the current P/E of 37.8x sits above a fair ratio of 31.6x and above both industry and peer averages, which raises the question of how much execution risk is already priced in.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the split between CAE’s risks and rewards still feels unresolved, act quickly and review the details so you can set your own stance with 3 key rewards and 2 important warning signs
Looking for more CAE-sized opportunities?
Do not stop your research at CAE. Use the Simply Wall Street Screener to quickly surface fresh ideas that fit your risk, income, and value goals.
- Target potential mispricing by scanning a curated pool of quality companies that screens for valuation support using the 9 high quality undervalued stocks.
- Strengthen your watchlist with businesses that pair healthier balance sheets with solid fundamentals by tapping into the list of solid balance sheet and fundamentals (7 results).
- Get ahead of the crowd by filtering for under-the-radar opportunities with strong financial traits through the 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com