


Radware Stock In Focus After New AI Agent Security Launch
- Radware reported its H1 2026 Global Threat Analysis findings and introduced Radware Agent Trust Management, a service that monitors AI agents’ stated intent and real actions to manage access to sensitive applications, data and business workflows.
- The new Agent Trust Management tool seeks to move customers beyond simple bot blocking by giving security teams session level visibility, intent tracking and permission based controls tailored to AI agent traffic across sectors like e commerce, finance and travel.
- Next, the focus shifts to how Radware's attempt to granularly govern AI agent intent and permissions could influence its broader investment narrative.
Scan beyond Radware and this AI agent security theme by comparing it with 92 AI infrastructure stocks that are also gearing their businesses around rising machine to application traffic.
What Is Radware's Investment Narrative?
Radware’s story appeals most if you believe security budgets keep shifting toward application level protection and AI specific controls, not just perimeter tools. Earnings have grown 16% per year over the past 5 years, yet the stock trades on a rich 75.5x P/E versus about 31x for US software peers and above an estimated future cash flow value of US$19.48 per share. That premium leans on continued execution in areas like cloud services, where capital intensity is relatively light but customer trust and product depth matter more than sheer scale.
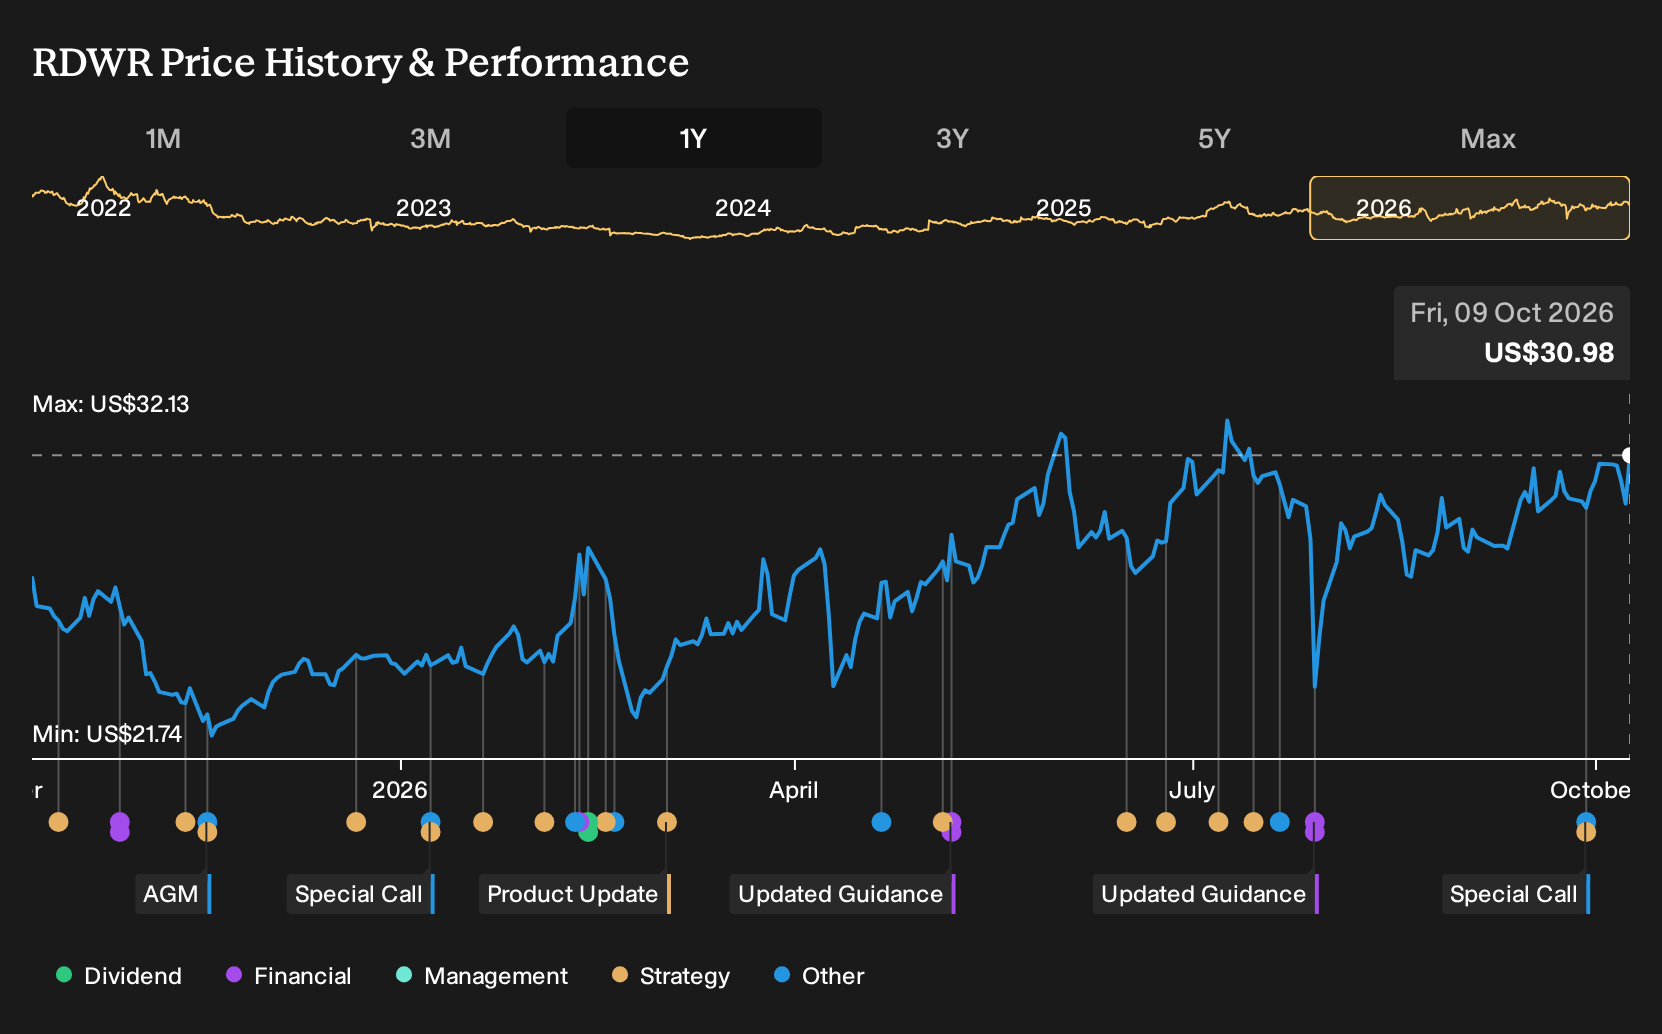
The new Agent Trust Management launch fits directly into that thesis. It keeps Radware tied to demand around bot and AI agent traffic instead of more generic security spending. In the short term, the bigger questions are less about the product itself and more about whether this kind of offering can convert into higher quality, recurring revenue while earnings are influenced by large one off items and insiders have been selling stock during a strong 1 year share price run. Pricing power, deal cycles and the ability to justify that high multiple are now in clearer view.
Even so, there is a less comfortable angle in this story that centers on ...
There's only one way to know the right time to buy, sell or hold Radware. Head to Simply Wall St's company report for the latest analysis of Radware's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$19.48 and US$30.50 per share, which already shows how far opinions on Radware can stretch. With these views set before the Agent Trust Management launch, you can treat the new AI agent focus as a fresh lens and explore a wider spread of community perspectives.
Explore another Radware fair value estimate, including one that suggests as much as 37% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Radware research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Radware. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Radware's overall financial health at a glance.
Looking For More Ideas Beyond Radware?
If you want to pressure test your thesis on Radware against other opportunities, a quick scan through a few tailored stock lists can help you see what else matches your priorities on value, income, or balance sheet strength.
- For investors hunting for mispriced quality, compare Radware with a curated set of potentially underappreciated companies by reviewing 28 high quality undervalued stocks.
- If consistent income matters most to you, line up Radware against businesses screened for robust yields and stability through the 8 dividend fortresses.
- When capital preservation sits near the top of your checklist, balance your view on Radware with the 31 resilient stocks with low risk scores that score well on resilience and downside protection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com