


Preferred Bank (PFBC) Stock Looks Inexpensive As Earnings Support Comes Into Focus
Preferred Bank has delivered a strong share price run over the last few years, which now puts more attention on whether the current valuation is fully supported by its earnings power. With the stock recently closing at US$102.58, the key issue for you is how much of that move reflects the underlying profitability of the business versus changing market expectations.
- Over the past 3 years the stock has gained 82.5%, which puts a lot of weight on whether current earnings can carry that kind of rerating.
- The bank leans on a focused commercial lending model and depends heavily on how efficiently it converts that loan book into sustainable earnings, which can influence how much investors are willing to pay for each dollar of profit.
- Your read on Preferred Bank is one view; the desks covering it have another. See what analysts think Preferred Bank's shares could be worth.
The issue now is whether Preferred Bank's current share price is adequately backed by the earnings it is generating today.
If you want to cross check Preferred Bank against other ideas built around earnings support, a focused stock screen is a useful next step via 28 high quality undervalued stocks.
Does Preferred Bank Look Undervalued on Earnings?
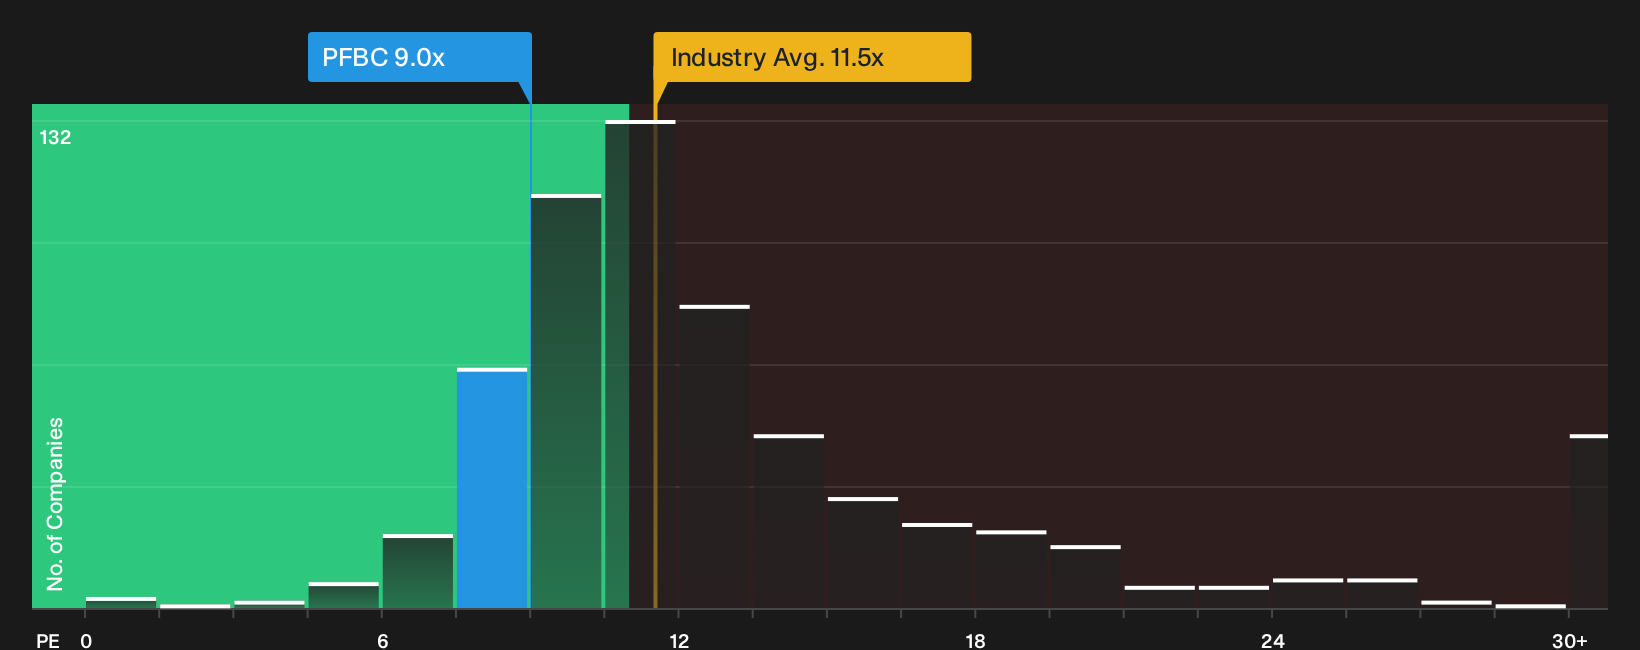
The P/E ratio is a useful lens for Preferred Bank because earnings sit at the center of how investors usually judge lenders. At the recent share price, the stock trades on a P/E of about 9.0x, compared with an industry average of roughly 11.5x for banks and a peer group closer to 13.4x. That places Preferred Bank at a visible discount to both its sector and a set of comparable institutions.
The internal fair multiple estimate, which blends the bank's profit profile, capital base, size and risk inputs, points to a higher P/E than where the shares trade today. For you as a shareholder or potential buyer, that gap suggests the market is pricing Preferred Bank more cautiously than the model implies, even after accounting for sector specific risks. The key question is whether you think the current earnings level and balance sheet strength justify a closer alignment with that implied multiple over time. Explore the numbers behind Preferred Bank's P/E valuation.
The Preferred Bank Narrative: What Would Justify Today's Price?
Preferred Bank Narratives pick up where the valuation puzzle leaves off. They explain which assumptions on growth, margins and earnings would need to hold for Preferred Bank's current price to appear meaningfully higher or lower. Each idea treats fair value as a hypothesis about the business that you can revisit over time, rather than a static snapshot. They are available on Simply Wall St's Community page for you to explore when you want that extra layer of context.
One of the top community narratives on Preferred Bank: 10% undervalued
"The main thing that has to go right is that Preferred Bank sustains its current balance of credit quality, measured loan growth and active capital return…"
Discover why this Narrative puts Preferred Bank at 10% undervalued.
Preferred Bank’s valuation still leaves one crucial unknown
Price and earnings only tell part of the story for Preferred Bank, because recent research has also flagged specific risk checks that could change how you view the whole profile. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com